
Applied Materials (AMAT) Climbed, What Is Behind The Latest Attention?
Applied Materials (AMAT) just expanded its EPIC Center collaborations, bringing in BE Semiconductor Industries and KIOXIA to co-develop advanced packaging and memory architectures tailored to growing AI infrastructure requirements.
The latest EPIC Center partnerships arrive during a powerful run in Applied Materials’ shares, with a 30-day share price return of 23.17% and a year-to-date share price gain of 100.86%, even after a 10.45% decline over 90 days. Total shareholder return over five years sits at 345.93%, reflecting long-term momentum as investors reassess both growth potential and execution risk around AI driven demand.
Scan other AI infrastructure plays that echo Applied Materials’ packaging and memory push by reviewing the hand picked 90 AI infrastructure stocks.
Applied Materials now trades well below the average analyst price target after a sharp run and a recent pullback. Is that gap signaling market caution that is misplaced, or is it still catching up with the risks being priced in?
Most Popular Narrative: 14% Undervalued
Applied Materials last closed at $540.04, while the most followed narrative pins its fair value around $627.66. This suggests the market is pricing the stock below those modeled assumptions and leaves investors to judge whether that gap reflects opportunity or underestimated risk.
The ongoing explosion in data creation and rapid adoption of digital transformation (IoT, automotive, industrial automation) continue to accelerate wafer fab buildouts globally, with over 100 new fabs or expansions tracked this year and governments incentivizing regional manufacturing. Applied's broad portfolio and investments in local manufacturing infrastructure (for example, new Arizona and EPIC centers) position it to capture a greater share of this growing and more geographically diverse capital expenditure, supporting both revenue growth and margin resilience.
See why 312 investors see Applied Materials as 14% undervalued.
Result: Fair Value of $627.66 (UNDERVALUED)
Still, the narrative around Applied Materials could be tested if export restrictions in China tighten further, or if a few major customers pull back on wafer fab spending.
Find out about the key risks to this Applied Materials narrative.
Another View On Applied Materials’ Valuation
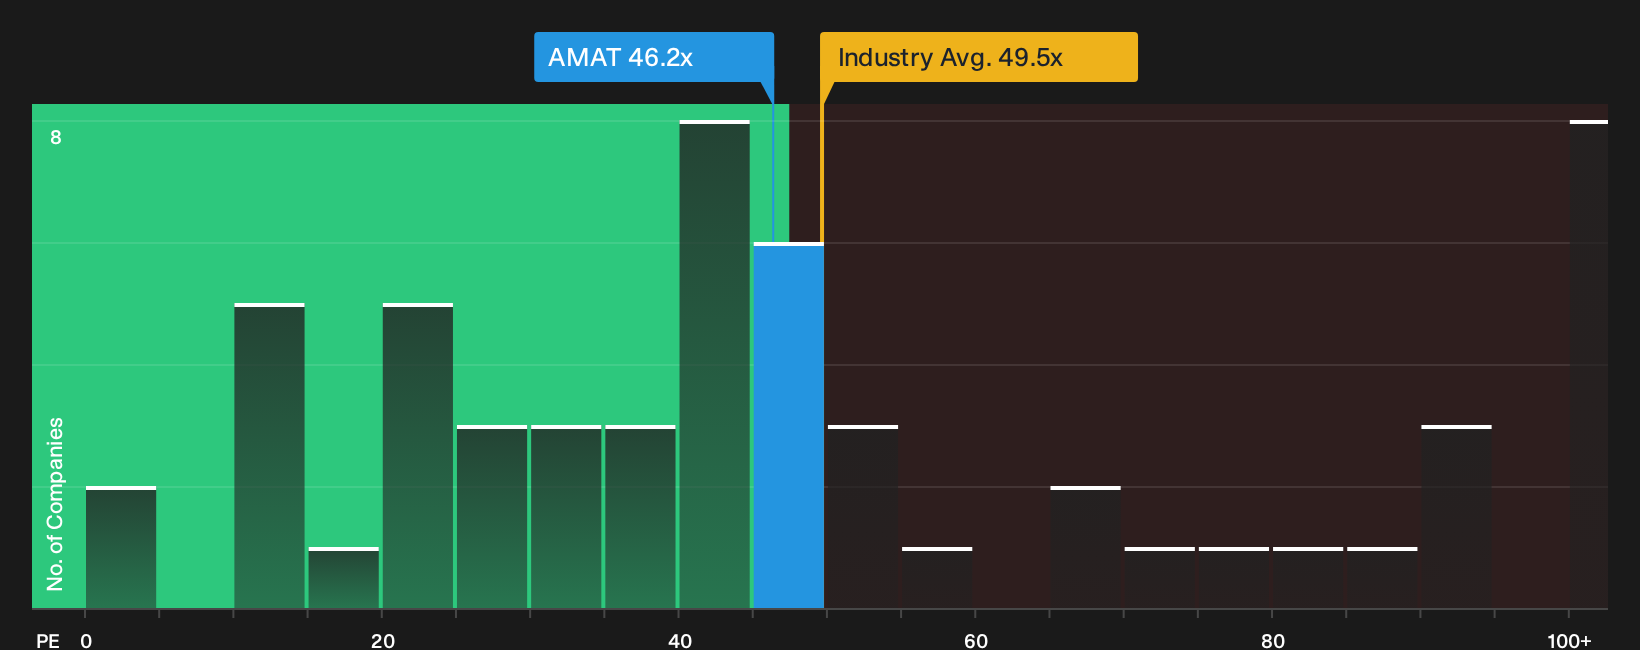
The earlier narrative leans on analyst fair value around $627.66 and a bullish growth path. A second lens tells a cooler story. Applied Materials trades on a P/E of 46.2x while the fair ratio sits at 44.5x, so the market is already paying a premium to where that ratio could drift.
This multiple is slightly below both peer and US Semiconductor industry averages of 49.4x and 49.5x, yet still above the fair ratio. That points to limited room for error if sentiment or earnings expectations soften from here.
Our valuation breakdown unpacks this gap in more detail. It can help you judge whether paying above the fair ratio feels comfortable for your own risk profile, or whether it looks like a crowded trade that needs stronger conviction to hold. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Applied Materials so far. If you want a clearer signal, act quickly: pull up the full data set and review the 3 key rewards and 1 important warning sign.
Hunting for more ideas beyond Applied Materials?
Do not stop with one opportunity. Use the Simply Wall Street Screener to spot fresh angles, compare setups, and pressure test your thinking against different types of stocks.
- Target potential mispricings by scanning a curated set of 31 high quality undervalued stocks that pair solid fundamentals with more attractive entry points.
- Build a sturdier core for your portfolio by focusing on companies screened for balance sheet strength through the list of solid balance sheet and fundamentals (26 results).
- Add income-focused ideas to your watchlist by reviewing a group of 7 dividend fortresses that combine higher yields with business resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com