
Bank of Nova Scotia (TSX:BNS) Expands Buyback Approval, Is The Stock Fully Priced?
Bank of Nova Scotia (TSX:BNS) drew fresh attention after regulators approved a sharp expansion of its normal course issuer bid, increasing the ceiling on share repurchases that can be cancelled on the market.
For context, Bank of Nova Scotia shares now trade at CA$129.93, with a 90 day share price return of 6.16% and a year to date share price gain of 26.88%. The 1 year total shareholder return of 49.08% and very large 3 year total shareholder return above 7x suggest strong longer term momentum, even as the stock recently dipped 1.82% on a 7 day share price basis and saw brief pressure around sector wide moves in Canadian banks and its latest fixed income issuance.
Compare Bank of Nova Scotia's buyback fueled momentum with other potential opportunities by scanning our hand picked list of 6 high quality undervalued stocks.
Bank of Nova Scotia now trades only slightly below analyst targets yet carries a much wider implied discount to intrinsic value. Is the market being prudently cautious after the buyback news, or overly conservative on this bank?
Most Popular Narrative: 2% Undervalued
On the most followed narrative, Bank of Nova Scotia screens as slightly undervalued, with an implied fair value of CA$132.71 against the current CA$129.93 share price. This puts the recent buyback expansion into sharper context for long term holders.
Expansion of banking and wealth management services in high-growth Pacific Alliance countries (Mexico, Peru, Chile, Colombia) positions BNS to capture revenue growth from increasing financial inclusion and rising middle-class demand for loans and investment products, supporting future top-line and earnings expansion.
Accelerated investment in digital platforms, including AI-driven solutions and enhanced online banking capabilities, is expected to drive operational efficiency, reduce costs, and boost net margins through scalable customer acquisition and improved client experiences.
See why 180 investors see Bank of Nova Scotia as 2% undervalued.
Result: Fair Value of CA$132.71 (UNDERVALUED)
Still, Bank of Nova Scotia faces two clear pressure points: exposure to Latin American volatility and sensitivity to any downturn in Canadian housing and related credit quality.
Find out about the key risks to this Bank of Nova Scotia narrative.
Another View On Bank of Nova Scotia’s Valuation
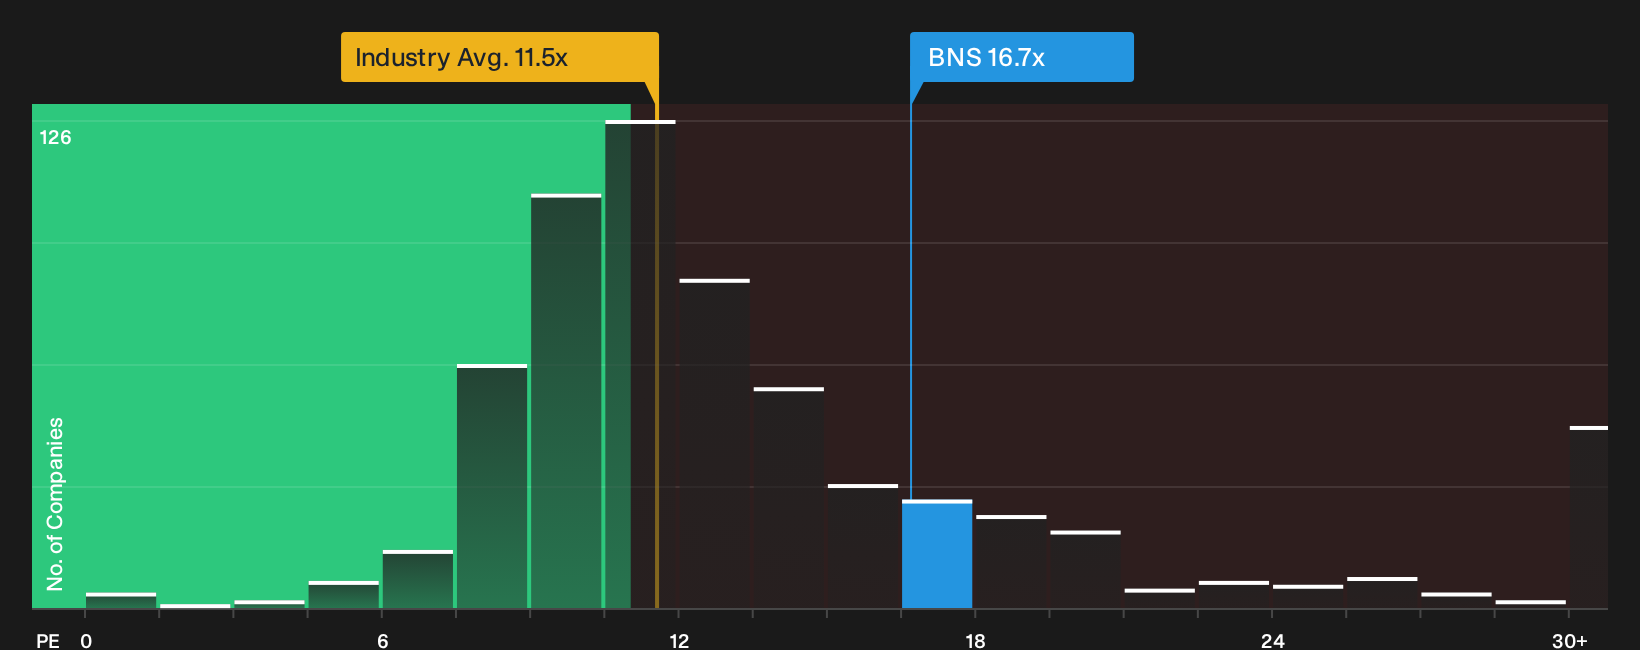
There is a very different signal coming from plain P/E math. Bank of Nova Scotia trades on 16.7x earnings versus 11.5x for the wider North American banks group and roughly 17x for close peers, while its fair ratio is estimated at 17.6x. That points to limited cushion if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Bank of Nova Scotia story points in different directions, so move quickly, review the full data set carefully, and weigh the upside against the issues highlighted in 4 key rewards and 1 important warning sign.
Looking for more Bank of Nova Scotia sized ideas?
If you stop with Bank of Nova Scotia, you only see one angle. Cast the net wider, or risk missing sectors, regions, and balance sheets that better match your goals.
- Target potential deep value by scanning a curated pool of 6 high quality undervalued stocks that combine solid fundamentals with compressed valuations.
- Lock in income potential by reviewing a focused set of 1 dividend fortresses that already clear a 5% yield hurdle.
- Sleep easier by filtering for 8 resilient stocks with low risk scores built around resilient business models and stronger risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com