
Albemarle (ALB) Stock Stays Above Fair Value On Sales Pressure
Albemarle has seen its share price fall back, with the stock closing at US$104.59 after a series of declines. This puts a spotlight on a simple question for investors who care about valuation: Are you paying a sensible price for Albemarle's current sales, or has the recent slide still not brought the stock into line with its underlying revenue base?
- Over the past 5 years, Albemarle's share price has fallen 48.3%, which makes the link between its current market value and its sales a crucial issue.
- The business is heavily tied to selling materials such as lithium, so the level and stability of those sales can directly shape what looks reasonable to pay for each dollar of revenue.
- There is a second opinion on Albemarle worth weighing. See what analysts think Albemarle's shares could be worth.
The issue now is whether Albemarle's current share price is adequately supported by its sales when lined up against the Fair Ratio benchmark.
If you are comparing Albemarle with other opportunities that focus on valuation, it can be helpful to review it alongside companies in the 31 high quality undervalued stocks.
Does Albemarle Look Pricey on Sales?
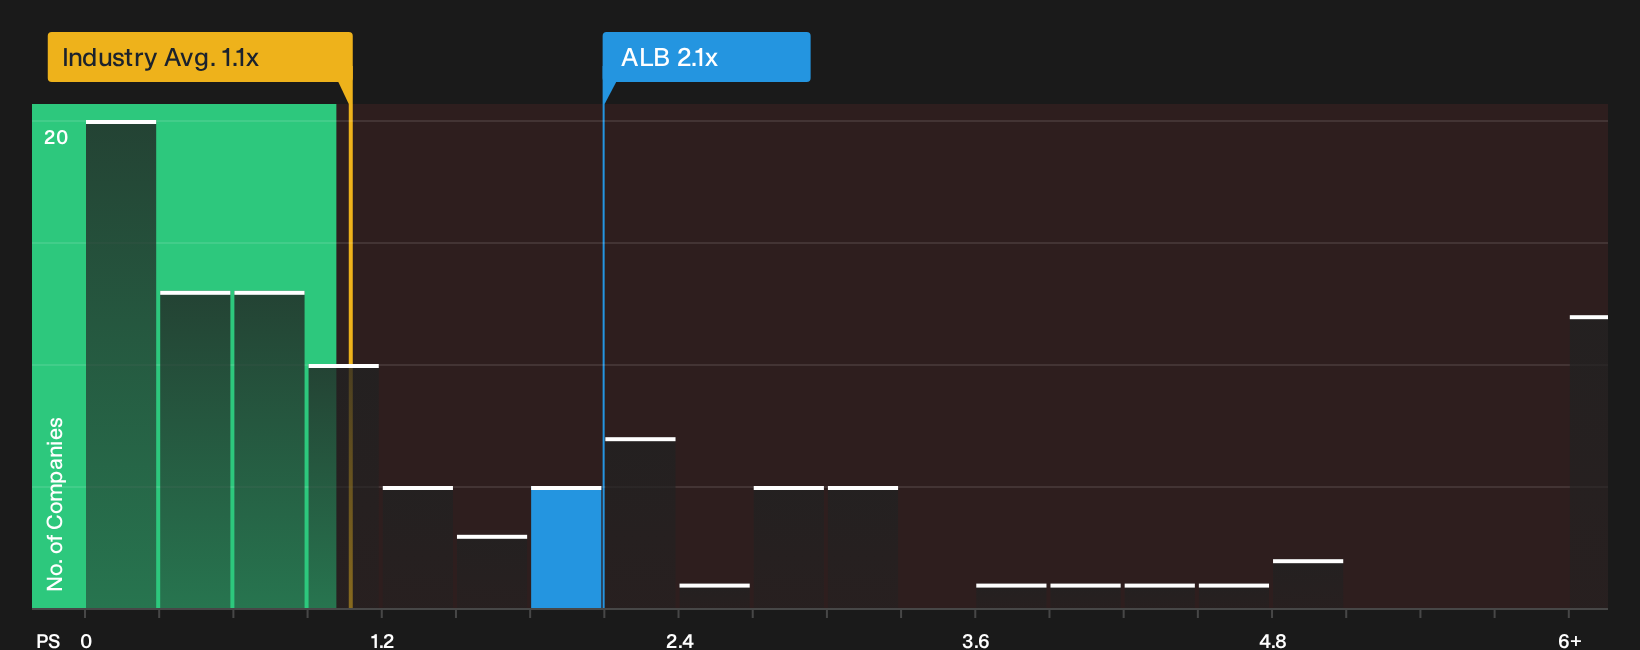
The P/S ratio suits Albemarle because sales are less affected by accounting choices than earnings in a capital heavy chemicals business. On this yardstick, Albemarle trades on a P/S of 2.1x, which is very close to the 2.1x peer average and above the broader chemicals industry at about 1.1x. That mix suggests the stock prices each dollar of revenue in line with more direct rivals, while carrying a richer tag than the wider sector.
The Fair Ratio model, which blends Albemarle specific factors like margins, growth expectations, size and risk, points to a lower multiple than the current 2.1x. That gap means the shares screen as overvalued on this P/S framework, even before you form a view on where lithium volumes or pricing might go next. For a holder or potential buyer, the key question is whether Albemarle's revenue quality or business profile justifies paying more per dollar of sales than the model suggests is typical. Explore the numbers behind Albemarle's P/S valuation.
The Albemarle Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Albemarle valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than it is today. Each narrative turns Albemarle's implied fair value into a clear thesis about the business that you can track over time, and they sit on Simply Wall St's Community page for ongoing discussion.
One of the top community narratives on Albemarle: 39% undervalued
"With ~50% of sales volumes locked under long-term agreements with major Western OEM and battery customers, Albemarle benefits from enhanced revenue stability…"
Discover why this Narrative puts Albemarle at 39% undervalued.
One last Albemarle check before you stop at the share price
Before you decide how Albemarle fits into your watchlist, it is worth asking who is steering the business and how their rewards line up with your interests. See who runs Albemarle and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com