
Is Smart Factory Launch Altering The Investment Case For Belden (BDC)?
- Belden recently launched the Belden and Edge2Web Smart Factory Insights solution, powered by AWS IoT SiteWise, and moved select RUCKUS ICX Ethernet switch production into its Pune, India plant to support digital manufacturing visibility and local hardware output.
- The pairing of no-code industrial analytics with expanded RUCKUS manufacturing inside Belden highlights a push to tighten execution on both software driven insights and physical network infrastructure delivery.
- We will now look at how Belden's Smart Factory Insights push could influence the existing investment narrative centered on digital transformation.
Scan how Belden's push into smart factories compares with other industrial players by running your own filters over 40 power grid technology and infrastructure stocks in the same automation and infrastructure sweet spot.
Belden Investment Narrative Recap
Belden’s story still hinges on investors believing in a shift from basic connectivity hardware toward higher value digital infrastructure and software style solutions. The Smart Factory Insights launch fits directly into that idea by tying together plant floor data, KPIs and decision support. The key near term swing factor remains how quickly this solutions mix grows relative to the heavier OpEx needed to support it.
The main operational risk right now sits in execution. Integrating software, GenAI features and acquired capabilities while managing a high debt load could strain margins if orders slow or customers delay projects. The recent news does not radically change that risk reward balance, but it does push Belden a little further along its digital roadmap.
The RUCKUS ICX manufacturing move in Pune looks most relevant for you because it touches the same digital transformation theme as Smart Factory Insights. Belden is trying to line up software driven plant analytics with the physical networking hardware those plants require. That pairing connects to the thesis of growing solutions style revenue and stickier customer relationships.
Operationally, the India initiative can affect supply chain resilience, local delivery times and cost structure, which all feed into how attractive Belden looks on execution versus peers. It also introduces fresh integration risk across factories, R&D hubs and commercial teams. For investors focused on catalysts, it is another proof point to track as Belden leans into converged IT and OT projects and broader connectivity rollouts.
Belden's current analyst script points to revenues of $3.3b and earnings of $370.1 million by 2029, based on an assumed 5.9% yearly revenue growth rate and an earnings increase of about $133.5 million from $236.6 million today.
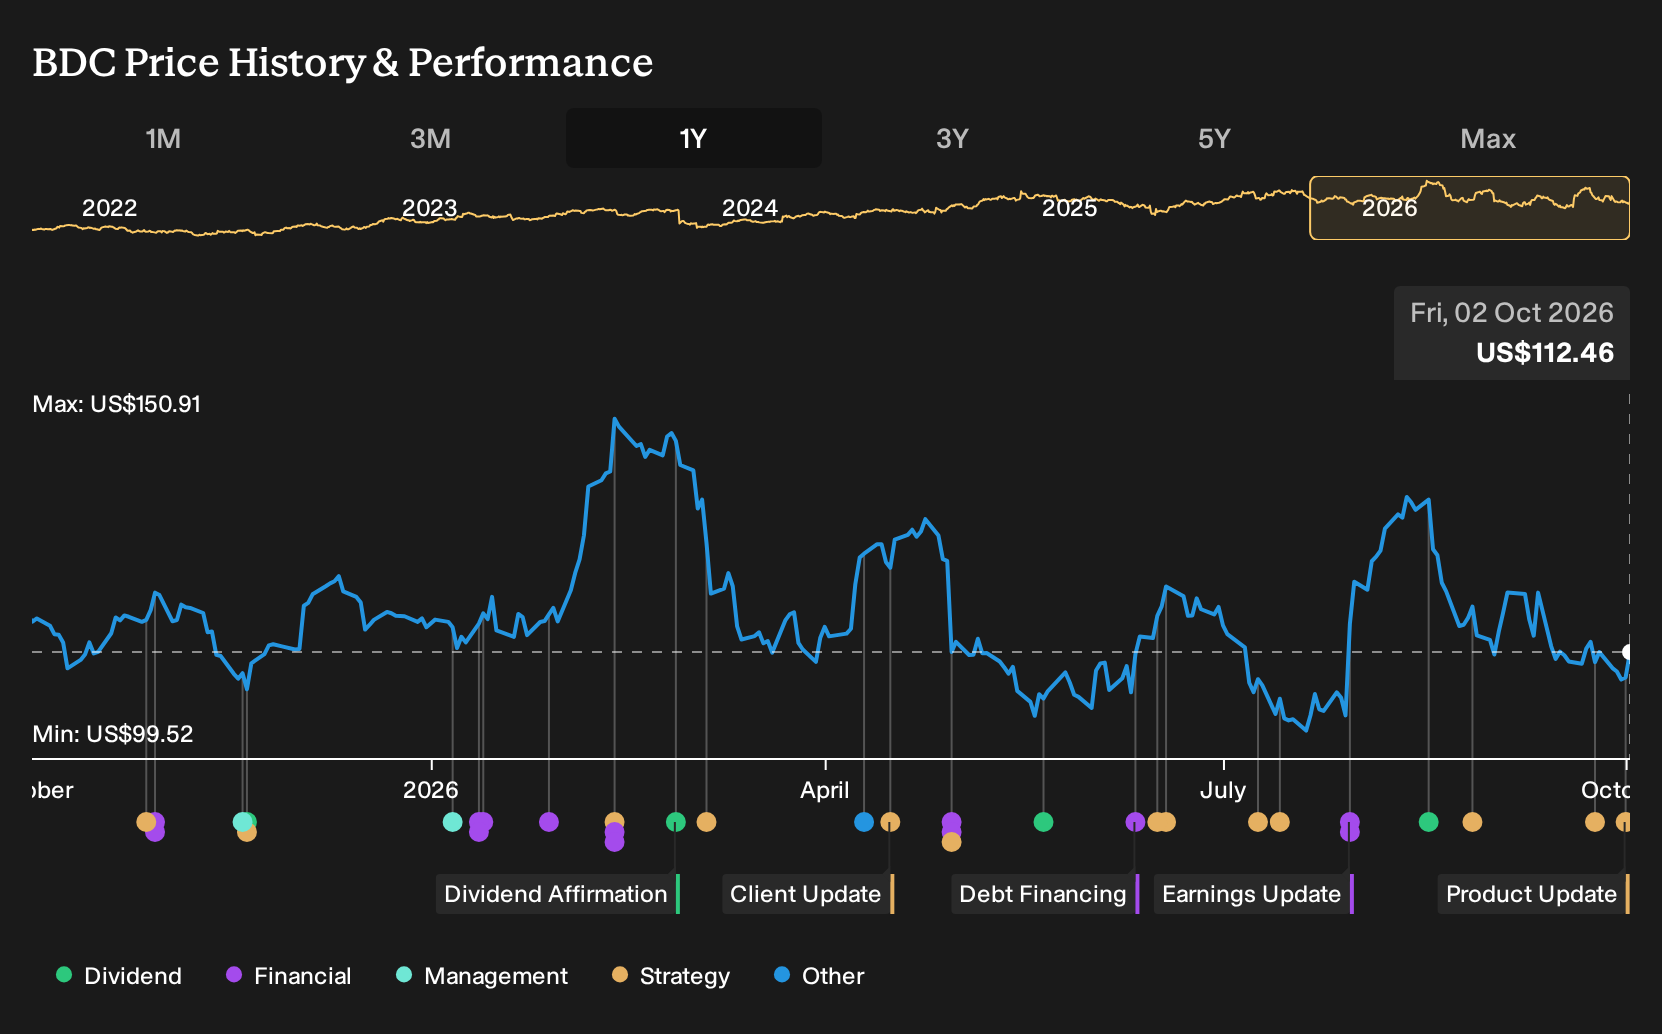
Uncover why Belden's fair value indicates a 35% potential upside to its current price, which could narrow quickly as Belden's digital shift plays out.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community stretch from US$152 up to about US$342.53, which shows how far apart retail assumptions on Belden can land. Before the Smart Factory and RUCKUS news, some users already priced in strong integration and IT OT convergence, while others flagged execution and margin pressure. You should expect opinion gaps and use those community views as a starting point to test your own scenario work.
Explore another Belden fair value estimate, including one that suggests as much as 205% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Belden research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Belden. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Belden's overall financial health at a glance.
Looking For More Investment Ideas Beyond Belden?
If Belden's smart factory push has you thinking more broadly about where to deploy capital next, a wider sweep across other businesses can sharpen your opportunity set. The Simply Wall St Screener lets you filter for the traits that matter most to you, whether that is value, resilience, income or early stage potential.
- Hunting for early stage potential with stronger balance sheets than you might expect for this corner of the market, you can sift through 9 elite penny stocks with strong financials to see which ones fit your risk tolerance.
- If resilience and lower risk scores are higher on your checklist, narrow your watchlist to companies in the 31 resilient stocks with low risk scores and focus on those that match your comfort level.
- For investors who want staying power and solid fundamentals at the same time, start with a list of solid balance sheet and fundamentals (26 results) and see which businesses deserve a deeper look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com