
Does Euro Commercial Paper Plan Change The Bull Case For A2A Stock (BIT:A2A)?
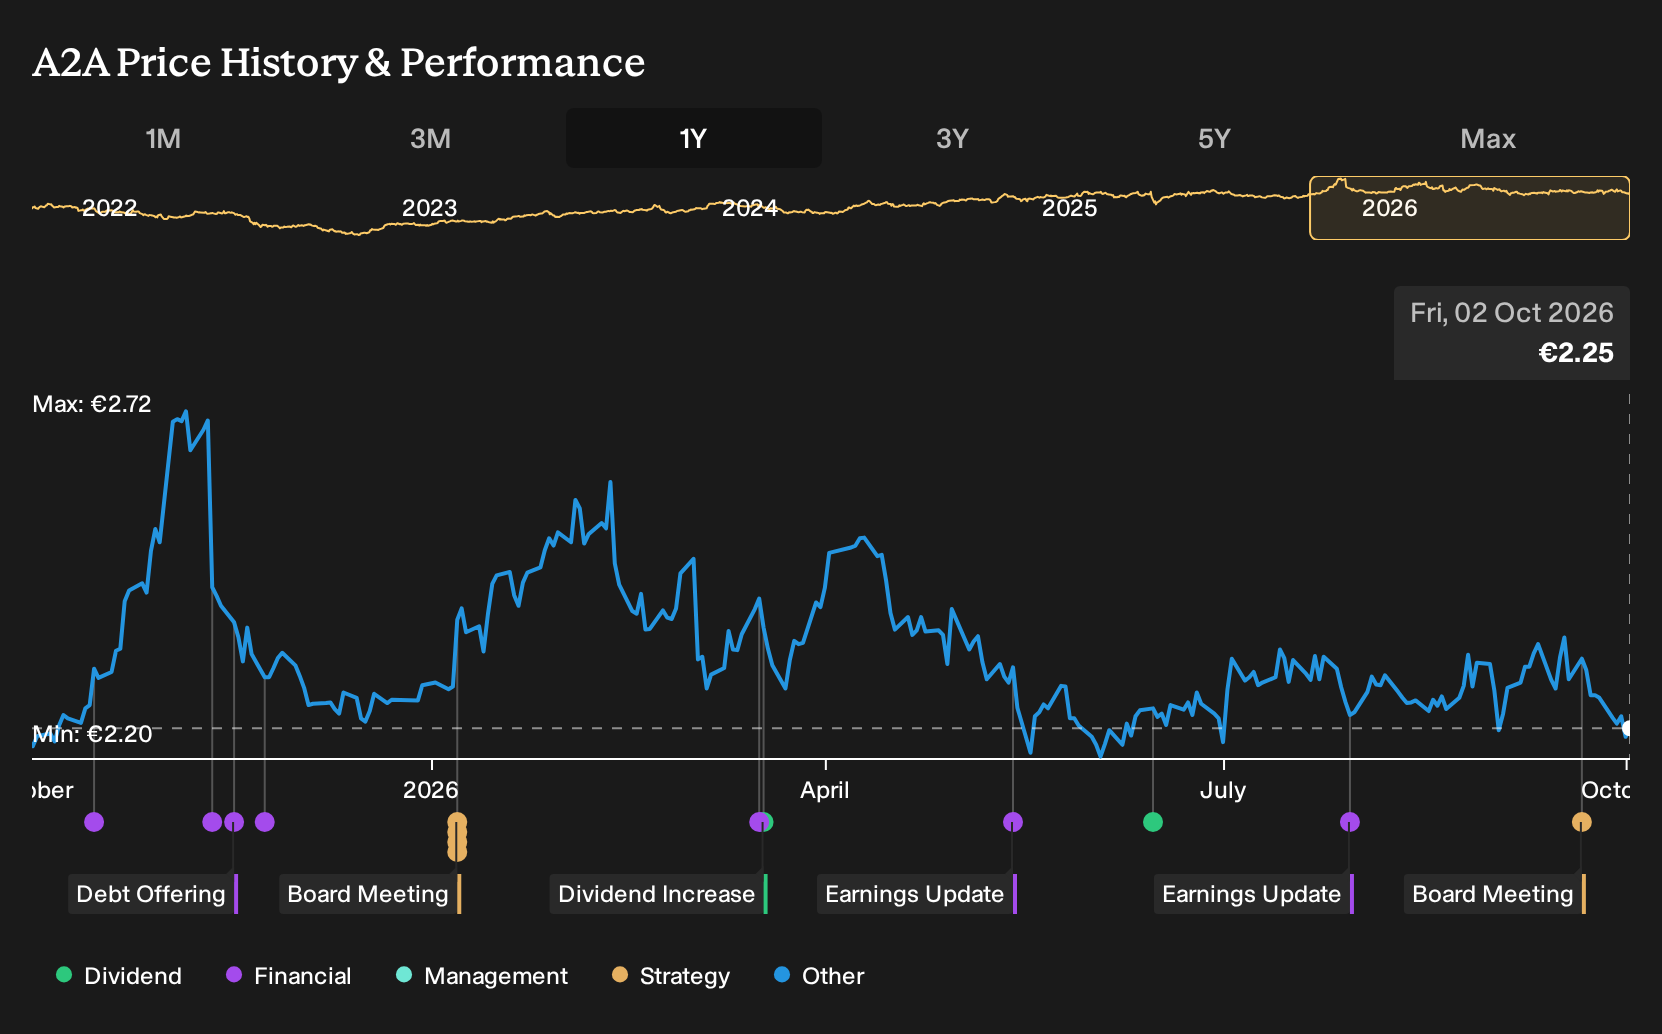
- A2A S.p.A. held a board meeting on 30 September 2026 to review the creation of a euro commercial paper programme of up to €1,500,000,000 and potential future issuance of unsubordinated, unsecured, non convertible notes under that framework until 30 April 2029.
- The planned euro commercial paper programme signals a focus on diversified short term funding that could affect A2A's cost of capital, liquidity profile, and capacity to support grid, circular economy, and digital infrastructure projects.
- This article examines how A2A's investment narrative is influenced by the proposed €1,500,000,000 euro commercial paper programme and related funding plans.
A2A Investment Narrative Recap
To hold A2A stock, you need to believe that heavy investment in grids, circular economy assets, and digital infrastructure can still create value even if headline revenue stays broadly flat and earnings grow slowly. The euro commercial paper plan mainly affects how that spending is funded rather than the fundamentals of electricity, heat, and waste operations.
The main near term swing factor remains execution on large CapEx without eroding already pressured net margins. The biggest risk is that higher debt and funding costs, combined with unresolved regulatory items around concessions and district heating, squeeze free cash flow and make it harder to support both investments and the dividend.
The board meeting around the €1,500,000,000 euro commercial paper programme directly links to A2A’s dependence on external borrowing. This is a utility with a high level of debt and customer deposits are not a funding cushion, so the structure and pricing of any short term issuance matter for interest costs and refinancing flexibility.
Access to that kind of short dated funding could help smooth the timing of grid, waste, and digital projects that analysts already see as central catalysts for the story. The flip side is that more short term paper, if not matched by disciplined CapEx and stable regulation, can amplify sensitivity to rate moves and any future tightening in capital markets.
A2A's narrative projects €14.4b revenue and €687.8 million earnings by 2029. This aligns with analyst assumptions of fairly flat yearly revenue and requires an earnings decline of about €24.2 million from €712.0 million today.
Uncover why A2A's fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster in a tight €2.17 to €2.88 range, yet they still reflect very different views on A2A's long run earnings power. Those opinions were formed before the €1,500,000,000 funding proposal. Revisit these community assumptions and weigh them against regulatory risk and heavy CapEx dependence.
Explore 2 other A2A fair value estimates, including one that suggests it could be worth just €2.17.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your A2A research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for A2A. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A2A's overall financial health at a glance.
Looking for more investment ideas beyond A2A?
If this funding story has prompted a fresh look at A2A, it can be useful to line it up against other stocks with different balance sheet profiles, income profiles, and upside potential using the Simply Wall St Screener.
- For potential mispriced opportunities backed by stronger fundamentals, run a search through our 196 high quality undervalued stocks and see which companies fit your criteria.
- If reliability and downside protection matter most to you, focus on businesses with steadier risk profiles by scanning our 228 resilient stocks with low risk scores.
- When you want growth potential without giving up financial strength, broaden your watchlist with our 616 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com