
What Does Apple (AAPL) Restructuring And Layoffs Mean For Its Product Roadmap?
- Apple (NasdaqGS:AAPL) CEO John Ternus announced a corporate restructuring that includes layoffs to address rising chip costs.
- The overhaul shifts Apple away from its long standing fixed product launch calendar toward a more flexible release schedule.
- Hardware and silicon engineering teams are being reorganized to focus on fewer core platforms and new chip design priorities.
- The restructuring and layoffs to tackle chip cost pressures and product timing shifts need weighing against the rest of our work. Our analysis turns up 2 other big wins for Apple as well.
Resets like this at Apple often echo across the broader hardware and semiconductor supply chain, so the wider AI build out trend is worth tracking through 90 AI infrastructure stocks.
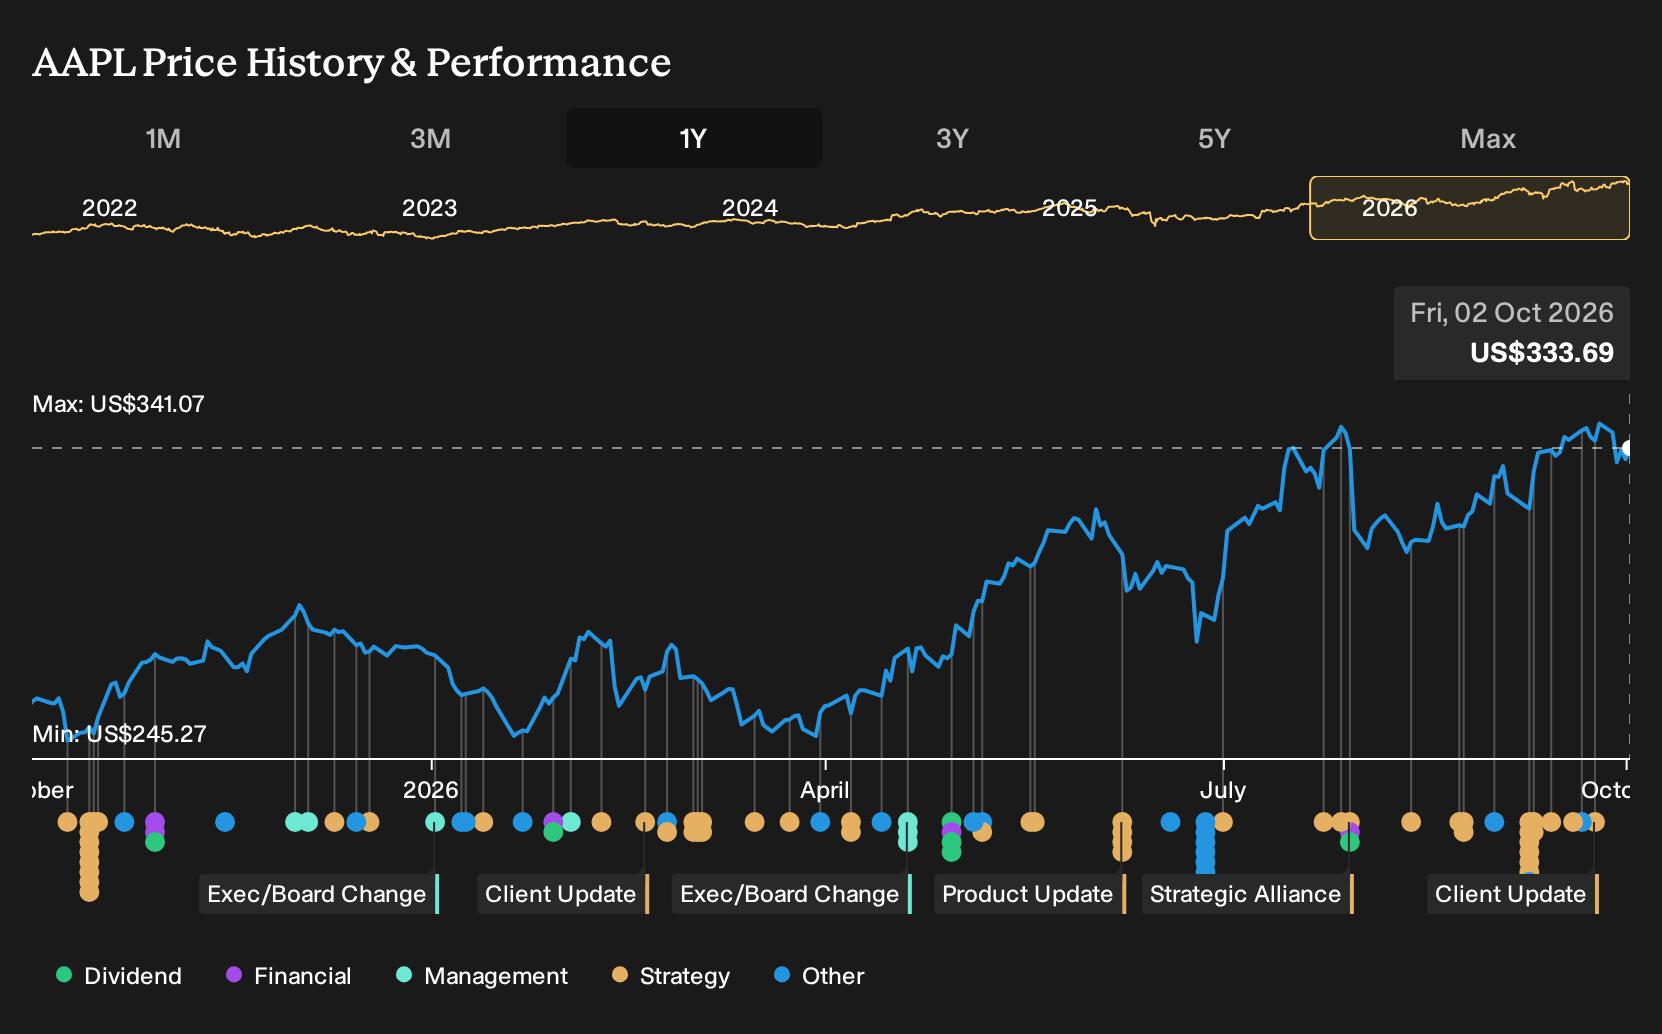
Apple, a US tech heavyweight with a reported market cap of about $4.8 trillion, earns its clout by designing and selling iPhones, Macs, iPads, wearables, and accessories worldwide. This gives this restructuring move direct implications for how its core hardware and chip priorities line up in the years ahead.
Apple leadership reset puts AI and cost Narrative to the test
Apple’s investment story assumes management can lean on proprietary silicon and AI-powered devices while keeping costs in check and margins resilient. John Ternus’ restructuring call goes straight to that Narrative, because it rewires who runs the hardware roadmap and how aggressively the group tackles rising memory and chip expenses.
"AI-powered features, enhanced wearables, and supply chain optimization support future product differentiation, new revenue streams, and improved cost management...
See how the full story points towards a $326 fair value for Apple.
The restructuring marginally strengthens the Apple thesis where it leans on supply-chain optimization and cost control. A leaner hardware and silicon org that focuses on fewer core platforms is directly aligned with the Narrative’s bet on proprietary chips and Apple Intelligence as the main way to keep device pricing power against Samsung and Google.
The pressure point is execution risk around that same bet. Cutting layers of management and shifting the long used launch cadence makes it harder to judge whether Apple can keep translating AI-heavy products into stable margins while regulatory, legal, and supply-chain risks flagged by analysts are still unresolved.
For you as an investor, a move like this only becomes useful once it is mapped back to a clear Narrative about what Apple is trying to achieve with AI, hardware, and costs over the long haul.
One big Apple question this article has not touched
Short term headlines grab attention, but the real crux for Apple is where analyst models think earnings and cash flows land a few years from now, and how that lines up with today’s pricing. See where analysts expect Apple to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com