
Is Coca Cola Consolidated (COKE) Pricey Following The Ohio Strike Shutdown?
Labor unrest at Coca-Cola Consolidated (COKE) has escalated after Teamsters extended an unfair labor practice strike, with more than 300 workers effectively shutting down Ohio operations and putting labor risk directly on investors’ radar.
Against this backdrop, Coca-Cola Consolidated’s share price closed at US$192.04, with a 1-day share price return of 2.63% and a year to date share price return of 28.16%. The 1-year total shareholder return of 60.18% points to strong longer term momentum despite some recent weakness over the past quarter.
Scan beyond Coca-Cola Consolidated and see how other consumer-facing businesses handle operational shocks by reviewing our hand picked 31 resilient stocks with low risk scores with relatively resilient profiles.
Coca-Cola Consolidated has delivered strong shareholder returns even as labor disputes raise fresh questions about operational risk. After this latest move in the share price, is the business quality already fully reflected in the valuation, or not yet?
Preferred P/E of 23.2x for Coca-Cola Consolidated: Is it justified?
Coca-Cola Consolidated trades on a P/E of 23.2x, which prices the latest $192.04 close as richer than the wider beverage sector but cheaper than its closest peer group.
The P/E ratio compares the current share price to earnings per share. For a bottler with $549.961m in net income and a long operating history across US$7.7b of revenue, it is a quick way to see how heavily the market is weighing current profits versus alternatives in the same industry.
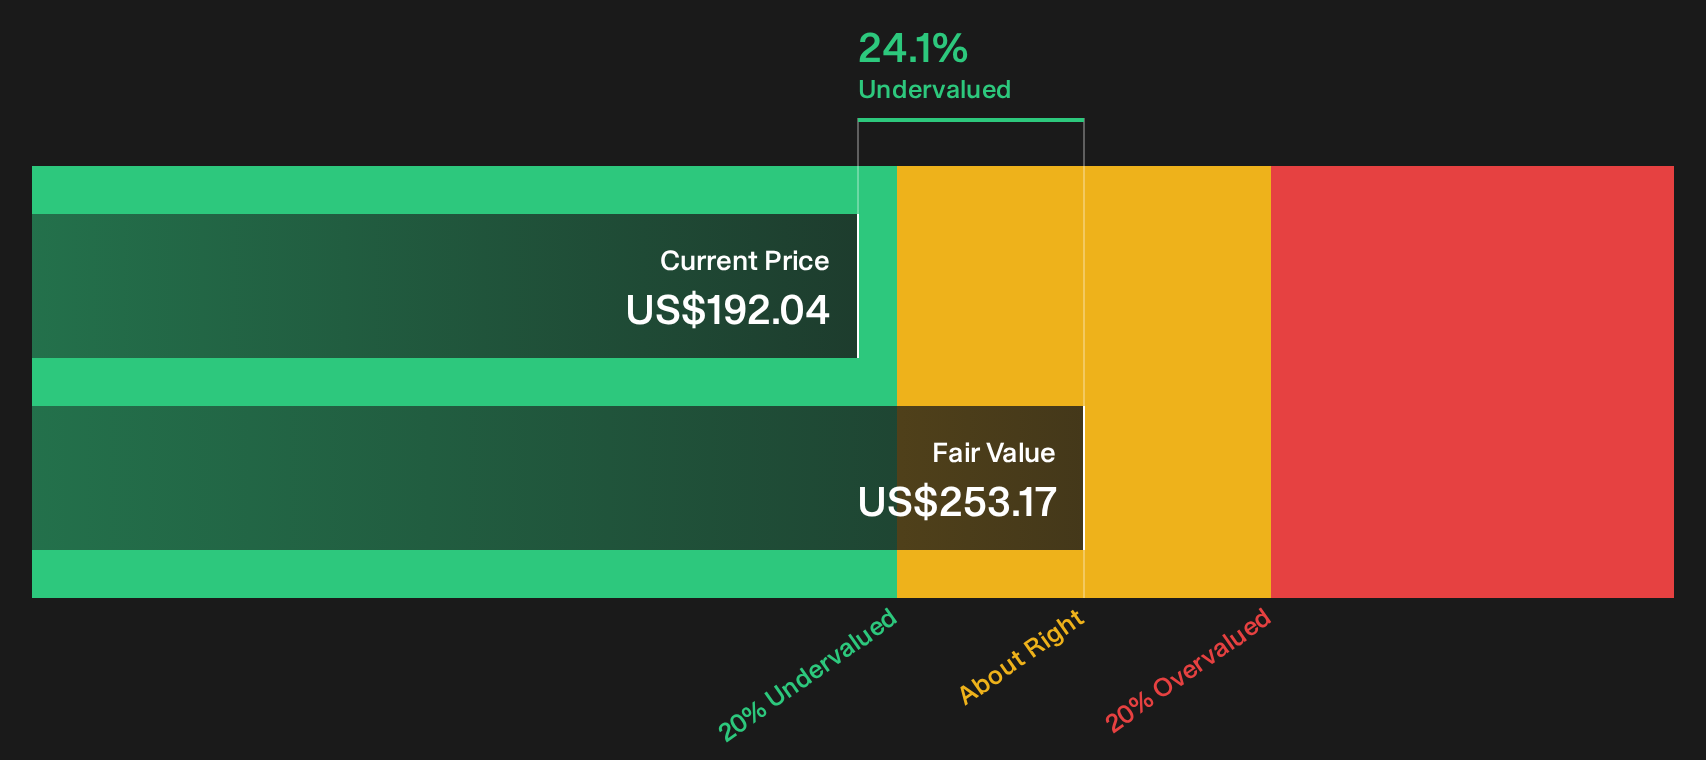
With high quality earnings flagged, 5 year earnings growth running at 19% per year, and a recent year where earnings declined 6.4% and margins slipped from 8.4% to 7.2%, that 23.2x multiple signals investors are paying up for a mixed profit record. The stock also screens as 24.1% below an internal fair value estimate based on future cash flows. This points to the possibility that the market price could be lagging some of the cash generation implied by the SWS DCF model.
Relative to the Global Beverage industry average P/E of 16.5x, the Coca-Cola Consolidated valuation is clearly richer. This suggests the market is assigning a premium to its profile. Compared with a 53.6x peer average, the same multiple looks restrained, implying investors in this stock are not paying the kind of prices seen for some higher rated bottlers and beverage groups.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 23.2x (ABOUT RIGHT)
Still, prolonged labor disputes or any hit to volumes across Coca-Cola Consolidated’s US$7.7b footprint could quickly challenge the current P/E premium that investors are paying.
Find out about the key risks to this Coca-Cola Consolidated narrative.
Another view on Coca-Cola Consolidated’s value
That 23.2x P/E paints Coca-Cola Consolidated as pricier than the 16.5x Global Beverage average, yet far cheaper than the 53.6x peer group. Investors are effectively paying a mid-range valuation for a business that the market has rewarded strongly over the past year.
Our DCF model points in a different direction, with an estimated future cash flow value of $253.17 per share versus the current $192.04 price. This implies that Coca-Cola Consolidated trades at a 24.1% discount and raises a simple question for holders and onlookers alike: is the market underpricing those cash flows, or is the model too generous?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Coca-Cola Consolidated for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Coca-Cola Consolidated and its valuation story do not need to leave you on the sidelines. Move fast, review the underlying data, and shape your own take using the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Coca-Cola Consolidated?
If Coca-Cola Consolidated has you rethinking where risk and value intersect, use this moment to widen your watchlist and pressure test your assumptions.
- Target robust fundamentals first by scanning a list of solid balance sheet and fundamentals (26 results) that can handle shocks without forcing you into stressful decisions.
- Hunt for mispriced quality and let the 31 high quality undervalued stocks surface candidates where strong finances meet prices that may not fully reflect them yet.
- Prioritise cash returns to shareholders by reviewing a focused 7 dividend fortresses that filters for income streams with higher yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com