
3 US Bank Stocks Built For Higher Short Term Yields
Investors are yanking cash out of mortgage-backed ETFs, Treasury yields sit above 5.3%, and cash suddenly feels less like dead weight and more like a profit center. That shift in mindset can reward businesses built around institutional cash management and short-term yield, while leaving others exposed to higher funding costs and jumpier clients. This piece unpacks the set up and profiles three U.S. stocks that are directly in the crosshairs of this rate driven story.
The three stocks below are a small sample of this cash rich corner of the market, while the full screen on Simply Wall St surfaced 28 more U.S. institutional cash management and short term yield platforms with equally compelling narratives that are not covered here. To go straight to the full set of ideas, analyze the risk and return trade offs, and identify your own highest conviction targets, head into the U.S. Institutional Cash-Management and Short-Term Yield Platforms screener.
USCB Financial Holdings (USCB)
Overview: USCB Financial Holdings is a Florida based bank holding company focused on business banking, deposit rich cash management services, and related lending.
Operations: USCB Financial Holdings generates about $94 million of banking revenue entirely from U.S. clients, reflecting a concentrated domestic franchise.
Market Cap: $408 million
USCB Financial Holdings plugs directly into the cash-management theme through business focused deposits, treasury services, and short term liquidity products, which makes its Florida growth story especially relevant for investors watching higher short term yields.
"The sustained population influx and robust economic growth in Florida and South Florida, combined with the bank's focus on commercial real estate and business banking in these high-growth markets, are likely to fuel further loan demand and deposit growth, leading to higher revenue and asset expansion over the coming years."
What happens to those expanding margins and deposit flows if a single key assumption about short term rate support eventually breaks?
If that rate support eventually cracks, read the full narrative for USCB Financial Holdings to see how USCB Financial Holdings could still turn deposit sensitivity into an accelerating opportunity.

Norwood Financial (NWFL)
Overview: Norwood Financial is a community bank that gathers local deposits and redeploys that cash into loans, wealth services, and short-term cash-management tools.
Operations: Norwood Financial generates about $100 million in banking and related financial services income, all from customers across the United States.
Market Cap: $360 million
Norwood Financial fits this cash-management theme as a community lender whose retail, municipal, and business clients often move balances toward shorter-term vehicles when longer bonds look shaky.
"Ongoing repricing of the loan portfolio at higher yields, combined with the 2024 securities repositioning, should continue to push net interest margin toward management’s target and support earnings expansion."
What really matters next is how one less visible funding pressure ultimately shapes the balance between richer loan yields and the cost of holding that cash.
That quiet funding squeeze is the real story, and the full narrative for Norwood Financial shows how Norwood Financial could turn repricing into an accelerating advantage.

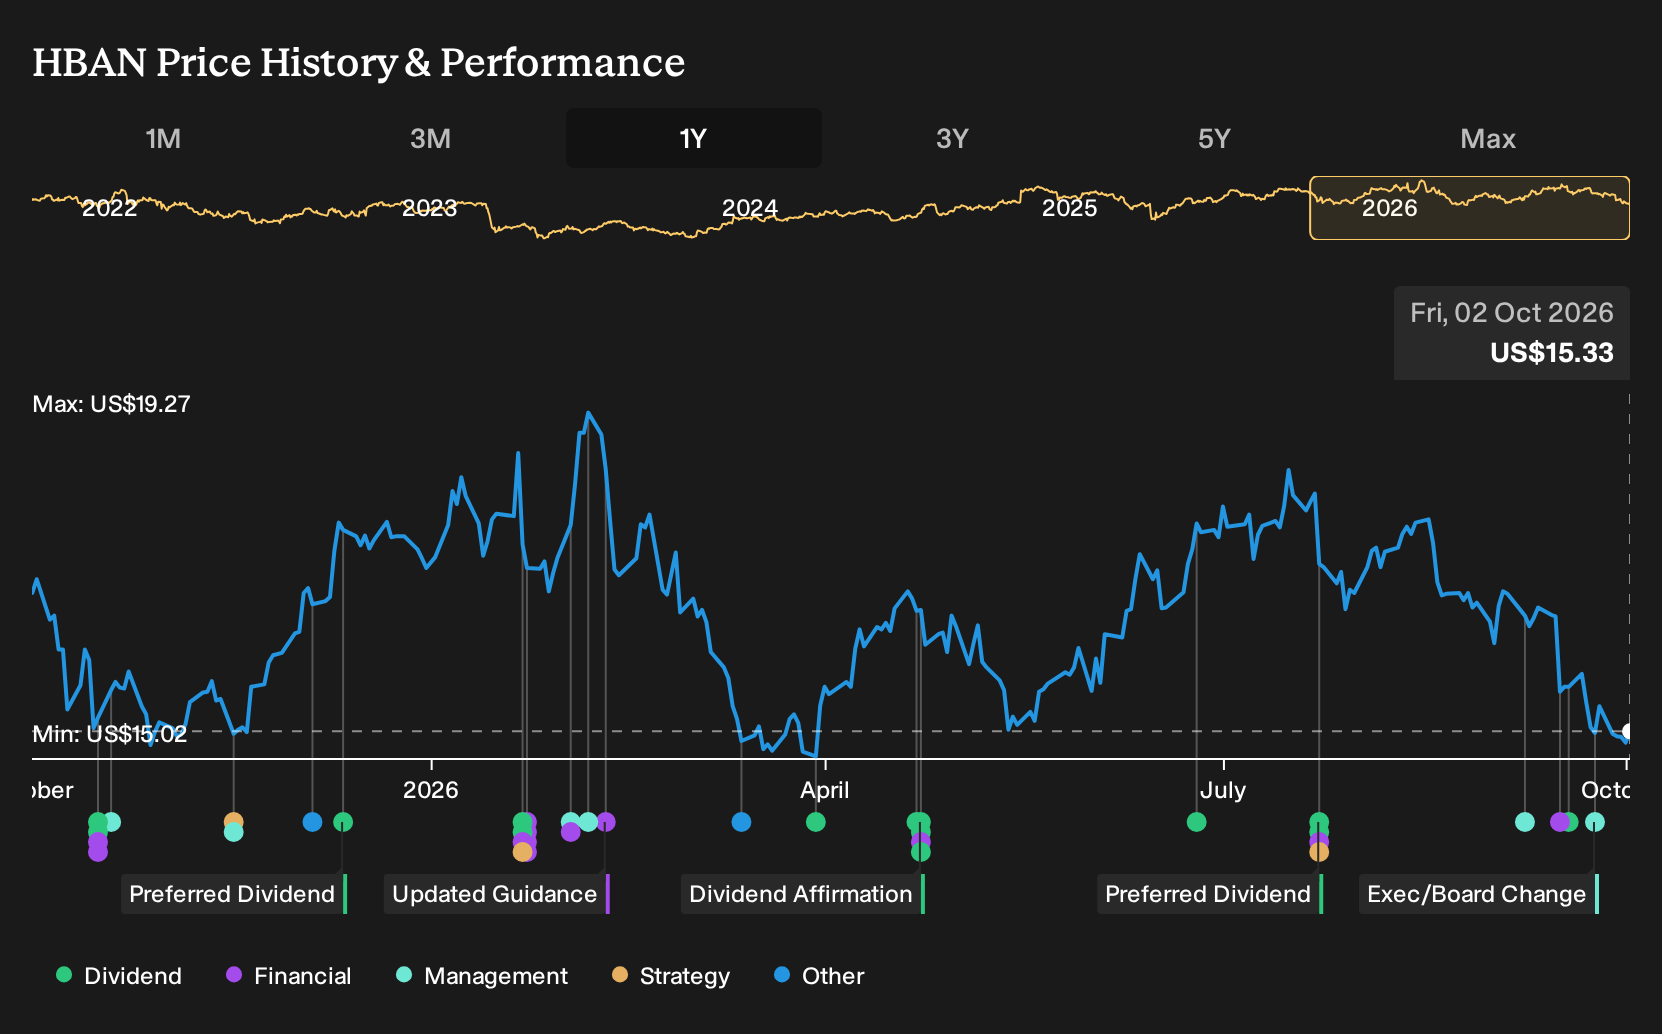
Huntington Bancshares (HBAN)
Overview: Huntington Bancshares is a large U.S. bank that blends commercial and corporate banking with deposit heavy cash-management and short-duration services.
Operations: Huntington Bancshares generates about US$9.2b of revenue, with roughly US$3.2b from Commercial Banking and US$6.3b from Consumer & Regional Banking, all in the U.S.
Market Cap: US$30.7b
For investors focused on institutional cash-management, Huntington Bancshares matters because commercial clients often treat it as both their transaction hub and short-term yield engine when rates move quickly.
"The expansion into Texas through the Veritex acquisition, together with the Cadence partnership and build-out in the Carolinas, is widening Huntington Bancshares’ footprint in higher population growth markets and is supported by sequential loan and deposit growth, which can underpin future revenue and earnings."
What really decides how much of that potential shows up in margins and fee income is how one quiet funding pressure ultimately resolves.
That funding pressure is the hinge, and the full narrative for Huntington Bancshares shows how Huntington Bancshares could see that stress decouple from earnings and fee momentum.
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Once momentum builds, prices can be flying before most investors even notice. Scan these curated shortlists while it matters and get in early.
- Hunt for potential breakout yield stories by scanning a curated 7 dividend fortresses that aim to keep income flowing while share prices are still under the radar for now.
- Spot early momentum across future-facing automation by running through a hand picked set of 90 robotics and automation stocks before capital floods in and reprices the whole group.
- Track where infrastructure spending could be building next by reviewing a focused pool of 40 power grid technology and infrastructure stocks while valuations still reflect old assumptions, not fresh demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com