
IonQ (IONQ) Stock Looks Hard To Call Despite Fresh Superion News
IonQ has ridden a powerful five year run in its share price while also staying in the headlines with new quantum hardware plans and partnerships, which raises a simple question for you as an investor: Does the current market value still line up with what IonQ’s balance sheet and book value can reasonably support?
- Over the past 5 years the stock has delivered a gain of about 420%, which puts a lot of long term optimism on the line when you compare that market enthusiasm with the company’s underlying net assets.
- Recent agreements around the Superion 256 quantum computer, including deployments with NVIDIA and academic and regional partners, can shape how fast IonQ turns its technology roadmap into revenue and capital requirements, both of which feed directly into how much weight investors place on book value today.
- Your read on IonQ is one view; the desks covering it have another. See what analysts think IonQ's shares could be worth.
The issue now is whether IonQ’s current share price is adequately supported by its book value when set against the industry average.
If you want to pressure test IonQ’s book value story against other quantum names as well, a curated list of 25 quantum computing stocks is available for further comparison.
Does IonQ Look Fairly Valued on Book Value?
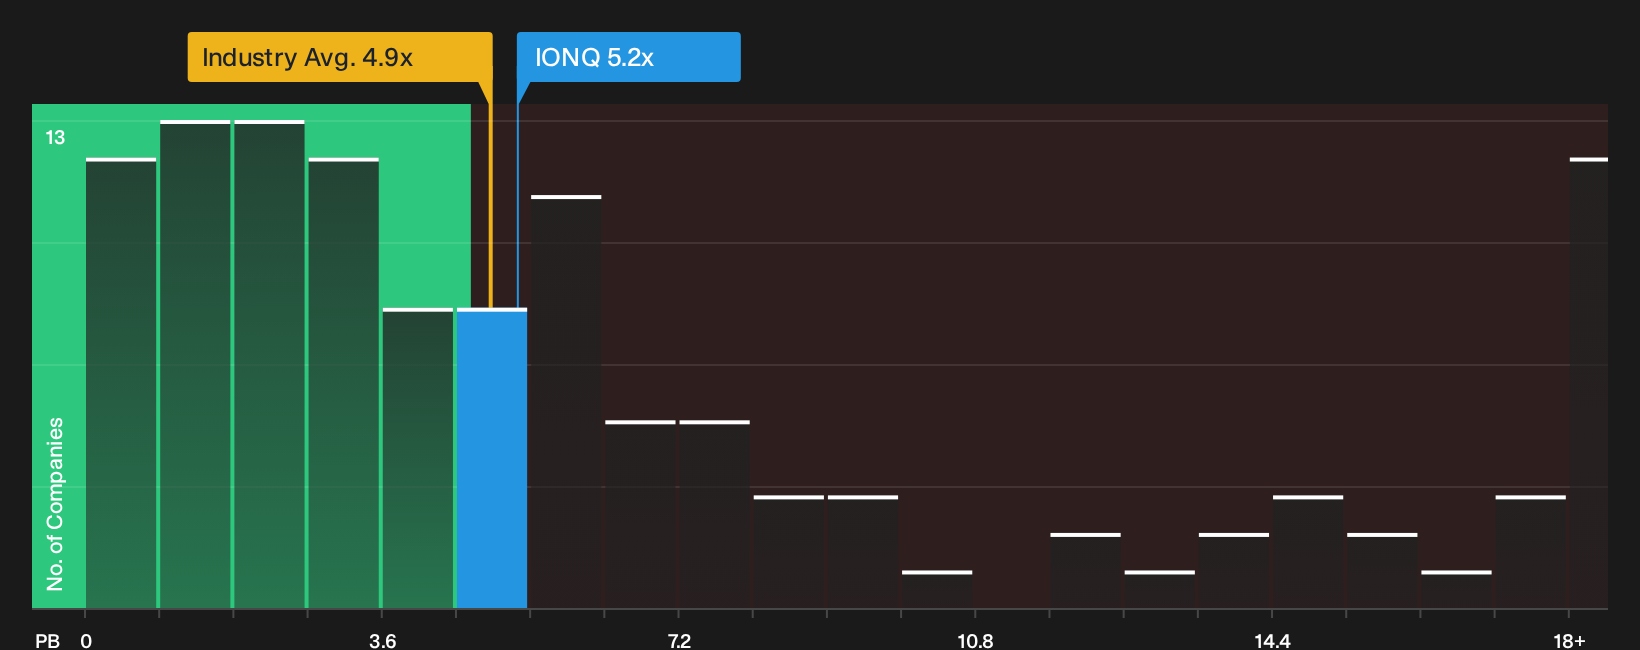
Price to book suits IonQ because investors are still weighing a balance sheet heavy on intellectual property and future projects rather than mature earnings power. On that measure, IonQ trades around 5.2x P/B, which is only modestly above the semiconductor group on roughly 4.9x. That places the quantum specialist close enough to the sector yardstick that the ratio alone does not indicate either a clear bargain or a clear bubble.
Compared with a peer average nearer 13.4x, the stock looks much less aggressively priced on this book value lens, even after the excitement around the Superion 256 partnerships with NVIDIA and academic buyers. For you as a shareholder, that leaves P/B sending a fairly balanced signal, where the premium to the wider industry is limited but the gap to more expensive peers serves as a reminder that the market is already assigning meaningful value to IonQ’s quantum roadmap. Explore the numbers behind IonQ's P/B valuation.
The IonQ Narrative: What Would Justify Today's Price?
IonQ’s story now turns from the P/B ratio to the assumptions sitting underneath it. Narratives on Simply Wall St’s Community page connect that valuation puzzle to the future that would need to unfold on growth, margins and earnings for the share price to end up meaningfully higher or lower than today. Where a single multiple or model gives one neat figure, these outlines spell out the future that figure leans on so you can watch in real time whether it stays on track or drifts off course.
IonQ splits opinion sharply, with community bulls and bears reading the same quantum roadmap in very different ways.
Bull case: 49% undervalued
"IonQ has systematically de-risked its thesis, and is now fully funded to execute a "winner-take-all" land grab, positioning it as the potential "Nvidia of Quantum"…
Discover why this Narrative puts IonQ at 49% undervalued.
Bear case: 765% overvalued
"At current prices, IonQ trades at well over 100 times revenue, a level rarely sustained even among the fastest growing technology companies…"
Explore why this Narrative puts IonQ at 765% overvalued.
The IonQ share price is only one piece of the decision
Valuation ratios tell you what the market pays today, but the next question is how professional forecasters currently see IonQ a few years from now and whether that picture lines up with your own expectations. Explore where analysts expect IonQ to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com