
Higher Rates Are Reshaping Bank Stocks Like Farmers National Banc and Arrow Financial
Higher for longer is no longer a theory; it is the story the Federal Reserve is telling investors with each rate decision. That story matters if you own banks, insurers or any stock that feels every tweak in borrowing costs and bond yields. This article walks through three US financial stocks from a quality-focused screener that could be meaningfully exposed to this new rate reality and explains why that may help or hurt your portfolio.
The three stocks in focus below are just a starting sample from this theme. The full screen surfaced 12 more US financial companies with equally interesting rate stories and business profiles that are not covered here. To see the broader opportunity set, identify your own front runners, and pressure test each thesis against hard data, head straight into the US Financials – Banks and Insurance Benefiting from Higher-for-Longer Rates screener.
Farmers National Banc (FMNB)
Farmers National Banc is a regional financial group rooted in Ohio that combines traditional banking with trust, retirement consulting, insurance and wealth management, a mix that fits the higher for longer rates theme through interest sensitive lending and invested assets. The bank segment generates about US$161.9 million of revenue, with a further US$15.9 million from trust and retirement services, supporting a market cap of roughly US$898 million.
For a higher for longer Fed path, Farmers National Banc offers rising net interest income, solid profitability and a 4.43% dividend yield, all screened for quality, stability and moderate risk. The opportunity depends on how one pressure point inside that earnings engine behaves if rates stay elevated longer than investors expect.
That pressure point is exactly what sits at the heart of the 4 key rewards and 1 important major warning sign, which can help you see what might accelerate or stall Farmers National Banc next.

Arrow Financial (AROW)
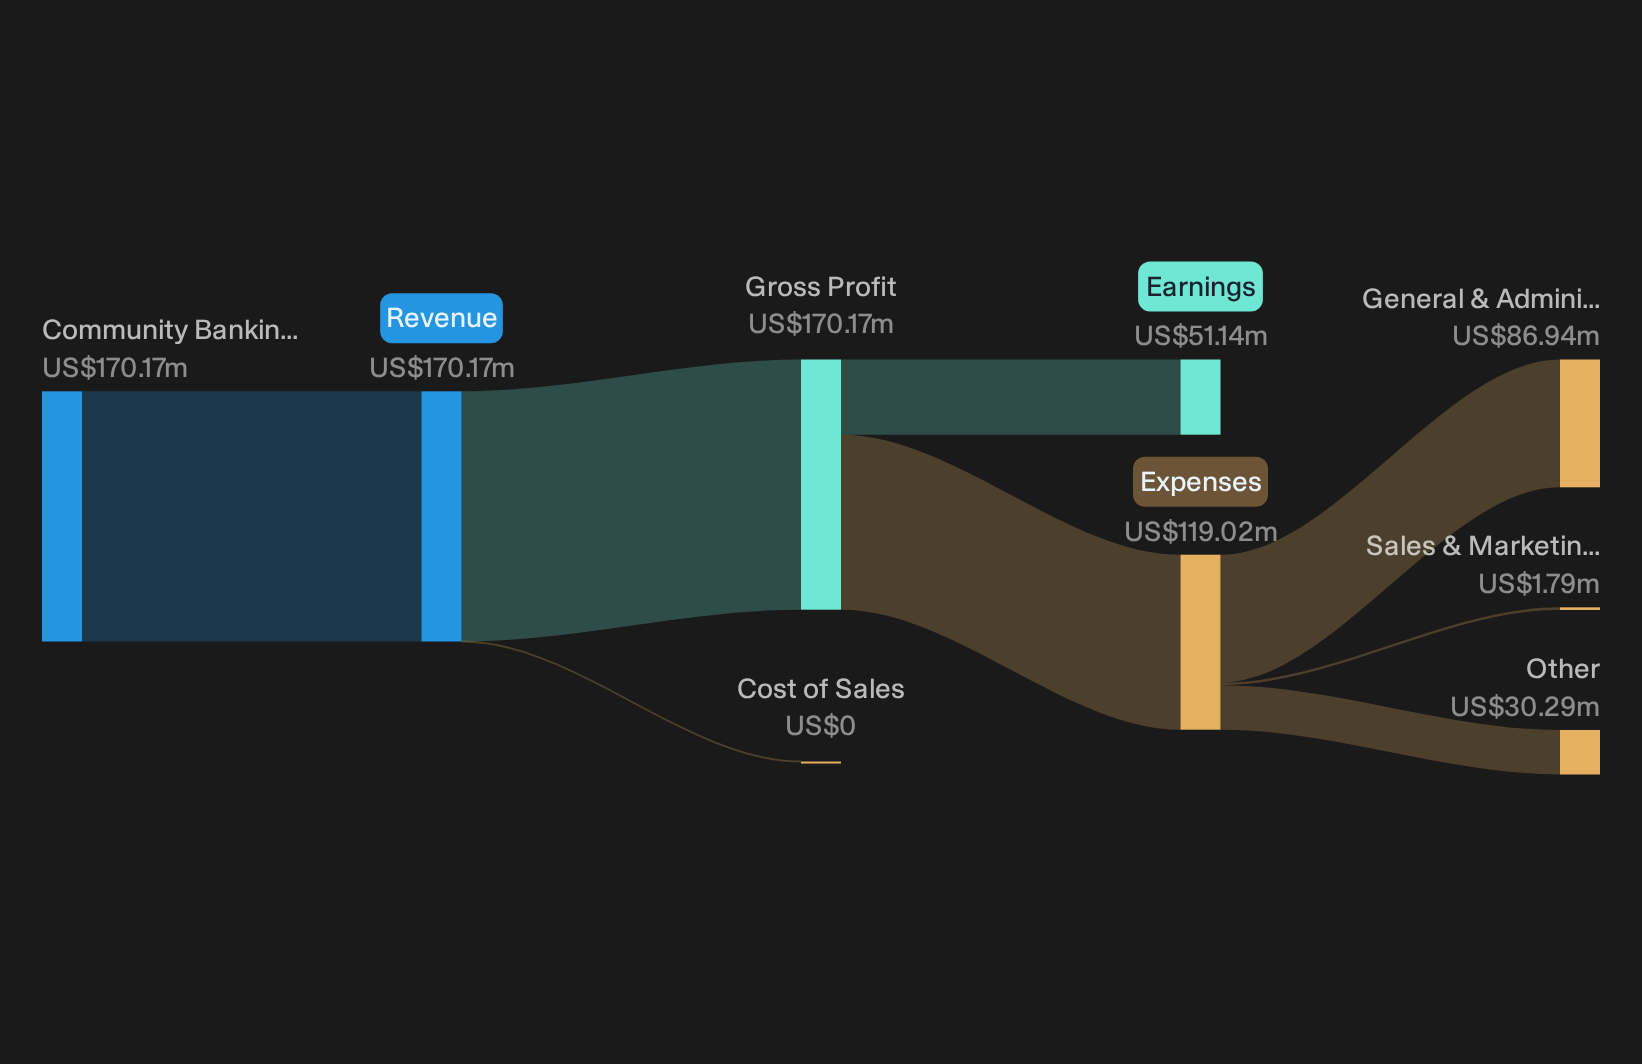
Arrow Financial is a Glens Falls based bank holding company focused on commercial and consumer lending, deposit products, and related financial services that tie directly into the higher for longer rates theme through interest driven income. It generates about US$170 million from community banking and has a market cap near US$690 million.
Arrow Financial lines up cleanly with the screener idea, because most of its US$170 million community banking revenue comes from interest earning loans and deposits that are directly linked to short term rates. Net interest income of US$35.93 million in Q2 2026 and a 3.18% dividend yield illustrate the connection between policy rates and investor returns if one quiet pressure inside that margin story shifts direction.
That quiet margin pressure is exactly where the story could surprise you, so tap into the analysis report for Arrow Financial to see whether Arrow Financial’s spread engine is stalling or quietly reloading.
Bank First (BFC)
Bank First is a Wisconsin based lender that lives squarely in the higher for longer rates theme, with earnings closely linked to what it earns on loans versus what it pays on deposits. It generates about US$217 million from banking operations and carries a market cap near US$1.7b.
Bank First ties directly into the higher for longer rates idea because its core business is classic spread lending. It earns the gap between loan yields and deposit costs on about US$217 million of banking revenue in the United States and is supported by a roughly US$1.7b market value. With the Fed turning more hawkish again, that spread engine and a long running dividend story both start to matter a lot more if one quiet source of pressure on those margins shifts direction.
If that margin pressure has your attention, scan the 3 key rewards and 1 important warning sign to see whether Bank First’s spread engine is quietly compounding strengths or masking early cracks.

Curious About Fresh Market Alternatives?
Fresh ideas move first. By the time momentum is obvious, early entry points can be gone or dropping fast. Scan under the radar for now and act now.
- Target steadier paydays by reviewing a curated set of dividend heavyweights screened for resilience in the 7 dividend fortresses before yields get picked over by the crowd.
- Hunt for under followed potential breakouts with strong balance sheets inside a hand filtered 19 high quality undiscovered gems while they are still flying below most radars.
- Position for the next wave of compute demand by checking rigorously filtered 90 AI infrastructure stocks before infrastructure spending momentum gets fully priced in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com