
Is Greenbrier Companies (GBX) Undervalued After Its $600 Million Railcar Order Win?
New railcar orders put Greenbrier’s recent performance in focus
Greenbrier Companies (GBX) just reported fresh demand in its core manufacturing business. The firm received orders for 3,400 railcars worth about US$600 million in its fiscal fourth quarter.
The announcement includes 780 units for Saudi Arabia’s state owned railway, covering tank cars for phosphoric acid and molten sulfur as well as intermodal equipment. This adds a new product line to a relationship that started with a 2015 tank car contract.
Greenbrier Companies’ latest US$600 million order arrives after a weaker run in the shares, with the 90 day share price return down 14.6% and the year to date share price return down 14.2%, while the 3 year total shareholder return is 11.3%. This points to longer term holders seeing a very different experience compared with recent momentum.
Scan beyond Greenbrier Companies and see how other rail and industrial plays are lining up in our curated list of list of solid balance sheet and fundamentals (26 results).
Bulls point to fresh US$600 million orders and steady annual revenue and net income growth, while bears focus on the recent share price slump. Which side does Greenbrier Companies’ current valuation lean toward?
Most Popular Narrative: 9% Undervalued
Greenbrier Companies closed at $40.58 against a widely followed fair value estimate of $44.67, which frames the new railcar orders against a valuation that already assumes only modest progress and tighter margins.
Greenbrier's robust global railcar backlog, valued at $2.6 billion, provides significant revenue visibility and is expected to support steady production rates, positively impacting future revenue streams. Market conditions, such as aging North American fleet and demand growth in Europe and Brazil due to infrastructure investments and policy changes, are likely to boost demand for railcar maintenance and new builds, potentially increasing revenue and operating margins.
See why 3 investors see Greenbrier Companies as 9% undervalued.
Result: Fair Value of $44.67 (UNDERVALUED)
Still, any prolonged slump in new railcar deliveries, or higher steel and financing costs, could squeeze Greenbrier Companies’ margins and challenge the current undervalued narrative.
Find out about the key risks to this Greenbrier Companies narrative.
Another view on Greenbrier Companies’ valuation
While one popular narrative pegs Greenbrier Companies close to a fair value of $44.67, the SWS DCF model lands in a very different place. It values Greenbrier Companies’ future cash flows at just $3.35 per share, which screens as heavily overvalued on that framework. When two yardsticks are this far apart, which one do you trust more for your own decision making?
For readers who want to see exactly how the cash flows are modeled and discounted, Look into how the SWS DCF model arrives at its fair value.
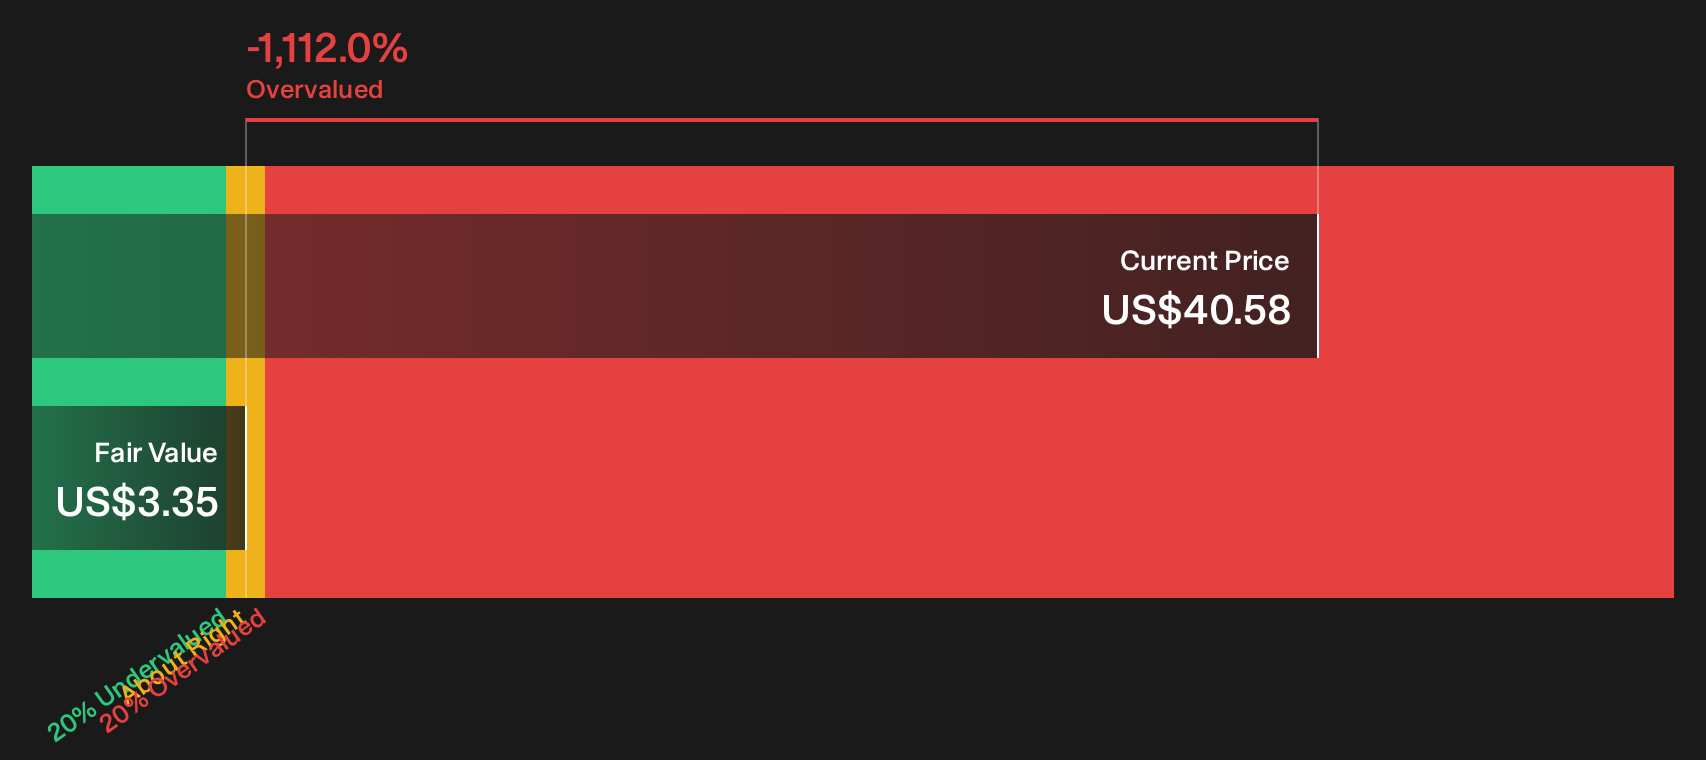
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Greenbrier Companies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between Greenbrier Companies’ risks and rewards after all of this? Do not wait for consensus to form. Scrutinize the numbers, stress test your own thesis, and ground your view in the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Greenbrier Companies?
Do not stop with Greenbrier Companies. Put this news in context by lining it up against other opportunities and let clearer choices emerge from the comparison.
- Target dependable income streams by focusing on businesses that feature 7 dividend fortresses built on established payout profiles and resilient cash generation.
- Hunt for mispriced quality by scanning 31 high quality undervalued stocks that pair solid fundamentals with share prices that lag behind underlying business strength.
- Prioritize capital protection first by reviewing 31 resilient stocks with low risk scores designed to limit downside exposure while still giving room for upside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com