
Senior Housing Deal Could Be A Game Changer For National Health Investors Stock
- National Health Investors invested US$107.7 million to acquire six senior housing properties with 443 units across Kentucky, Michigan, and Tennessee, adding them to its Senior Housing Operating Portfolio managed by Allegro Living Management.
- The move deepens National Health Investors' relationship with Allegro Living and increases direct operating exposure within its SHOP segment, concentrating more capital in actively managed senior housing communities.
- We will now look at how National Health Investors' US$107.7 million SHOP acquisition may reshape the broader investment narrative.
National Health Investors Investment Narrative Recap
To own National Health Investors, you need to be comfortable with a REIT that leans into operating exposure through its SHOP platform rather than simply clipping rent checks. The key near term swing factor is whether senior housing occupancy and RevPOR can support consistent net operating income while the firm integrates new assets and manages labor and operating costs.
The latest US$107.7 million SHOP acquisition adds more moving parts. If Allegro executes well, the larger operating base could support steadier cash flows. If integration is bumpy or move outs stay elevated, margins could feel pressure. The deal does not remove the bigger risk around tenant concentration and funding choices, including equity issuance.
The most relevant recent context for this SHOP expansion is the emphasis on portfolio optimization and new operating partnerships across National Health Investors. Management has been leaning into operator relationships to lift margins and recycle capital from weaker properties. Allegro already sits inside that playbook, so this purchase builds on an existing framework rather than creating a new one.
For you as a shareholder, the question is whether execution on these operating relationships can offset known headwinds like occupancy softness, labor strain, and integration risk. If the Allegro run communities in Kentucky, Michigan and Tennessee achieve stable occupancy and manageable capex needs, they could support the broader catalyst of steadier NOI from the SHOP segment while keeping downside from tenant issues in check.
National Health Investors' current analyst narrative points to revenues of US$516.5 million and earnings of US$154.7 million by 2029, built on 5.8% yearly revenue growth and an earnings decline of US$11.8 million from US$166.5 million today.
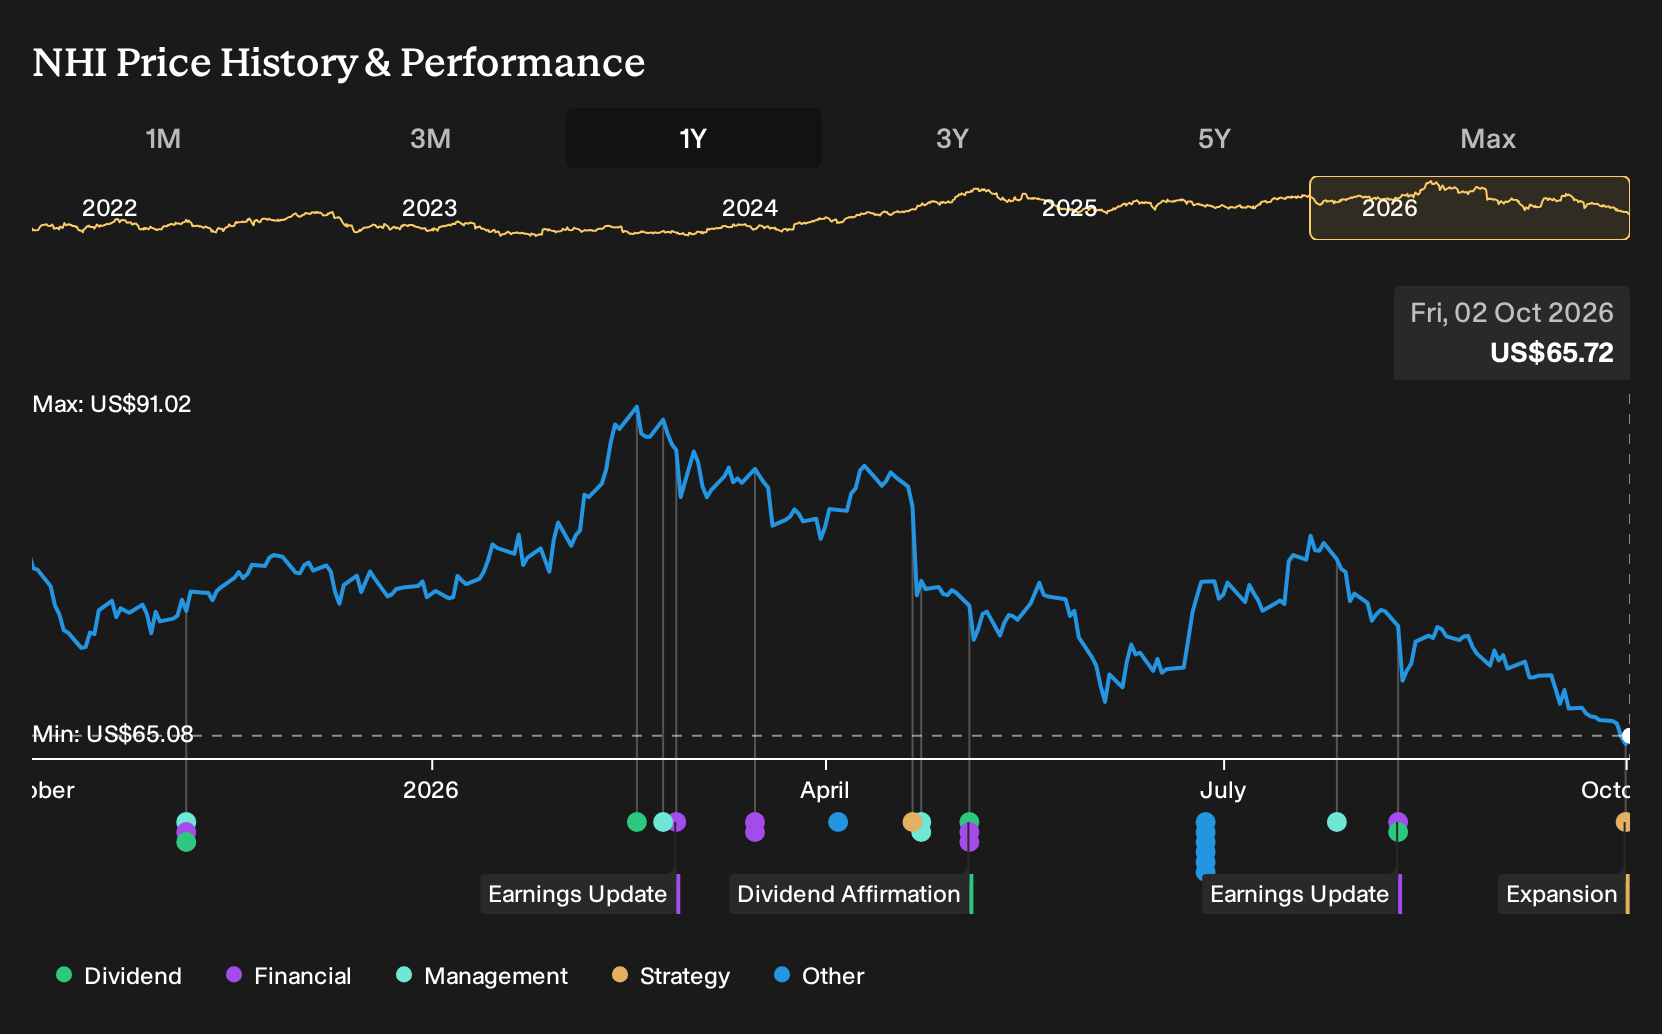
Uncover how National Health Investors' fair value indicates a 25% potential upside to its current price, which could narrow quickly if sentiment turns.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$66.59 to about US$174.82, so retail views on National Health Investors are far from aligned. That spread sits alongside real execution questions around occupancy softness, tenant concentration, and equity funding, which could all meaningfully influence how the SHOP expansion feeds into long term performance.
Explore 2 other National Health Investors fair value estimates, including one that suggests up to 166% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your National Health Investors research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for National Health Investors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Health Investors' overall financial health at a glance.
Looking for more investment ideas beyond National Health Investors?
Once you have a view on National Health Investors, it can help to pressure test that thinking against other opportunities using the Simply Wall St Screener. Comparing businesses side by side gives better context for balance sheets, cash generation, and income potential.
- For investors who care most about financial resilience, start with companies that screen well on debt, liquidity, and fundamentals through a curated list of solid balance sheet and fundamentals (26 results)
- If value is your focus, scan for businesses that combine strong quality checks with attractive pricing using a focused 31 high quality undervalued stocks
- For those building an income oriented portfolio, sort for stocks that pair higher yields with an emphasis on durability by running a targeted 7 dividend fortresses
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com