
Is Enerflex (TSX:EFX) Undervalued On Its Data Center Power Contract News?
Enerflex (TSX:EFX) is back in focus after the stock climbed 15.29% on 1 October 2026, following fresh details on a record Engineered Systems backlog and a major data center power contract.
That surge comes on top of a powerful run, with Enerflex recording a 30 day share price return of 18.51% and a year to date share price gain of 60.27%, while total shareholder return over the past year has reached 123.88%. This points to strong momentum building behind the recent contract news and portfolio reshaping moves.
Scan a curated set of power and infrastructure plays benefiting from similar data center demand with our 40 power grid technology and infrastructure stocks
After a one day jump and a big year to date climb, Enerflex now forces a timing call. Is the better move to pay up today or wait and see what the valuation math suggests?
Most Popular Narrative: 17% Undervalued
Enerflex’s most followed storyline pegs fair value at CA$42 per share compared with the latest close at CA$35.02. This puts the current excitement around data centers and gas infrastructure in the context of a longer margin and earnings roadmap rather than just a short term chart move.
Enerflex’s U.S. contract compression fleet is reported at 94% utilization on roughly 483,000 horsepower, with growth capital targeted to expand this fleet and management indicating visibility on growth into 2027. This could support revenue and return on capital employed if customer demand for natural gas compression remains healthy.
See why 1 investors see Enerflex as 17% undervalued.
Result: Fair Value of CA$42 (UNDERVALUED)
Still, the Enerflex story can change quickly if large gas projects slip or if the new data center and AI power contracts take longer to convert into revenue.
Find out about the key risks to this Enerflex narrative.
Another View: Enerflex Through The P/E Lens
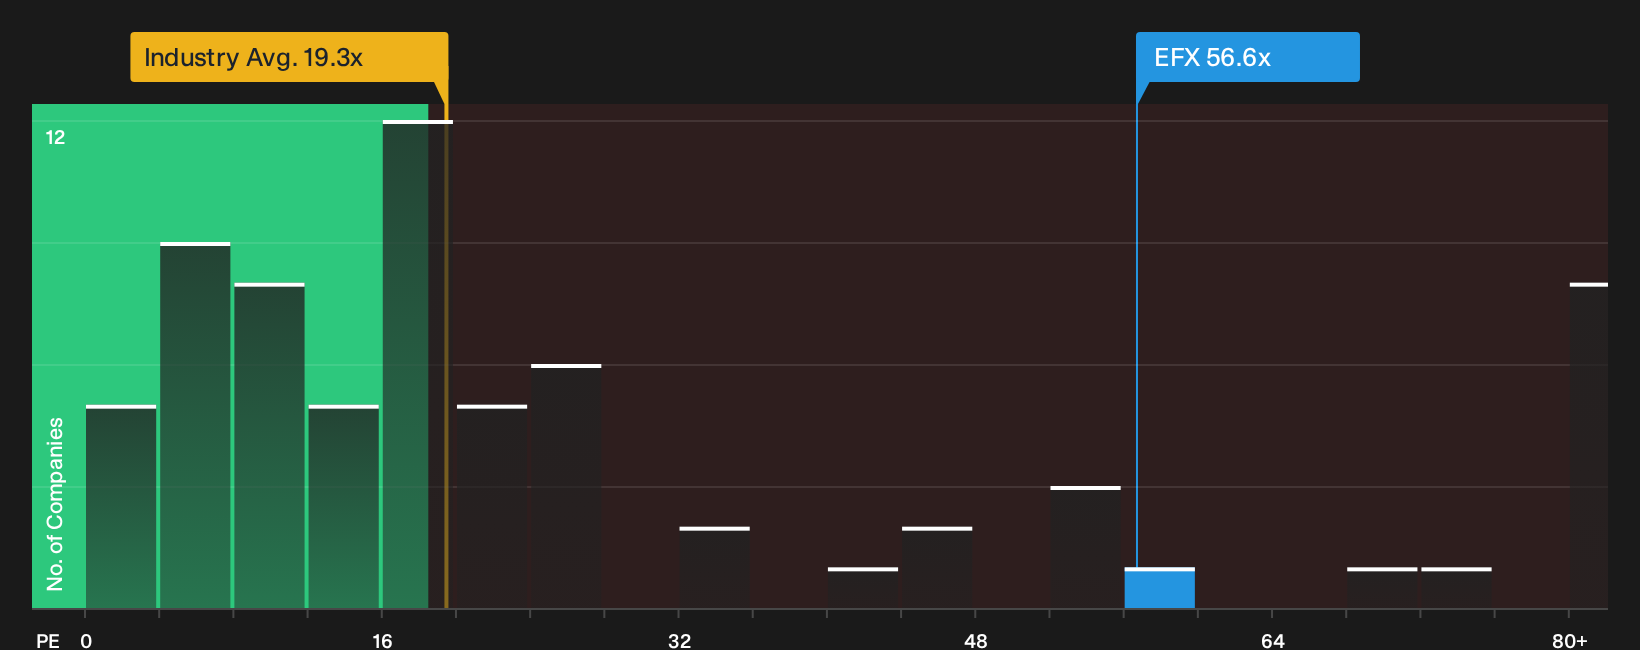
There is a catch. While the narrative pegs Enerflex at a fair value of CA$42, the current P/E of 56.6x sits far above both the peer average of 18.3x and a fair ratio of 20.3x. That sort of gap can flip from opportunity to valuation risk quickly in a rough patch.
For investors weighing that trade off against the growth story, it can help to see how the numbers stack up in detail, including where peers trade and where the fair ratio suggests the market could drift over time, through the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Enerflex’s story has clear fans and skeptics, so move quickly, pull up the full data, and decide where you land with the 3 key rewards and 2 important warning signs.
Looking for more Enerflex sized opportunities?
If Enerflex has sharpened your focus, do not stop here. Broaden your watchlist with data driven ideas that could reshape how you think about risk and reward.
- Target quality at a discount by scanning a 6 high quality undervalued stocks that filters for strong fundamentals and attractive pricing in one place.
- Prioritize resilience and sleep better at night by using a 8 resilient stocks with low risk scores that highlights businesses with sturdier financial risk profiles.
- Spot tomorrow’s potential leaders early by reviewing a 9 high quality undiscovered gems packed with underfollowed companies most investors are not watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com