
What Comes Next For Kuehne + Nagel After A 51% Gain
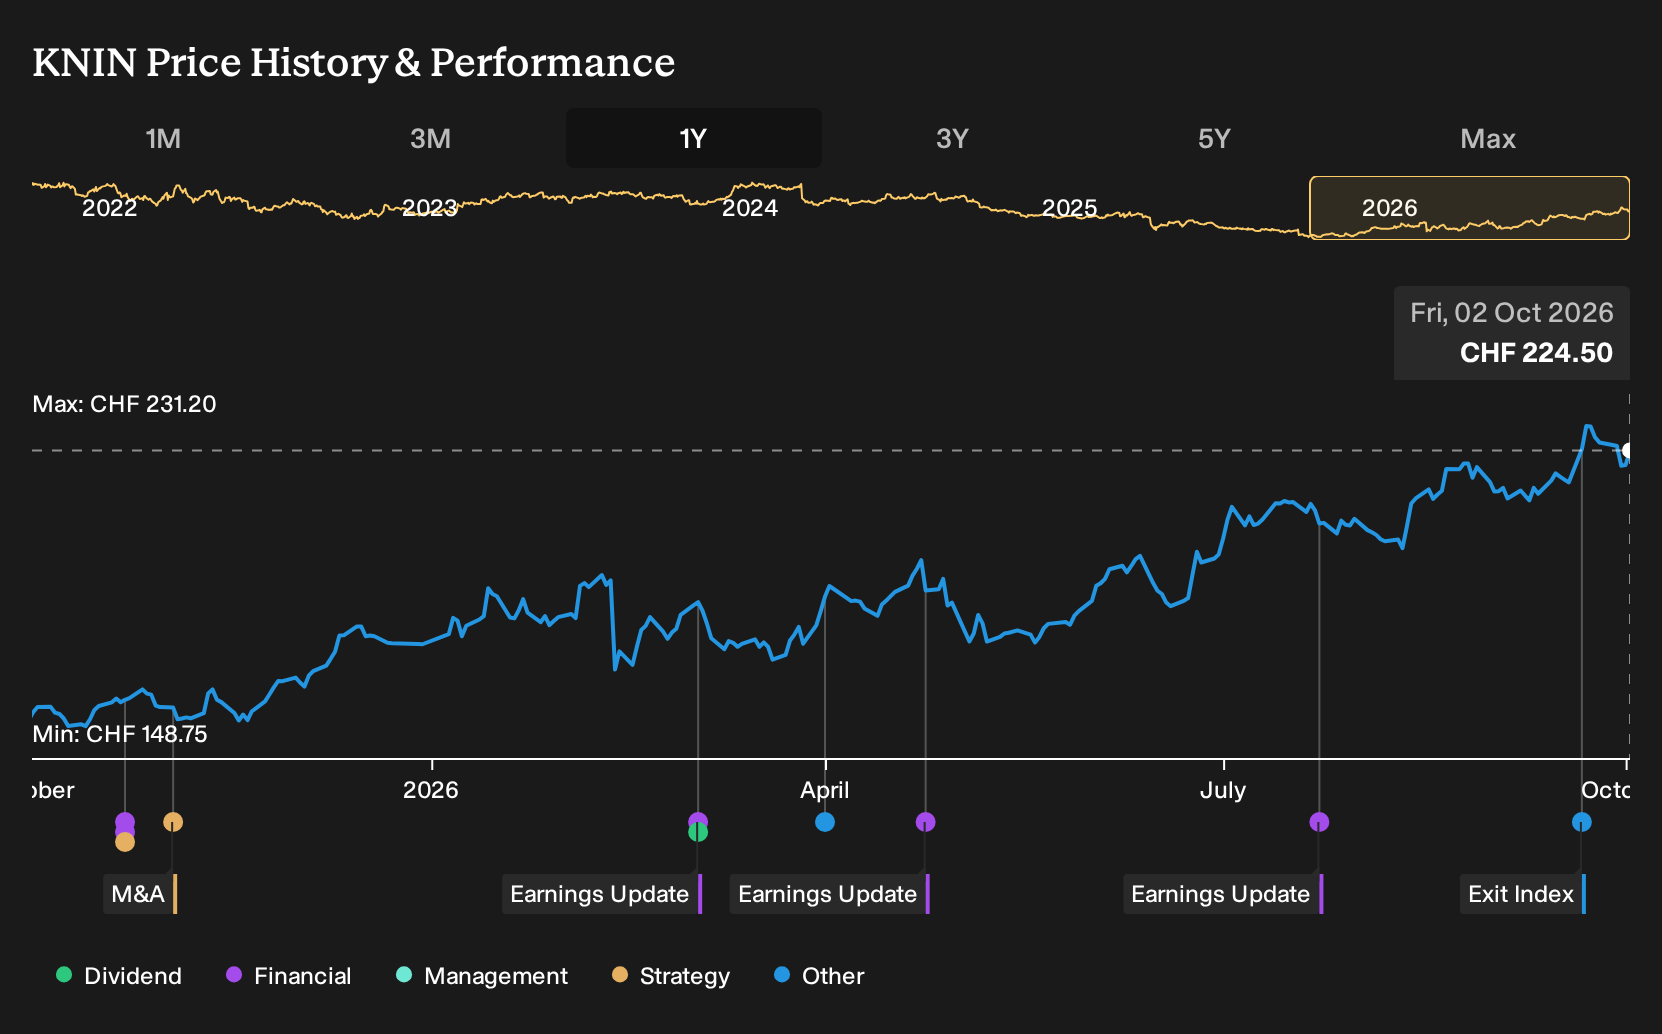
If you had been weighing Kuehne + Nagel International on 2 October 2025 and decided to commit fresh capital, your outcome today would look very different from a cautious onlooker. Holding Kuehne + Nagel International over the past year would have returned 50.9%, including dividends. That result now sits beside a split analyst view, Zacks rating upgrades, and firmer margins. If you faced that choice again, which signals at the time would really have carried the most weight?
Kuehne + Nagel International has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On Kuehne + Nagel International
The shares cost CHF153 at the start of the period, so any view on Kuehne + Nagel International hinged on whether that entry point left enough upside or downside against the competing stories.
The bullish Narrative saw a Fair Value of CHF176, an implied target price grounded in assumptions like revenue growth of 1.2% and a future P/E of 19.3x, helped by digital automation and e-commerce demand.
The bearish Narrative pointed to a Fair Value of CHF127, based on concerns that trade protectionism, digital disintermediation and pressure on freight rates could drive revenue to decline 5.4% a year and squeeze margins.
What The Results Changed For Kuehne + Nagel International
The key development was Kuehne + Nagel International reporting Q2 2026 revenue of CHF6,616m and net income of CHF268m, with net margin at 4.1% versus 3.9% a year earlier. That firmer profitability leaned toward the bullish margin assumptions, while the Zacks Strong Buy upgrades mainly reinforced sentiment rather than settling the long term volume or pricing debate. Overall, the evidence cut both ways.
The decision back in October 2025 really hinged on whether profitability would hold up as conditions shifted. When you assess another logistics stock, track whether reported net margin moves in the direction implied by the original thesis rather than relying on rating changes or chart patterns.
What Kuehne + Nagel International's Price Already Assumes
Today Kuehne + Nagel International trades at CHF224. The selected Narrative sees Fair Value below that level, which implies you would be paying up for a logistics group that has already impressed parts of the market with digital tools, acquisitions and exposure to faster growing freight niches.
The key question is what has to keep working. A buyer now would be assuming that efficiency gains and higher quality volumes can offset freight normalization, overcapacity and currency pressure enough to support earnings at this higher entry price.
"Exposure to currency pressures, weak demand, margin compression, industry overcapacity, and reliance on volatile freight segments threatens revenue growth and long-term earnings resilience."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 29% below our estimate - uses digital investing tools to capture recurring pension and savings flows.
- Company 2 - 27% below our estimate - expands specialist sales teams to secure longer-term maintenance and service contracts.
- Company 3 - 44% below our estimate - develops new flagship stores and digital channels to increase direct-to-consumer sales.
Those are three of them. See the full list of 208 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com