
USA Compression Partners (USAC) Could Be 17% Undervalued Following $600 Million Notes Issuance
USA Compression Partners (USAC) has reshaped its borrowing profile by issuing $600 million of 6.750% senior notes due 2035, with the proceeds designated to pay down existing credit facility debt and related costs.
Recent trading has been choppy for USA Compression Partners, with the share price down 7.46% over the past month and 3.57% over the last quarter, even as the year-to-date share price return is 6.85% and the 1-year total shareholder return is 18.40%.
See how USA Compression Partners compares with other income-focused infrastructure plays by checking our curated list of 7 dividend fortresses.
After the recent pullback and the fresh 6.750% notes reshaping USA Compression Partners' balance sheet, the fork in the road is clear. Is most of the easy upside already captured, or does valuation still leave meaningful room ahead?
Most Popular Narrative: 14% Undervalued
USA Compression Partners last closed at $25.42, while the most widely followed narrative pegs fair value closer to $29.67 based on its long term cash flow potential.
Robust growth in natural gas demand fueled by AI, cloud computing, and massive new data center investments is driving a sustained need for reliable, high-horsepower compression solutions, which positions USAC for ongoing contract wins and steady revenue growth.
Continued expansion in LNG export capacity and related infrastructure is creating long-term volume growth opportunities for midstream service providers, favoring USAC's specialized fleet and supporting utilization, earnings, and margin strength.
See why 6 investors see USA Compression Partners as 14% undervalued.
Result: Fair Value of $29.67 (UNDERVALUED)
Still, USA Compression Partners carries real risk if its concentrated customer base weakens or if higher capex and operating costs squeeze margins harder than analysts expect.
Find out about the key risks to this USA Compression Partners narrative.
Another View: What USA Compression Partners' P/E Is Saying
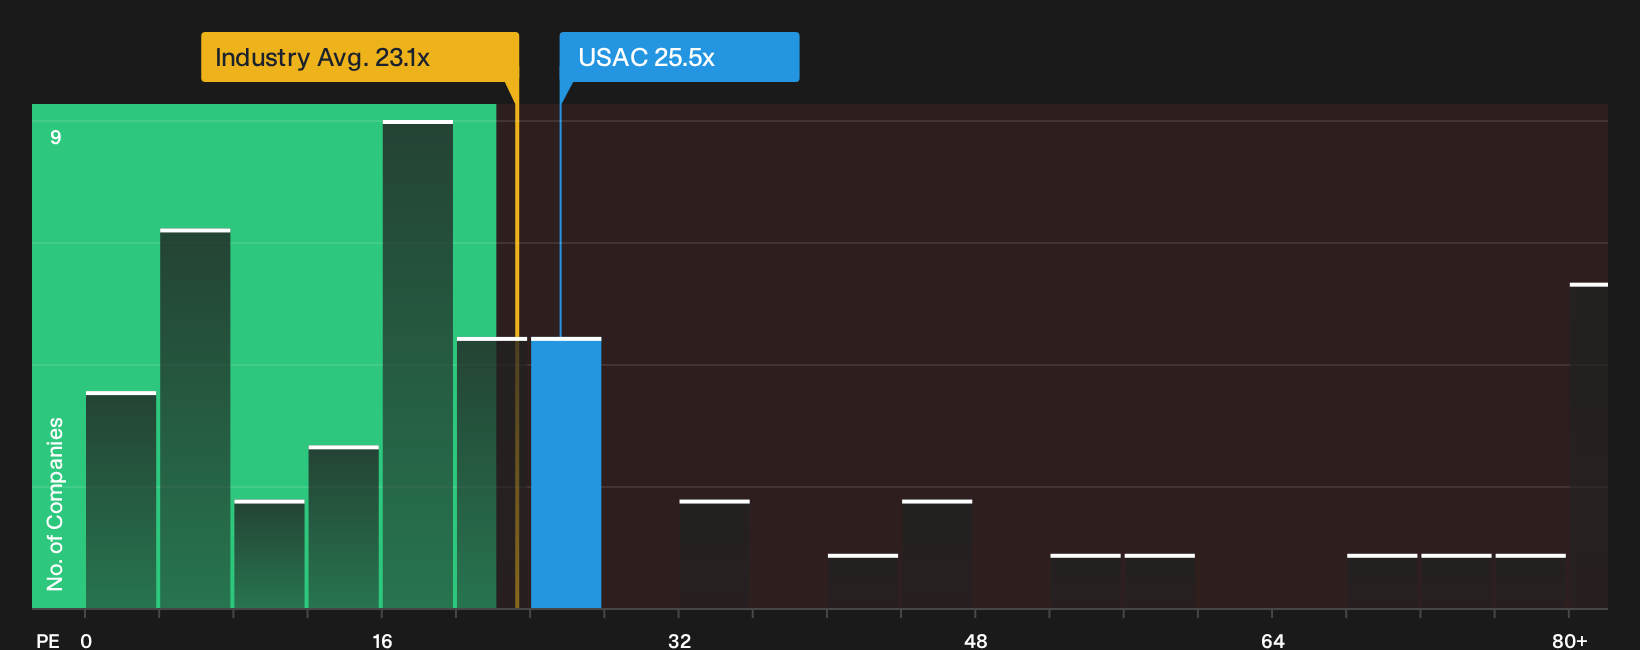
On simple earnings multiples, USA Compression Partners looks less generous. The units trade on a P/E of 25.5x, while the fair ratio is estimated at 19.5x and the broader US Energy Services group sits around 22.6x. That gap points to richer expectations. Is that premium a source of comfort, or could it be crowding out future upside?
To see how those earnings-based comparisons stack up across peers and the fair ratio that the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around USA Compression Partners can pull you in opposite directions, so move quickly to check the underlying data and weigh both sides of the story. The easiest way to balance the upside case against the concerns is to review the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond USA Compression Partners?
Do not stop with USA Compression Partners. Broaden your watchlist with focused stock ideas built from clear fundamentals, cash flows, and balance sheet strength using the Simply Wall Street screener.
- Target income plus resilience by reviewing a curated 7 dividend fortresses that aim to combine steady payouts with robust underlying businesses.
- Hunt for pricing gaps by scanning our 31 high quality undervalued stocks that filter for quality fundamentals at valuations that may warrant a closer look.
- Prioritise financial strength by zeroing in on a list of solid balance sheet and fundamentals (26 results) so you are not caught off guard by weak capital structures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com