
What Bio Rad Laboratories Stock's Recurring Revenue Shift Means For Shareholders
- Bio-Rad Laboratories has drawn fresh attention as its sales mix continues to move toward higher-margin, recurring consumables and reagents, even while instrument demand and clinical diagnostics reimbursement remain under pressure.
- The interesting shift lies in how this higher-margin, repeat revenue focus may cushion Bio-Rad Laboratories against funding swings and weaker one-off instrument orders.
- We will look at how Bio-Rad Laboratories' investment narrative is influenced by this shift toward higher-margin, recurring diagnostic revenues.
Scan beyond Bio-Rad Laboratories and compare its recurring revenue tilt with a curated list of solid balance sheet and fundamentals (26 results) designed to handle funding swings and uneven demand cycles.
Bio-Rad Laboratories Investment Narrative Recap
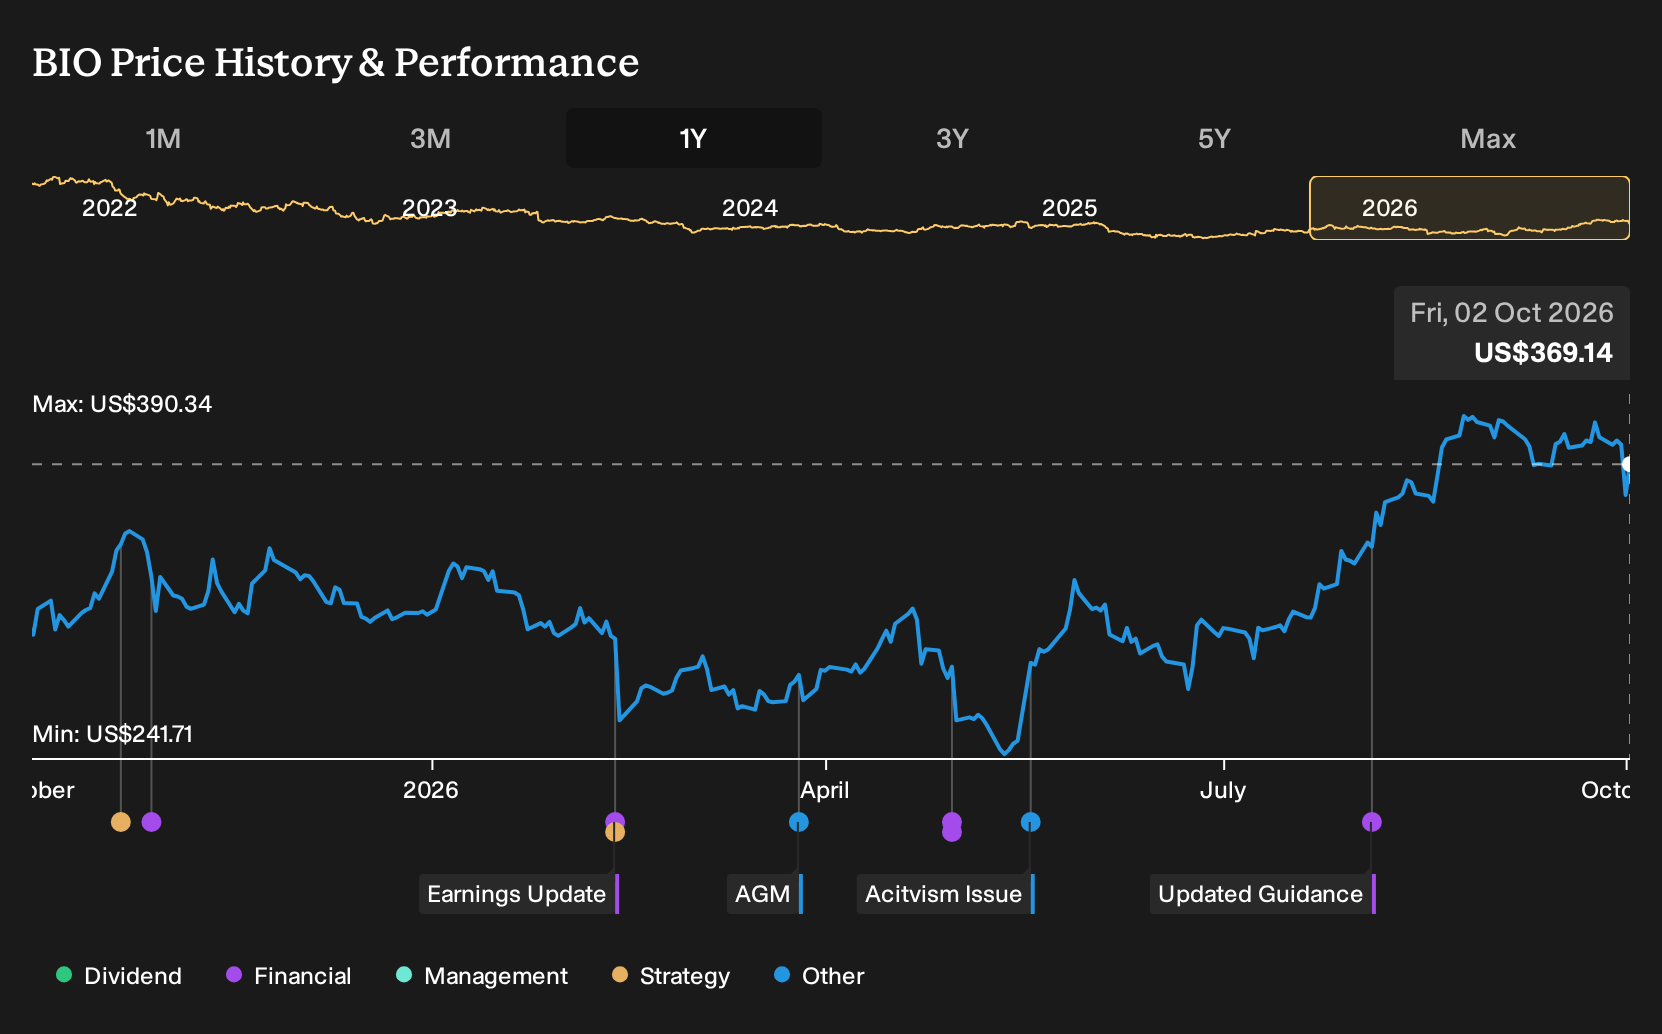
For Bio-Rad Laboratories, the big belief is that a tilt toward consumables and reagents can gradually matter more than lumpy instrument cycles. You are essentially backing a diagnostics and life science supplier that is trying to lean on repeat purchases while funding for labs and hospitals remains uneven. The recent pullback after strong 90 day and 1 year returns mainly reflects sentiment. It does not obviously change that core thesis.
The key near term swing factor is whether consumables and reagents can offset weak instrument demand and reimbursement pressure in Clinical Diagnostics, especially in China. The major operational risk is further gross margin squeeze if higher material costs persist and instrument volumes stay soft, which would keep profitability under pressure despite the healthier sales mix.
Recent discussion around Bio-Rad Laboratories has focused on share performance. However, the more relevant backdrop is still the rollout of higher value platforms like the QX Continuum and QX700 ddPCR systems and the Stilla Technologies deal. These expand the molecular diagnostics footprint and increase the potential consumable pull through tied to each installed system.
Those product lines sit alongside process chromatography and quality control offerings that are already tied to biopharma workflows and routine lab usage. Execution on these newer platforms now matters for both sides of the story. Strong adoption would support the recurring consumable narrative. Slower uptake would leave Bio-Rad more exposed to the existing risks around soft instruments, policy shifts and margin pressure.
Bio-Rad Laboratories' current analyst narrative points to revenues of $2.7b and earnings of $224.0 million by 2029, based on an assumed 1.5% yearly revenue growth rate and a move from earnings today of $222.4 million, which implies an earnings increase of about $1.6 million.
Uncover why Bio-Rad Laboratories' fair value indicates an 11% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
One alternate view on Bio-Rad Laboratories leans hard into regulatory cost risk. The most bearish analysts saw tighter price controls and compliance costs as a ceiling, so they pencilled in roughly flat revenue to about $2.6b and earnings of $232.1 million by 2029. That is a more pessimistic story than consensus. Both narratives were built before this latest share move, so treat them as starting points and explore how your own expectations might shift after the news.
Explore another Bio-Rad Laboratories fair value estimate, including one that suggests as much as 21% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Bio-Rad Laboratories research is our analysis highlighting 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bio-Rad Laboratories. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bio-Rad Laboratories' overall financial health at a glance.
Looking For More Investment Ideas Beyond Bio-Rad Laboratories?
If the Bio-Rad Laboratories story has sharpened your thinking around recurring revenue and balance sheet strength, you can extend that same lens to a broader watchlist using the Simply Wall St Screener.
- For investors who want quality at a reasonable entry point, start with a focused set of 31 high quality undervalued stocks that pair fundamentals with attractive valuations.
- If income is a priority, consider companies with stronger cash distributions by reviewing a curated 7 dividend fortresses that may suit long term payout goals.
- When capital preservation matters most, concentrate on resilience first and work through a 31 resilient stocks with low risk scores built around sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com