
What Monster Beverage Stock Leadership Change Means For Shareholders
- Monster Beverage reported that Rob Gehring, CEO Americas, resigned effective November 30, 2026, with Chief Strategy Officer Emelie C. Tirre stepping in on an interim basis to oversee the Americas and Caribbean.
- This reshuffle moves a senior commercial operator back to Coca-Cola while putting Monster Beverage’s long time strategist in direct control of its largest region.
- We will look at how Monster Beverage's investment narrative is affected by Tirre’s interim leadership over the key Americas and Caribbean region.
Scan how Monster Beverage’s leadership shuffle compares with other consumer stocks by running the curated list of solid balance sheet and fundamentals (26 results) alongside MNST in your watchlist.
Monster Beverage Investment Narrative Recap
To own Monster Beverage, you need to be comfortable with a consumer brand that leans heavily on execution in energy drinks, product refreshes and global distribution through the Coca Cola system. The short term story still revolves around keeping volumes healthy in the Americas while managing higher freight, fuel, marketing and aluminum costs so margins do not get squeezed.
The CEO Americas change looks more like management rotation than a shift in the operating playbook. Emelie C. Tirre already knows the region from her prior commercial role, which helps continuity around price increases, zero sugar mix and international expansion. The bigger near term risk remains cost pressure and underperforming Alcohol Brands.
The leadership move ties directly to Monster Beverage’s biggest commercial engine. The U.S. and Canada plus Latin America and the Caribbean together contribute more than US$6.2b of revenue, so the handover to Tirre touches the region where price actions, promotions and product launches matter most for near term earnings quality.
There is no fresh operating announcement alongside this management change. The key reference points therefore remain the existing growth drivers: expansion of zero sugar energy drinks, new affordable brands such as Predator, Fury and Bang, and deeper use of the Coca Cola distribution network still frame the main catalysts. Execution in these areas now flows through Tirre for the Americas and Caribbean, which is worth monitoring in upcoming quarters.
What The Analyst Scenario Implies For Monster Beverage
Monster Beverage's consensus narrative points to forecast revenue of US$12.1b and earnings of US$2.9b by 2029. Analysts are assuming revenue will rise by roughly 9.6% a year, with earnings increasing by about US$0.8b from US$2.1b today to reach that 2029 estimate.
Uncover how Monster Beverage's fair value indicates a 17% potential upside to its current price. This gap could narrow quickly.
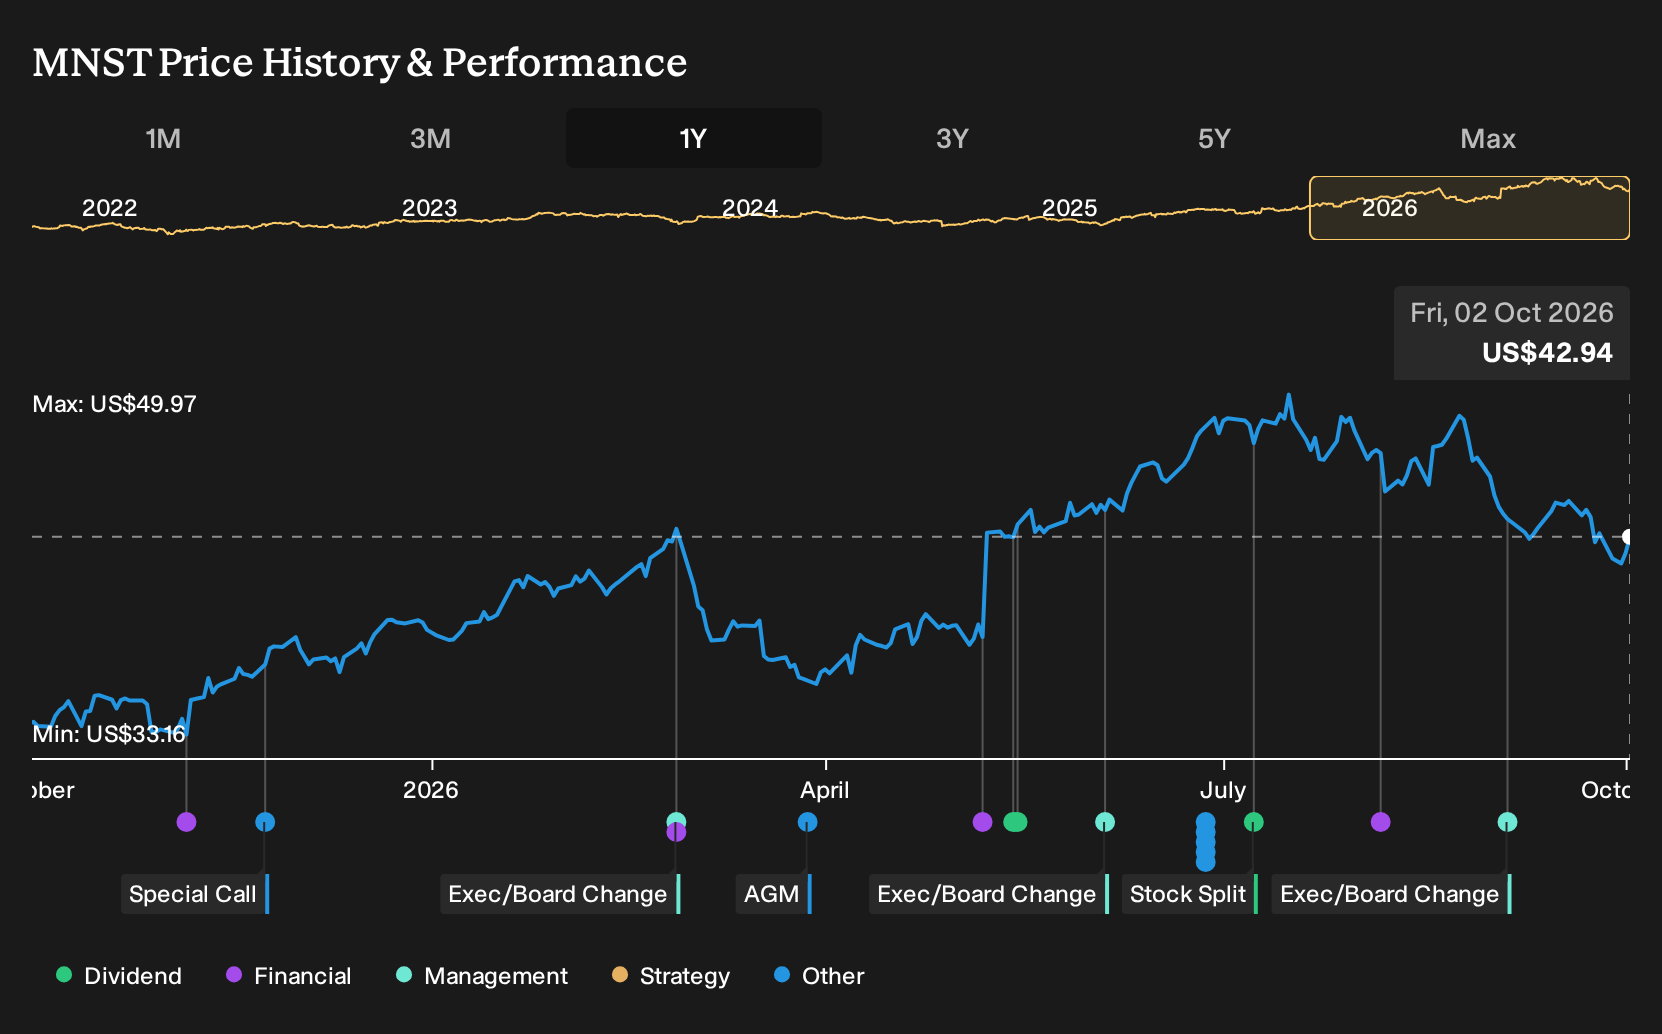
Exploring Other Perspectives
For Monster Beverage, the more cautious narrative revolves around category growth slowing. The lowest analysts were already penciling in about US$11.5b of revenue and US$3.0b of earnings by 2029 before this leadership change. You might see those estimates shift again. Treat this reshuffle as a fresh cue to compare different viewpoints.
Explore 3 other Monster Beverage fair value estimates, including one that suggests it could be worth just $41.16.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Monster Beverage research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Monster Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monster Beverage's overall financial health at a glance.
Looking for more Monster Beverage investment ideas?
Monster Beverage might be the focus today, but your portfolio benefits when you compare it with other businesses that share similar strengths or offer very different risk and return profiles. The Simply Wall St Screener can help you surface those candidates quickly so you can spend more time assessing the stories that matter to you.
- If capital preservation sits high on your priority list, scan a universe of companies with steadier profiles through the 31 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, broaden your watchlist by reviewing companies in the 31 high quality undervalued stocks.
- Income focused readers who want yield with resilience can investigate stocks in the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com