
Top 3 Australian Value Stocks To Watch In October 2026
Australian inflation is running at 4% and the local cash rate now targets 4.60%, so blunt growth stories are getting less slack. Cash generation suddenly matters again. When a business throws off solid cash but trades below an internally assessed fair value, patient investors often start paying attention. This piece walks through three undervalued Australian stocks where discounted cash flow work suggests the gap could be worth studying.
The three examples below are just a sample, and the full screen on Simply Wall St surfaced 6 more companies with similarly compelling cash flow stories that are not covered here. To identify and analyze those extra ideas alongside this shortlist, head straight to the Undervalued Stocks Based On Cash Flows screener.
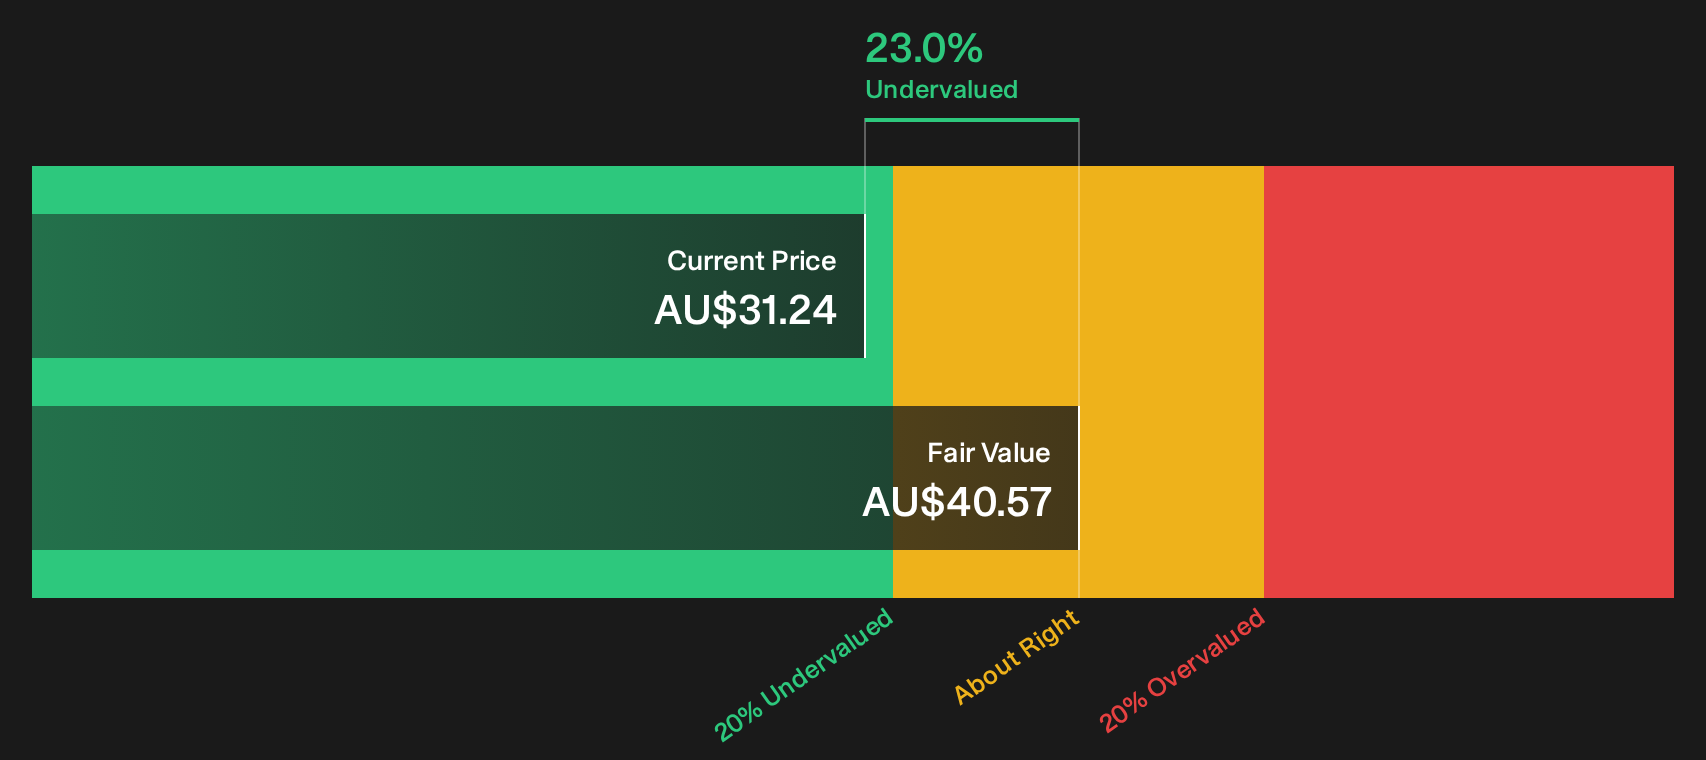
Woodside Energy Group (ASX:WDS)
Woodside Energy Group is a global hydrocarbon producer whose liquefied natural gas projects sit at the center of its cash flow story, which is what puts it on this undervalued cash flow screen.
Woodside Energy Group produces LNG, pipeline gas, crude oil and liquids across the Asia Pacific, Africa, the Americas and Europe, with about A$7.3b from Australia, A$4.6b from international operations and A$1.9b from marketing activities, and a market value near A$59.4b.
Expectations for sustained LNG demand and flawless project execution could be influenced by decarbonization trends, regulatory risks and potential project delays.
For investors watching Woodside, current attention is on how one pressure point ultimately affects long term cash generation.
That pressure point is exactly what the full narrative unpacks, so read the full narrative for Woodside Energy Group to see where Woodside Energy Group could be decoupling from market expectations.
Qualitas (ASX:QAL)
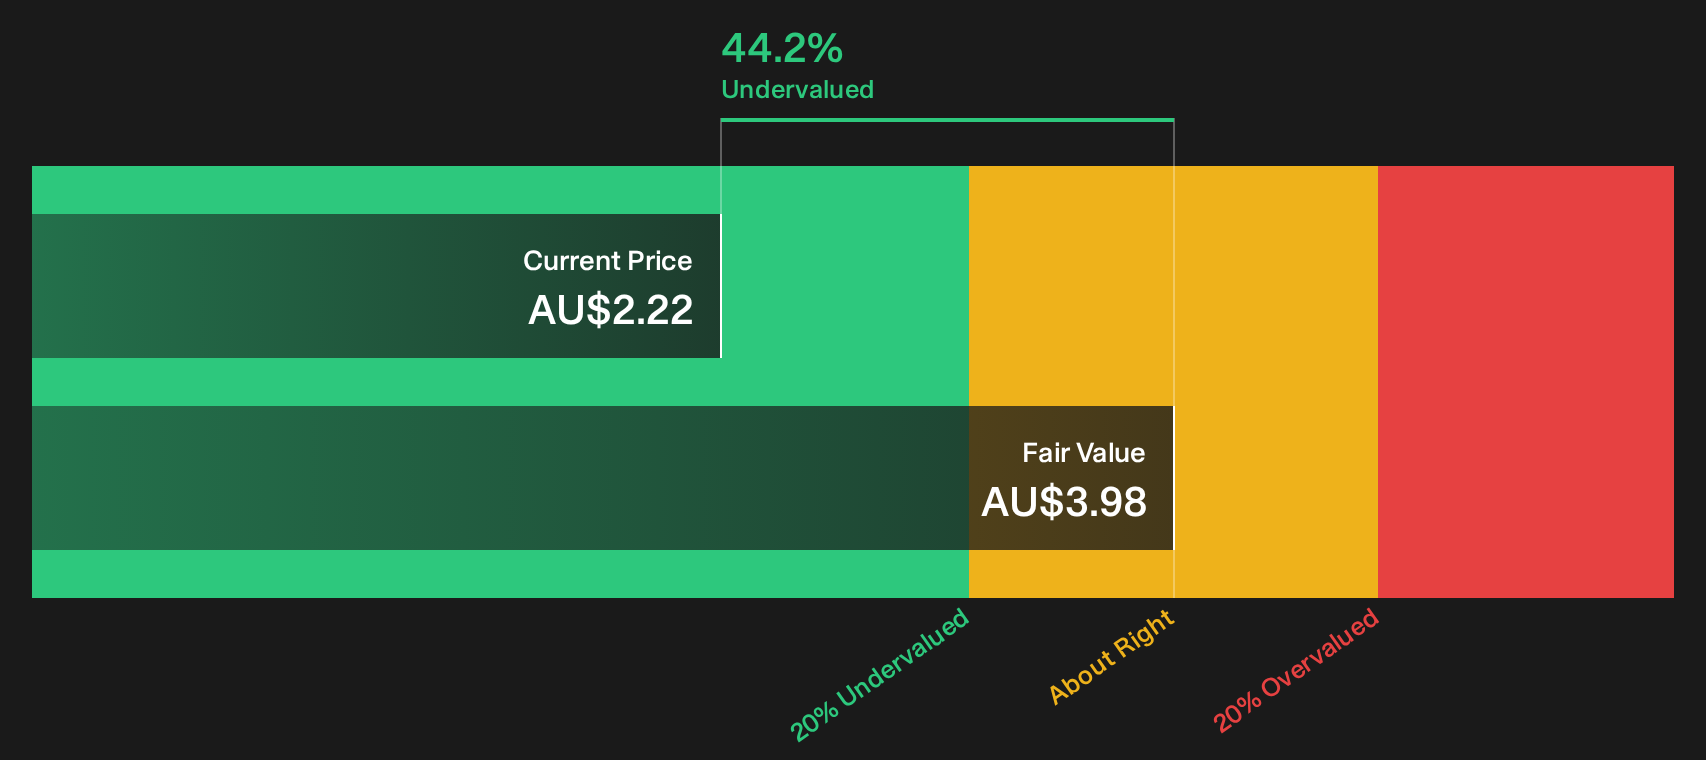
Qualitas is an Australian alternative real estate investment manager focused on real estate private credit, where secured lending and structured credit facilities create the cash flows that underpin its inclusion in this cash-flow-based undervaluation screen.
Qualitas earns about A$14.6 million from funds management and a small A$0.04 million from direct lending, giving investors exposure to fee-based cash generation, and the stock carries a market value near A$657 million.
For investors following undervalued cash flow stories, Qualitas brings a different angle as a specialist real estate lender that channels institutional capital into projects traditional banks increasingly avoid.
Banks have continued to move away from commercial property lending since 2009, and private credit’s share of Australian real estate debt has grown from 15% in 2019 to 26% today, with forecasts of 35% by 2030.
What happens to Qualitas’ cash flows if a single key assumption about how competitively it can price that lending eventually shifts?
That pricing power question is where things get interesting, so read the full narrative for Qualitas to see whether Qualitas’ fee engine is accelerating or quietly stalling.
Westgold Resources (ASX:WGX)
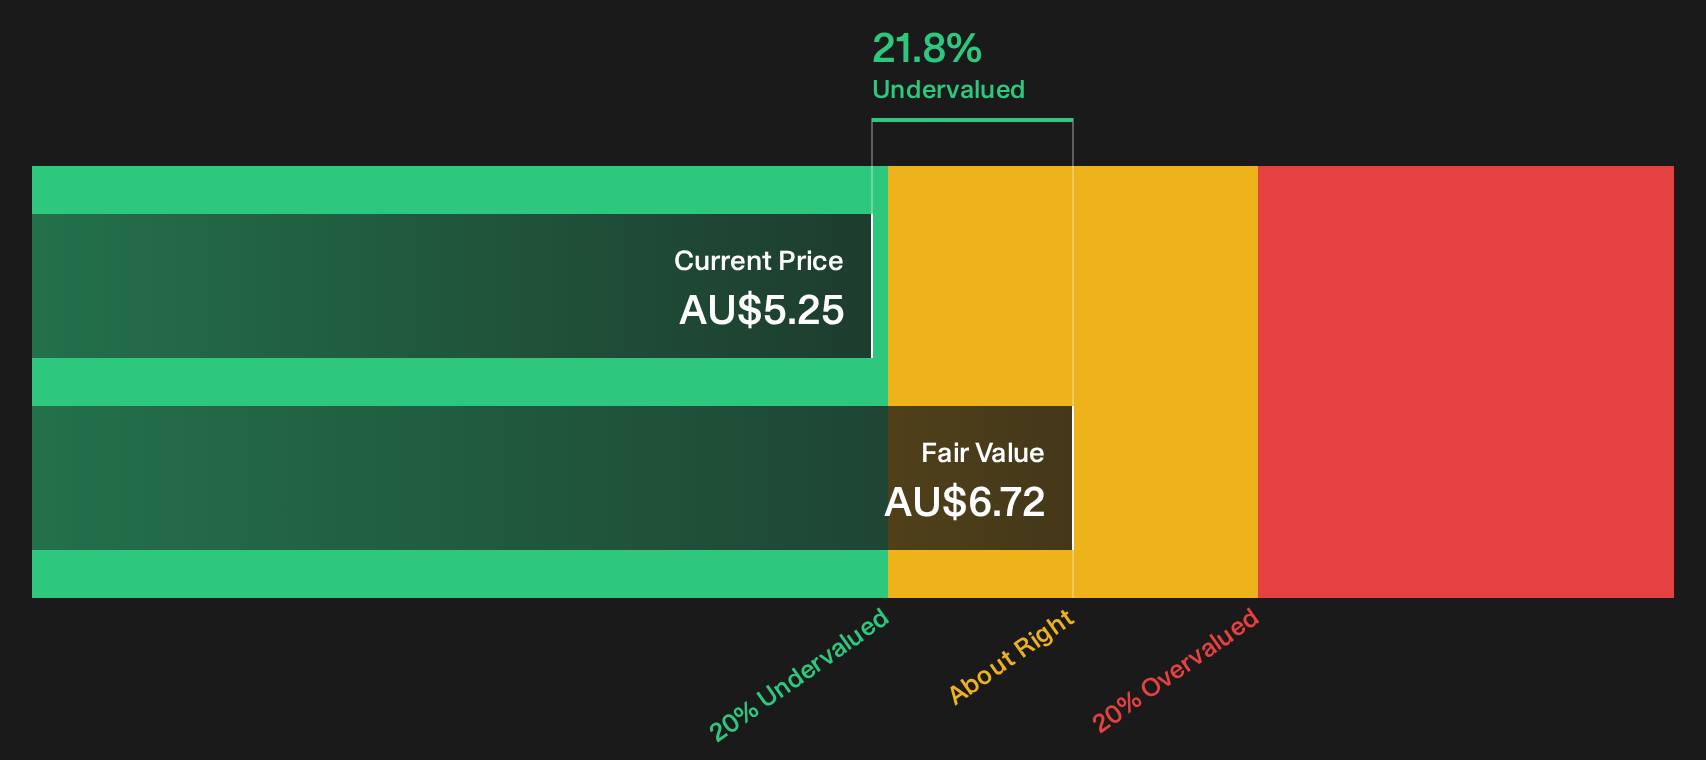
Westgold Resources is a Perth based gold producer whose Murchison operations generate about A$1.7b of revenue and Southern Goldfields about A$732 million, anchoring the cash flows behind its inclusion in this DCF screen, with the stock valued by the market at roughly A$4.9b.
For Westgold Resources, the appeal of this cash flow screen comes from hard rock assets already turning ore into saleable metal and a clear plan to push more tonnes through those Western Australian processing hubs.
"The integration of the Karora transaction has significantly increased Westgold's production scale and operational flexibility, positioning the company to benefit fully from sustained global monetary instability and rising geopolitical tensions, with upside leverage to higher gold prices directly feeding into revenue and earnings."
What investors really need to watch now is how a single cost pressure shapes the gap between those growing ounces and the margin on each one.
If that cost line is where the story really turns, read the full narrative for Westgold Resources to see whether Westgold Resources’ margin engine is quietly accelerating.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories, early momentum and quietly flying tickers often get caught by screens long before headlines. These picks stay under the radar for now, so consider them before they draw wider attention.
- Chase resilient income streams by scanning the 3 dividend fortresses that aim to keep cash returns flowing even when sentiment drops elsewhere.
- Hunt under-the-radar growth stories using the 15 high quality undiscovered gems curated for quality fundamentals that the broader market has not fully priced in yet.
- Explore the AI build out with the 90 AI infrastructure stocks focusing on hardware, data centers and backbone providers supporting that trend.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com