
Kerry Group plc (ISE:KRZ) Passed Our Checks, And It's About To Pay A €0.462 Dividend
Readers hoping to buy Kerry Group plc (ISE:KRZ) for its dividend will need to make their move shortly, as the stock is about to trade ex-dividend. The ex-dividend date is two business days before a company's record date in most cases, which is the date on which the company determines which shareholders are entitled to receive a dividend. The ex-dividend date is important as the process of settlement involves at least two full business days. So if you miss that date, you would not show up on the company's books on the record date. Meaning, you will need to purchase Kerry Group's shares before the 8th of October to receive the dividend, which will be paid on the 6th of November.
The company's next dividend payment will be €0.462 per share, and in the last 12 months, the company paid a total of €1.40 per share. Based on the last year's worth of payments, Kerry Group has a trailing yield of 1.6% on the current stock price of €86.15. Dividends are an important source of income to many shareholders, but the health of the business is crucial to maintaining those dividends. So we need to investigate whether Kerry Group can afford its dividend, and if the dividend could grow.
Dividends are typically paid from company earnings. If a company pays more in dividends than it earned in profit, then the dividend could be unsustainable. Fortunately Kerry Group's payout ratio is modest, at just 37% of profit. Yet cash flows are even more important than profits for assessing a dividend, so we need to see if the company generated enough cash to pay its distribution. Over the last year it paid out 50% of its free cash flow as dividends, within the usual range for most companies.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
View our latest analysis for Kerry Group
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If earnings decline and the company is forced to cut its dividend, investors could watch the value of their investment go up in smoke. With that in mind, we're encouraged by the steady growth at Kerry Group, with earnings per share up 5.1% on average over the last five years. Decent historical earnings per share growth suggests Kerry Group has been effectively growing value for shareholders. However, it's now paying out more than half its earnings as dividends. If management lifts the payout ratio further, we'd take this as a tacit signal that the company's growth prospects are slowing.
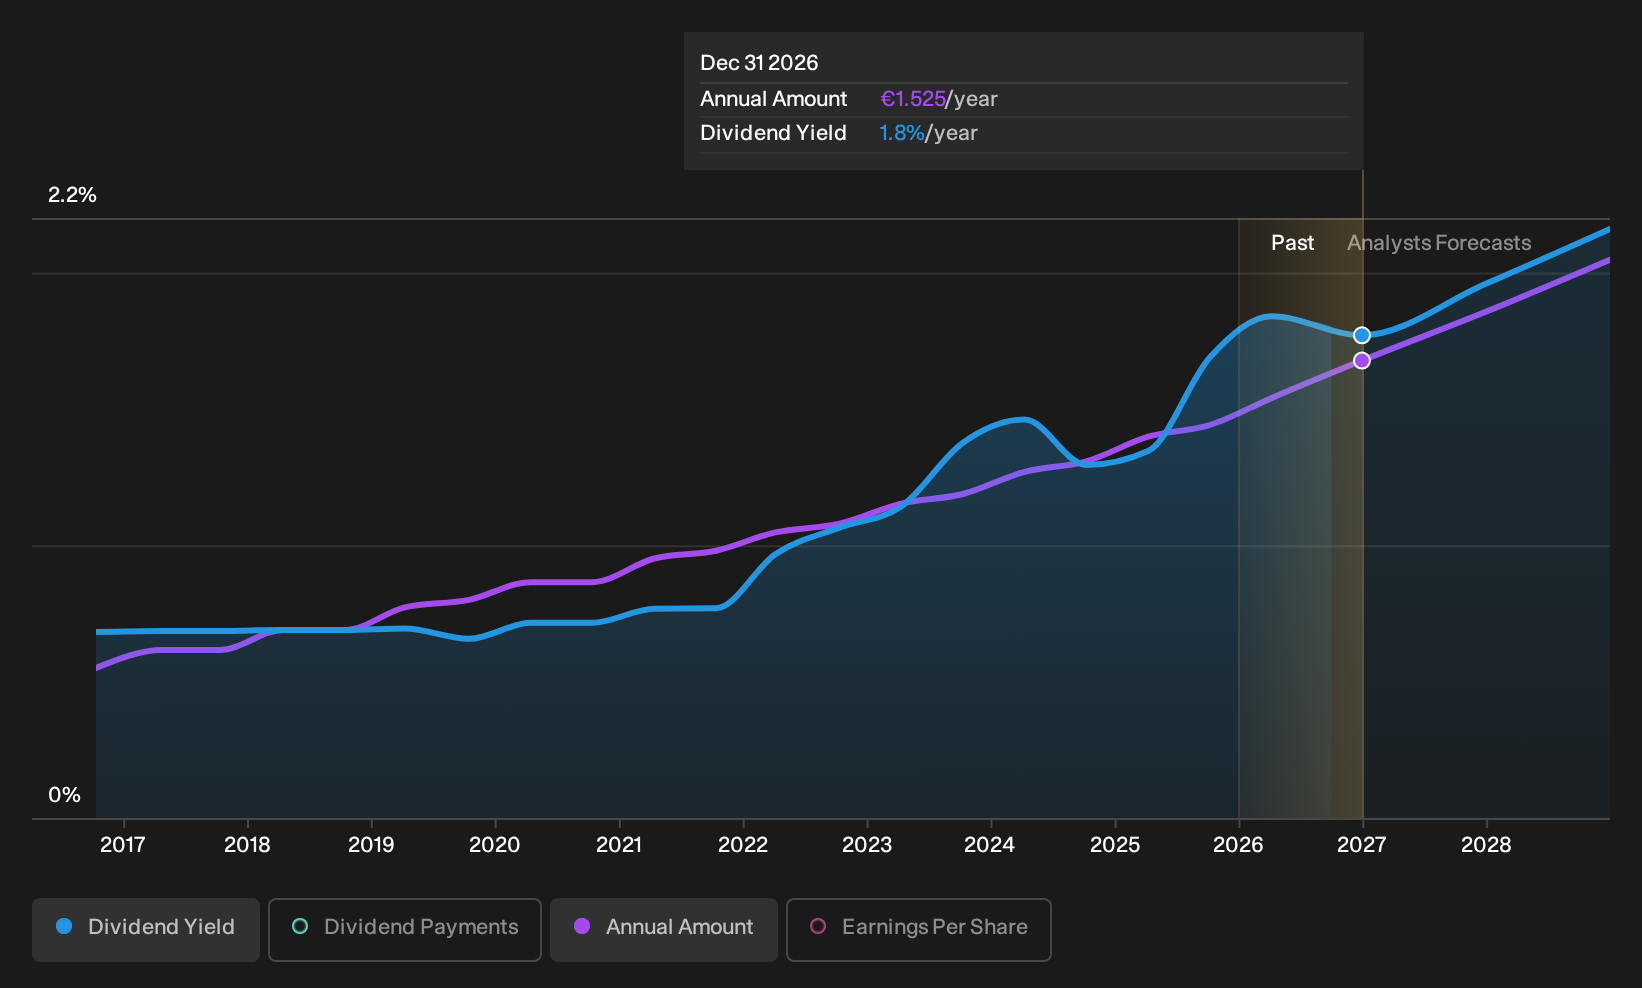
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. Kerry Group has delivered 11% dividend growth per year on average over the past 10 years. We're glad to see dividends rising alongside earnings over a number of years, which may be a sign the company intends to share the growth with shareholders.
The Bottom Line
Has Kerry Group got what it takes to maintain its dividend payments? Earnings per share have been growing at a steady rate, and Kerry Group paid out less than half its profits and more than half its free cash flow as dividends over the last year. It might be worth researching if the company is reinvesting in growth projects that could grow earnings and dividends in the future, but for now we're not all that optimistic on its dividend prospects.
Ever wonder what the future holds for Kerry Group? See what the 15 analysts we track are forecasting, with this visualisation of its historical and future estimated earnings and cash flow
Generally, we wouldn't recommend just buying the first dividend stock you see. Here's a curated list of interesting stocks that are strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.