
MSCI (MSCI) Could Be 42% Undervalued After Index Rule Questions
A Bitcoin policy think tank has challenged how MSCI (MSCI) crafted its latest index rule proposal, raising questions about stricter criteria that could see crypto treasury firms such as Strategy and Metaplanet removed from benchmark indexes.
The policy debate comes at a challenging time for MSCI shareholders. The share price closed at US$535.95 on 30 September and has declined over the past week and month. The 90-day share price return is also lower, while the 3-year total shareholder return remains positive, although momentum has eased compared with that medium-term record.
Spot potential beneficiaries or peers of MSCI's index changes by scanning our curated list of 31 resilient stocks with low risk scores with resilient profiles that may hold up better when benchmark rules tighten.Bulls point to MSCI’s index franchise and positive 3 year shareholder return, while bears focus on the recent share price slide and policy heat around crypto inclusion. Which side the current valuation leans toward next remains an open question.
Most Popular Narrative: 30% Undervalued
On the narrative view, MSCI’s fair value of $762.58 sits well above the last close at $535.95. This puts real weight behind the idea that the recent pullback has moved the stock away from what some investors see as its long term potential.
MSCI’s products are largely information and software, rather than physical products. Once the data, methodology and technology infrastructure exist, additional customers can produce very high incremental margins.
See why 7 investors see MSCI as 30% undervalued.
Result: Fair Value of $762.58 (UNDERVALUED)
Still, the MSCI story can break if index clients push back on crypto rule changes, or if recurring fee economics face pressure from lower asset values.
Find out about the key risks to this MSCI narrative.
Another View: MSCI Looks Pricey On Earnings
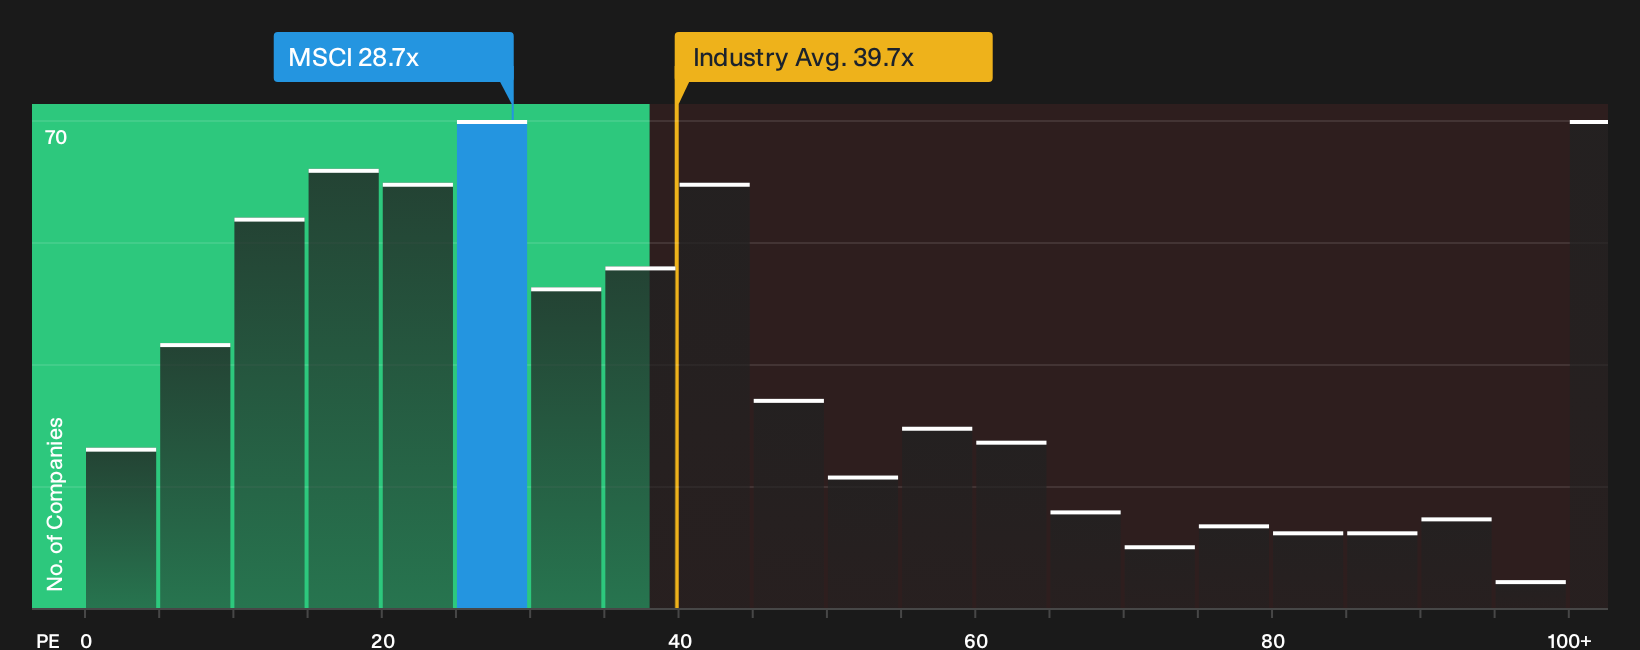
Look away from fair value models for a moment and focus on what the market is actually paying for MSCI. The stock trades on a P/E of 28.7x, compared with 24.5x for direct peers and a fair ratio of 14.9x that our work suggests the multiple could move toward.
That gap means investors are currently accepting a higher valuation risk in exchange for MSCI’s qualities as a business. The question is whether you are comfortable paying almost twice the fair ratio for the index and analytics franchise at this stage of the story.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this combination of pressure and optimism around MSCI leaves you unsure, act quickly on the data and decide where you stand by weighing its 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond MSCI?
Do not stop your research with MSCI. Broaden your opportunity set with a few focused screeners that can surface companies aligned with the way you like to invest.
- Target resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (26 results) that keeps financial strength front and center when markets get choppy.
- Hunt for potential mispricings using a focused shortlist of 31 high quality undervalued stocks that combine quality traits with more modest market expectations.
- Build a cash flow focused watchlist around income ideas screened through 7 dividend fortresses that prioritize higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com