
Pipeline Rate Challenge Might Change The Case For Investing In Exelon Stock (EXC)
- Exelon Corporation recently filed a motion to intervene with the Federal Energy Regulatory Commission on behalf of its utilities Baltimore Gas and Electric, PECO Energy, and Delmarva Power & Light, arguing that FERC decisions in a Transcontinental Gas Pipeline proceeding could directly affect their gas service rates and terms.
- The filing underlines how Exelon’s regulated utilities remain tightly linked to third party gas transportation costs, which can influence operating expenses, affect customer affordability, and shape the scope for future rate proposals.
- We will now look at how Exelon’s investment narrative could be influenced by its FERC intervention over gas pipeline rates and services.
Scan how Exelon’s gas pipeline exposure compares with other utilities by running your criteria across our curated 40 power grid technology and infrastructure stocks.
Exelon Investment Narrative Recap
To own Exelon, you need to be comfortable with a regulated utility that relies heavily on a US$41.7b capital plan, rate base growth and tight cost control rather than rapid expansion. The main near term swing factor remains how regulators treat recovery of grid and gas investments. The Transco pipeline intervention looks incremental, not a game changer.
The sharper risk is still regulatory pushback on customer affordability, especially at PECO and BGE, which could slow or reshape that investment plan and affect earnings quality. Gas transportation outcomes feed into that, because higher pass through costs can limit room for new projects and test Exelon’s 2% O&M growth discipline.
The FERC motion to intervene is the clearest recent move that ties directly to this risk reward balance. Exelon is signaling that pipeline tariffs and service terms matter for more than 1.2 million gas customers across BGE, PECO and Delmarva, which means they also matter for the group’s operating expenses and regulatory conversations.
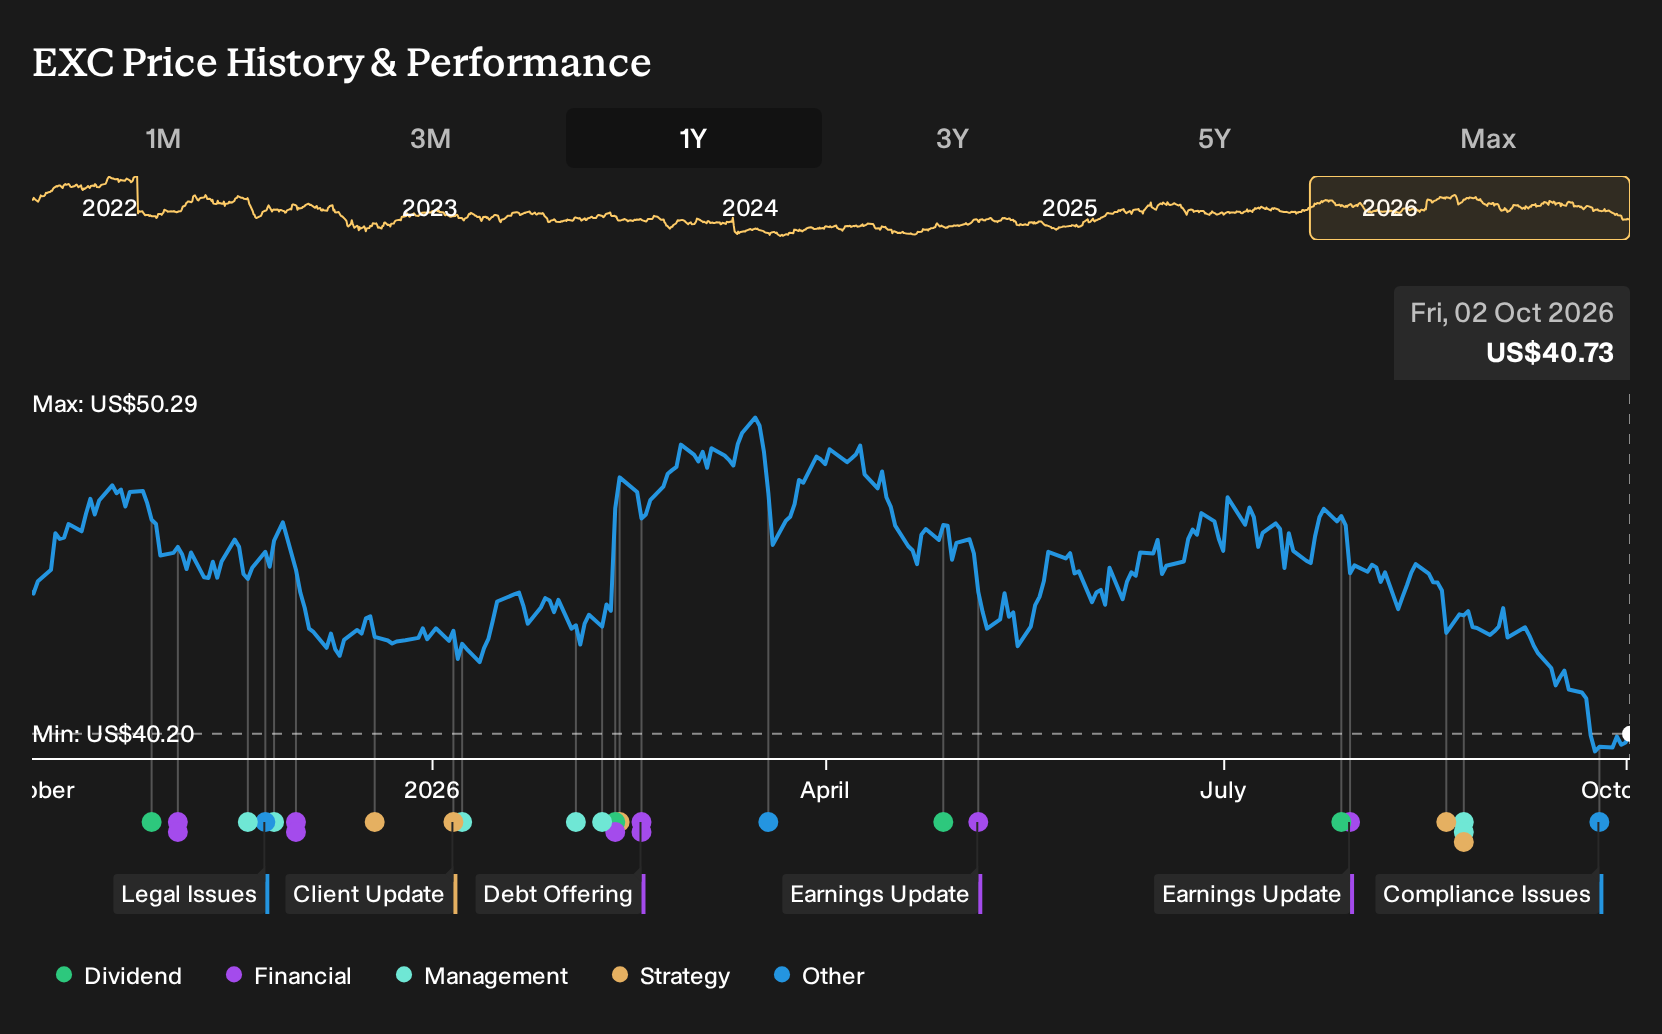
For you as a shareholder, the key question is simple: Can Exelon continue executing its multi year grid plan, manage interest expense and support a 4.12% dividend that is flagged as not well covered by free cash flow, while gas transport decisions and affordability debates continue to evolve in the background?
Exelon's current analyst story points to revenues of US$27.8b and earnings of US$3.6b by 2029, built on assumed 3.2% yearly revenue growth and an earnings increase of about US$0.8b from US$2.8b today to the forecast consensus level.
Uncover why Exelon's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$9.37 to US$48.71 per share, which already shows how far retail opinions on Exelon can spread. Those views do not reflect the recent FERC intervention or ongoing rate case uncertainty, so investors may want to compare them with updated scenarios based on regulatory outcomes and capital plan execution.
Explore another Exelon fair value estimate, including one that suggests as much as 77% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Exelon research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Exelon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Exelon's overall financial health at a glance.
Looking For More Ideas Beyond Exelon?
Once you have a view on Exelon, it can help to compare it with other opportunities that match your preferred mix of quality, risk and income. The Simply Wall St screener lets you filter for traits that matter to you and quickly build a focused watchlist.
- If capital preservation is front of mind, start with sturdier balance sheets and steadier fundamentals using our 31 resilient stocks with low risk scores.
- If you want businesses that combine strong finances with room to grow, scan candidates in the 19 high quality undiscovered gems that might not be on every radar yet.
- If reliable cash generation appeals to you, focus on income heavy opportunities screened in the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com