
Is Honeywell International (HON) A Bargain On The Dangote Refinery Win?
Honeywell International (HON) drew fresh attention after Dangote Petroleum Refinery selected its process technologies and digital solutions for a planned 700,000 barrel-per-day refinery in Kenya, which is one of the largest single-train projects globally.
The Honeywell International share price at US$213.99 has edged higher over the past month, with a 1 month share price return of 3.84%. However, the 90 day share price return is down 6.90%, while the 1 year total shareholder return of 5.68% and 3 year total shareholder return of 24.85% point to momentum that has built more over time than in the very short term, as investors weigh recent project wins like the Dangote refinery contract alongside a dividend affirmation and softer recent trading in the stock.
Scan beyond Honeywell International and the Dangote refinery contract by reviewing a curated set of industrial and infrastructure plays in our 40 power grid technology and infrastructure stocks
Honeywell International now trades higher on contract buzz while still carrying a weaker recent 90 day share price record. Has most of the easy upside already passed, or does the current valuation still leave meaningful room?
Most Popular Narrative: 33% Undervalued
The most followed valuation story on Honeywell International pegs fair value at $320.19 per share, versus the recent $213.99 close. This points to a wide gap that this view attributes to how the market is treating Honeywell’s automation and energy technology exposure.
HON RemainCo is a pure-play industrial automation and energy technology compounder with a confirmed June 29 catalyst, $19B+ in contracted backlog, a sold-out LNG order book, a global SAF technology licensing position, a recurring revenue platform transition underway via Forge, and an embedded position on both sides of the energy transition, all trading at a conglomerate discount that disappears in 53 days.
See why 67 investors see Honeywell International as 33% undervalued.
Result: Fair Value of $320.19 (UNDERVALUED)
Still, Honeywell International faces two clear pressure points: softer recent 90 day share performance, and annual declines in revenue and net income growth that could challenge that 33% undervalued story.
Find out about the key risks to this Honeywell International narrative.
Another View: SWS DCF Model Flags Honeywell as Overvalued
The popular Honeywell International narrative leans on a $320.19 fair value, yet the SWS DCF model paints a different picture. In that framework, intrinsic value sits at $137.49 per share, well below the current $213.99 price. This raises the question of whether cash flow assumptions are tighter than the bullish story suggests.
Look into how the SWS DCF model arrives at its fair value.
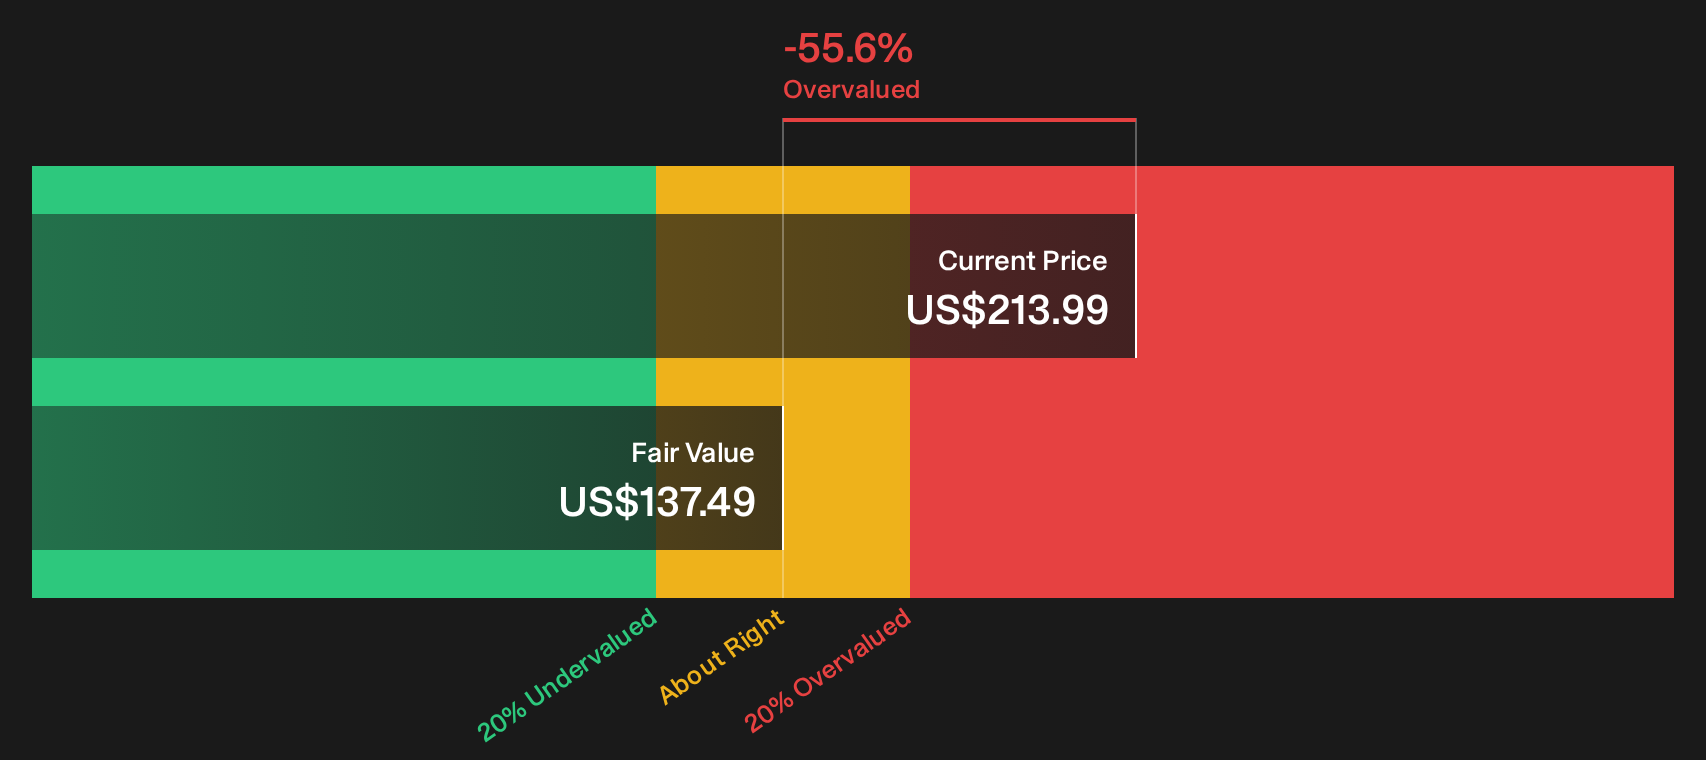
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Honeywell International can either be noise or a useful prompt, depending on how quickly you dig into the details yourself. To size up both sides of the story before sentiment shifts again, start with the 4 key rewards and 3 important warning signs.
Looking for more Honeywell International sized investment ideas?
If Honeywell International has you thinking harder about where you put your next dollar, do not stop at a single ticker when better risk reward lineups might be one screen away.
- Target steadier compounding by reviewing a curated 31 resilient stocks with low risk scores that can help you reduce portfolio swings without stepping entirely out of the market.
- Hunt for strong businesses at marked down prices by scanning our 31 high quality undervalued stocks so you are not relying on a single underappreciated story.
- Boost your potential income stream by reviewing a 7 dividend fortresses that focuses on higher yielding payouts while you assess total return potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com