
After Unicaja Banco's 51% Run, The Hard Part Still Has To Hold
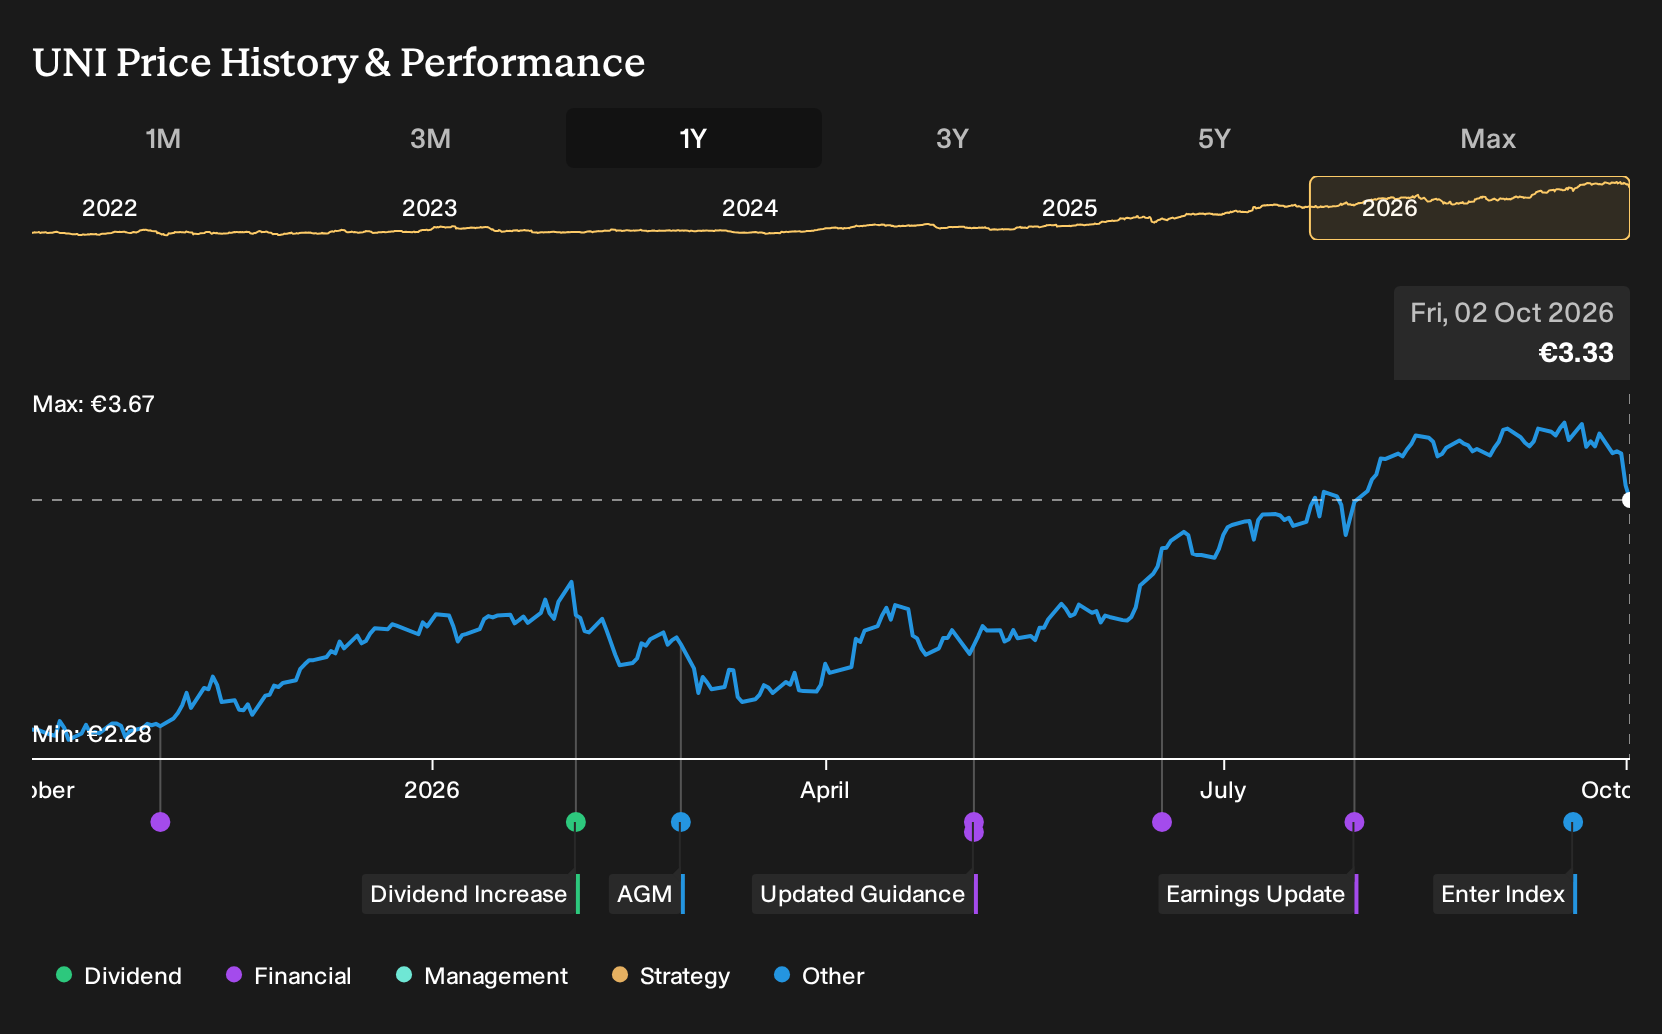
If you only skimmed the mixed analyst views on Unicaja Banco in late 2025, this outcome might feel surprising. Holding Unicaja Banco over the past year would have returned 50.7%, including dividends. That gain arrived in a period when one bullish camp pointed to digitalization and under-banked regions, while a cautious group questioned margin resilience and valuation. If you had been weighing those opposing arguments on 2 October 2025, what exactly was knowable then about the trade-off you were taking?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Unicaja Banco has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Arguing About
The shares cost €2.32 at the start of the period, and Unicaja Banco sat between two sharply different but plausible stories about what came next.
The bullish narrative put fair value at €2.90, based on the idea that digitalization, under-banked regions and the Liberbank merger could support structurally higher net margins and room for what were seen as sustainably rising dividends.
The bearish view pinned fair value at €2.02, warning that expected compression in net interest margins and limits to cost cuts could pull earnings and profitability below the optimistic assumptions in the price.
What The Results Changed For The Unicaja Banco Debate
The clearest new clue came from Unicaja Banco's Q2 2026 report. Total revenue reached €555.262 million with net income at €193.647 million, and net margin moved from 33.7% in Q2 2025 to 34.9%. A green note buyback and new issue aimed at MREL and liquidity management added support for the more optimistic story, so the period leaned toward the bullish case.
The key lesson is simple. When a thesis hinges on margin resilience, keep checking reported net margin rather than only watching revenue or headlines about capital actions.
What Unicaja Banco's Run Already Prices In
Unicaja Banco now trades at €3.33, and this Narrative's Fair Value sits below that quote based on a more cautious read of the business. The current view leans on concerns that digital disruption and regional headwinds could constrain the bank's ability to keep compounding profitability.
For today's valuation to hold, you would need confidence that Unicaja's digital transformation and cost discipline keep offsetting pressure on margins from fintech rivals and slower core markets.
"As digital banking adoption accelerates and nimble fintechs continue to capture market share for payments, lending, and savings products, Unicaja Banco faces mounting pressures on fee income and customer retention. Over the long term, this digital erosion threatens both revenues and net margins, especially given Unicaja's mixed record on technological innovation and digital transformation."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 44% below our estimate - uses AI driven matching and integrated datasets to connect employers with suitable candidates.
- Company 2 - 47% below our estimate - sells treatment planning software compatible with varied hardware to streamline oncology clinic workflows.
- Company 3 - 27% below our estimate - adds sales staff focused on elevator maintenance contracts that support later modernization projects.
Those are three of them. See all 208 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com