
3 Canadian Growth Stocks With Up To 67% Earnings Growth
The Federal Reserve has just lifted interest rates for the first time since 2023, which often puts faster growing companies under the spotlight as investors reassess what they are willing to pay for future earnings. Canadian businesses that are already expanding and where insiders hold meaningful stakes can look especially interesting when money feels more selective. This article highlights three such growth stocks with high insider commitment.
The three companies highlighted next are just a starting sample, and the full screen surfaced 46 more businesses with similarly compelling growth stories and insider ownership levels that are not covered here. If you want to go deeper straight away, use the Fast Growing Stocks With High Insider Ownership screener to identify, filter, and analyze the highest conviction ideas that fit your own criteria.
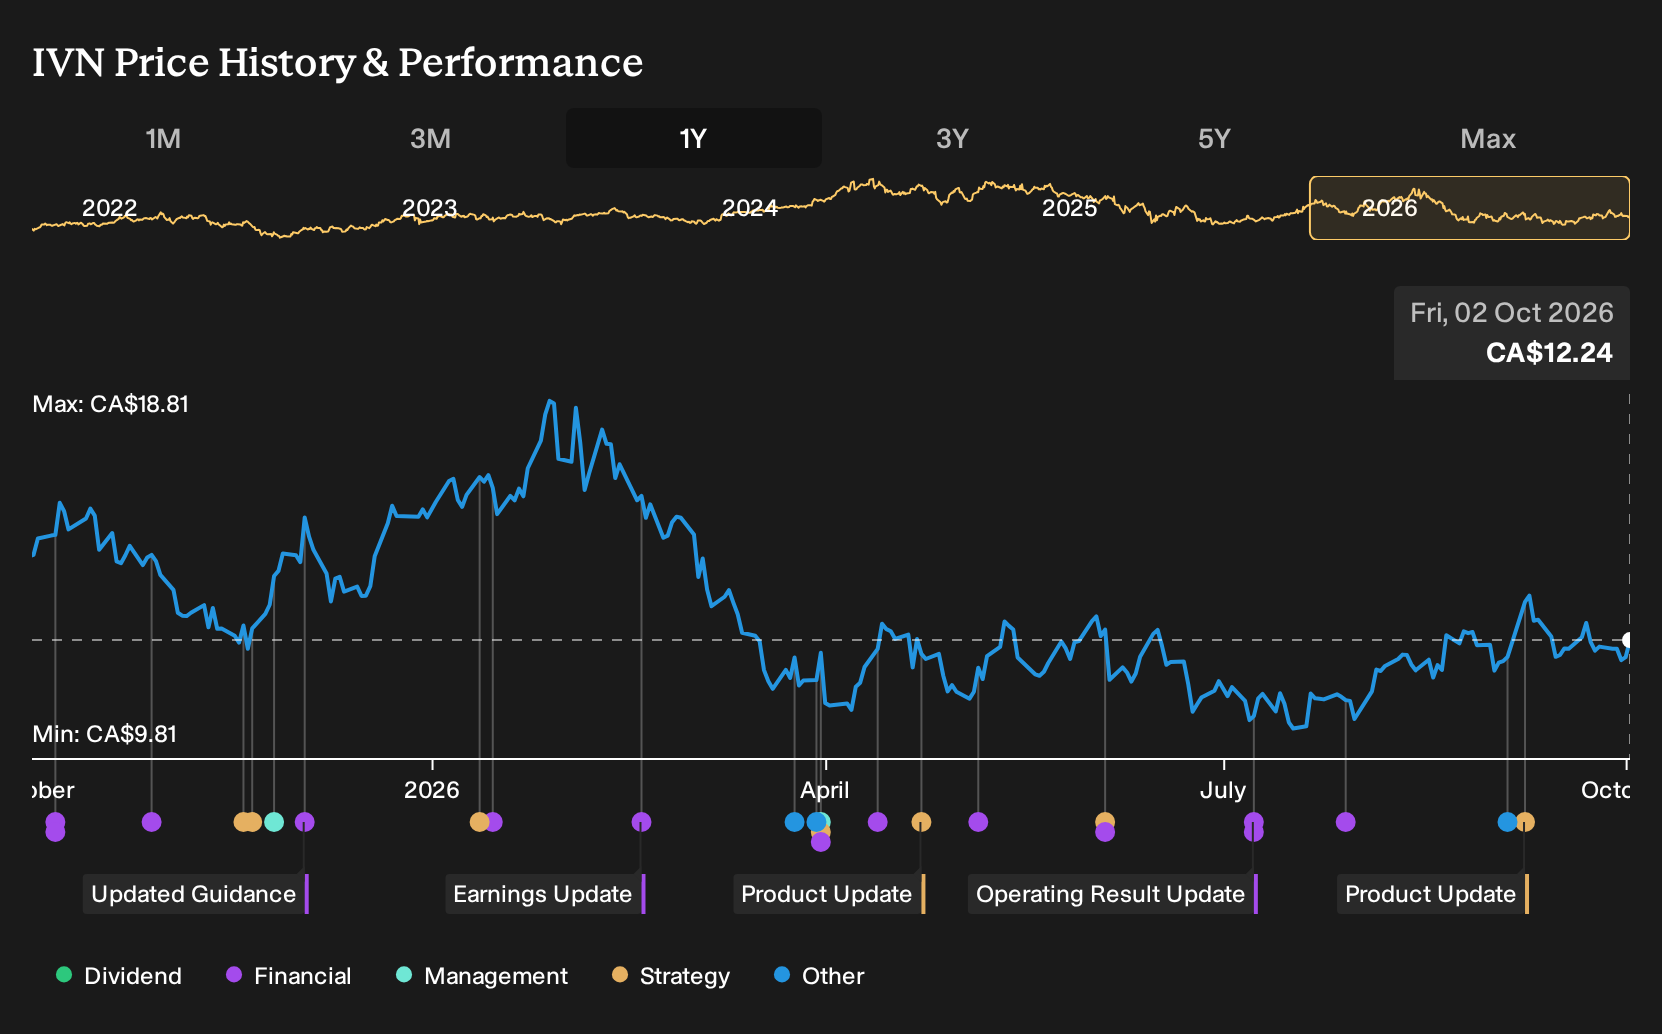
Ivanhoe Mines (TSX:IVN)
Ivanhoe Mines is a diversified African-focused miner that investors often link to fast growth and insider commitment through its flagship Kamoa-Kakula copper complex. Its scale means any shift in expectations can move the story quickly.
Ivanhoe Mines develops and operates large mining projects across Africa, with revenue of about $575 million mainly from Kipushi properties, and a market value of roughly CA$16.8b.
"Catalysts stacked (Phase 3/4 Kamoa ramp to >550 ktpa medium term, Platreef Phase 2, Kipushi de-bottlenecking, smelter online, Project 95 recoveries, exploration)."
What happens if one unseen swing factor changes how confidently those future volumes can support the current growth expectations?
That unseen swing factor is exactly where the full narrative for Ivanhoe Mines digs in, separating temporary noise from shifts that could accelerate or stall Ivanhoe Mines over time.
Cascades (TSX:CAS)
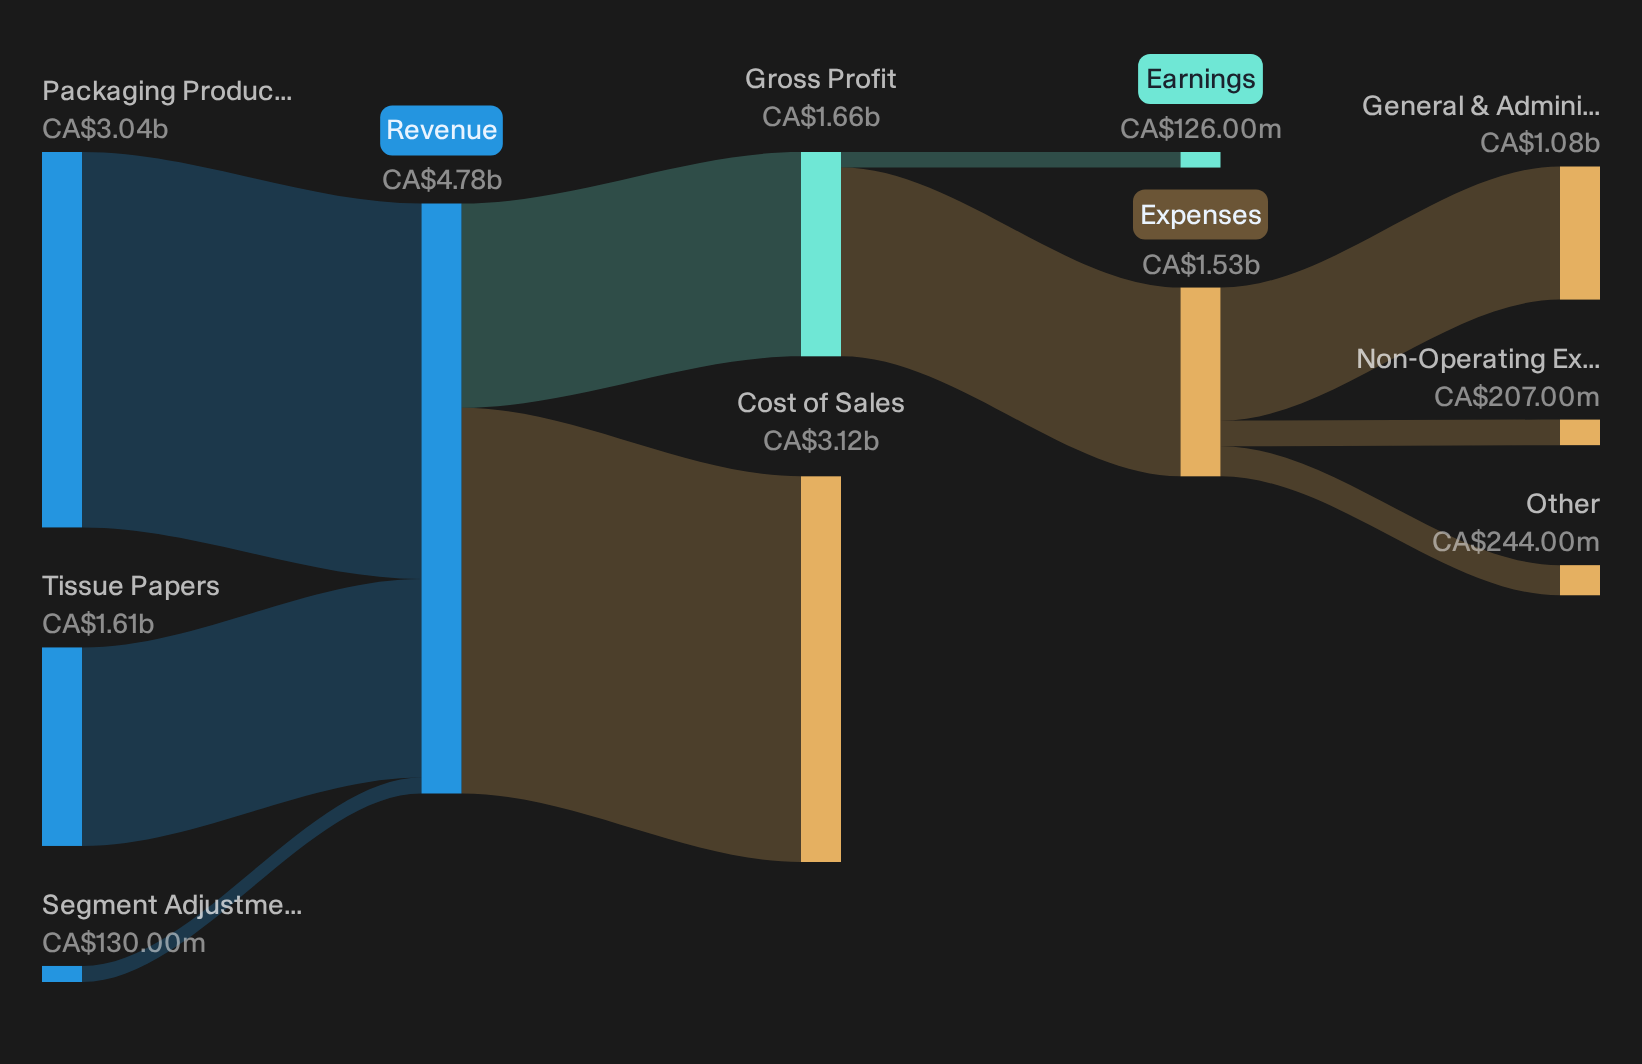
Cascades blends packaging and tissue operations, but its e-commerce and protective packaging line is the clearest tie to fast-growing online retail demand. Packaging Products generated about CA$3.0b of the CA$4.8b segment total in the latest year, with Tissue Papers at CA$1.6b, and the stock is valued around CA$1.9b.
Cascades gives this screener a different flavour, because its growth potential is tied to both everyday essentials and the cardboard infrastructure behind online shopping.
"Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins."
What really matters now is how one unresolved cost pressure shapes that margin story investors are starting to price in.
If that pressure is the hinge on Cascades’ next phase, the full narrative for Cascades shows whether efficiency gains are merely masking risk or setting up accelerating cash generation.
Highlander Silver (TSX:HSLV)
Highlander Silver is a Toronto based explorer focused on the San Luis silver and gold project in Peru, fully owned and central to the growth and insider alignment behind this screener’s theme. The stock is early stage with no revenue yet and a market value around CA$1.5b.
Highlander Silver now links its 100% owned San Luis project and insider aligned upside to actual numbers, with a market value near CA$1.5b. The catch is how one funding dependent assumption holds up as exploration and development move forward.
That funding hinge is exactly where the analysis report for Highlander Silver starts to separate blue sky upside from the assumptions that could quietly stall Highlander Silver’s story.

Seeking Fresh Alternatives Before They Fly
Fresh breakout stories rarely stay under the radar for long. Momentum shifts fast, prices move, and good information decays. Scan new ideas before the crowd arrives and get in early.
- Spot cash rich businesses built for staying power by running the list of solid balance sheet and fundamentals (7 results) while the market focus is still elsewhere.
- Explore potential income opportunities by checking the 1 dividend fortresses.
- Look for miners with operational torque using the curated 36 elite gold producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com