
Starbucks (SBUX) Closes Stores As Back To Starbucks Puts Valuation Back In Focus
Starbucks (SBUX) is trimming its North America footprint, with the board approving plans to shut roughly 1% of more than 18,000 coffeehouses as part of its Back to Starbucks store refresh program.
The store refresh comes after a weaker patch for the Starbucks share price, with the stock down 11.25% over the past 30 days and 9.17% over 90 days. Even so, the year to date share price return is 12.79% and the 1 year total shareholder return is 12.39%. This points to longer term holders still being in positive territory, while shorter term momentum has faded as investors weigh the impact of restructuring charges and a slower pace of net new store openings against the broader Back to Starbucks plan.
Compare Starbucks' reset with other consumer-focused businesses that could be setting up for their next move in our curated list of 31 high quality undervalued stocks.
Bulls see Back to Starbucks pruning weak stores to support a healthier US$108.1b franchise. Bears focus on closures, charges, and slower openings. Which story does the current valuation actually reflect?
Most Popular Narrative: 16% Undervalued
The most followed Starbucks narrative pegs fair value at $112.23 versus a last close of $94.71. The gap it highlights is material and depends heavily on how the Back to Starbucks plan feeds into earnings power over time.
The Back to Starbucks plan, including Green Apron Service, standardized store scorecards, and a $2b cost-savings program through fiscal 2028, is still in progress and is expected to continue affecting operating margins and earnings as more of the targeted savings and process changes flow through the P&L.
See why 227 investors see Starbucks as 16% undervalued.
Result: Fair Value of $112.23 (UNDERVALUED)
Still, Starbucks faces real pressure from unionisation efforts that could keep labor costs higher, as well as from legal or regulatory actions that may lift compliance spending.
Find out about the key risks to this Starbucks narrative.
Another View on Starbucks Valuation
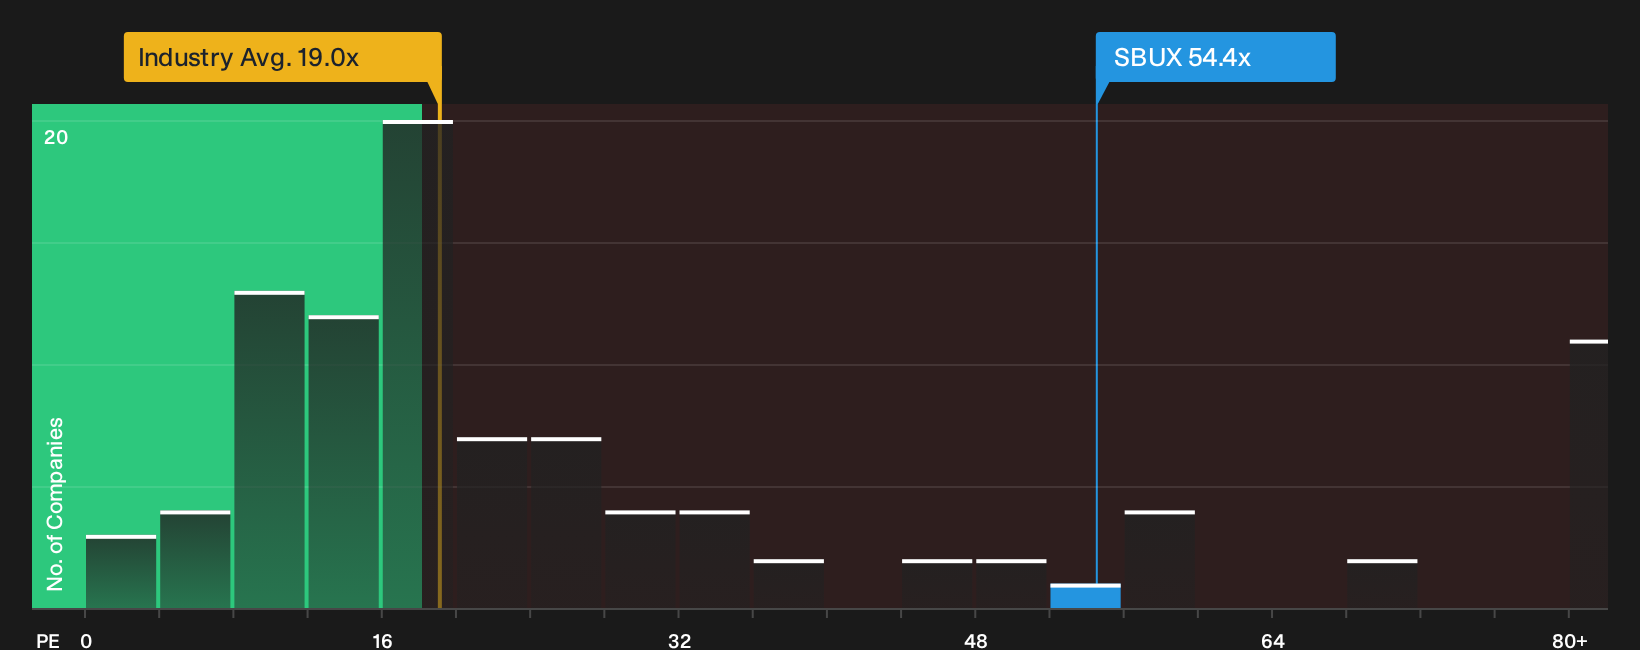
While the most followed Starbucks narrative leans on a fair value of $112.23, the current P/E of 54.4x tells a tougher story. That multiple is higher than the estimated fair ratio of 32.7x, the US Hospitality average of 19x, and a 40.4x peer average. This raises questions about downside risk if sentiment cools.
Investors weighing these signals may want to see what the numbers say about this price in more detail. This is where the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Starbucks story feels split between promise and risk, consider acting while the facts are fresh and evaluate the data yourself using the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Starbucks?
Do not stop at a single ticker. Broader context helps decisions feel calmer and more confident, especially when you compare Starbucks with very different opportunities side by side.
- Spot potential turnarounds early by scanning the 9 elite penny stocks with strong financials that already pair tiny market caps with sturdier looking financials.
- Zero in on quality at a discount by reviewing the 19 high quality undiscovered gems that combine strong fundamentals with relatively low market attention.
- Prioritise sleep-at-night holdings by focusing on the 31 resilient stocks with low risk scores that feature more resilient balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com