
We Think Seascape Energy Asia (LON:SEA) Needs To Drive Business Growth Carefully
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So, the natural question for Seascape Energy Asia (LON:SEA) shareholders is whether they should be concerned by its rate of cash burn. For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
When Might Seascape Energy Asia Run Out Of Money?
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. As at June 2026, Seascape Energy Asia had cash of UK£5.0m and no debt. Importantly, its cash burn was UK£6.4m over the trailing twelve months. Therefore, from June 2026 it had roughly 9 months of cash runway. Notably, analysts forecast that Seascape Energy Asia will break even (at a free cash flow level) in about 3 years. Essentially, that means the company will either reduce its cash burn, or else require more cash. You can see how its cash balance has changed over time in the image below.
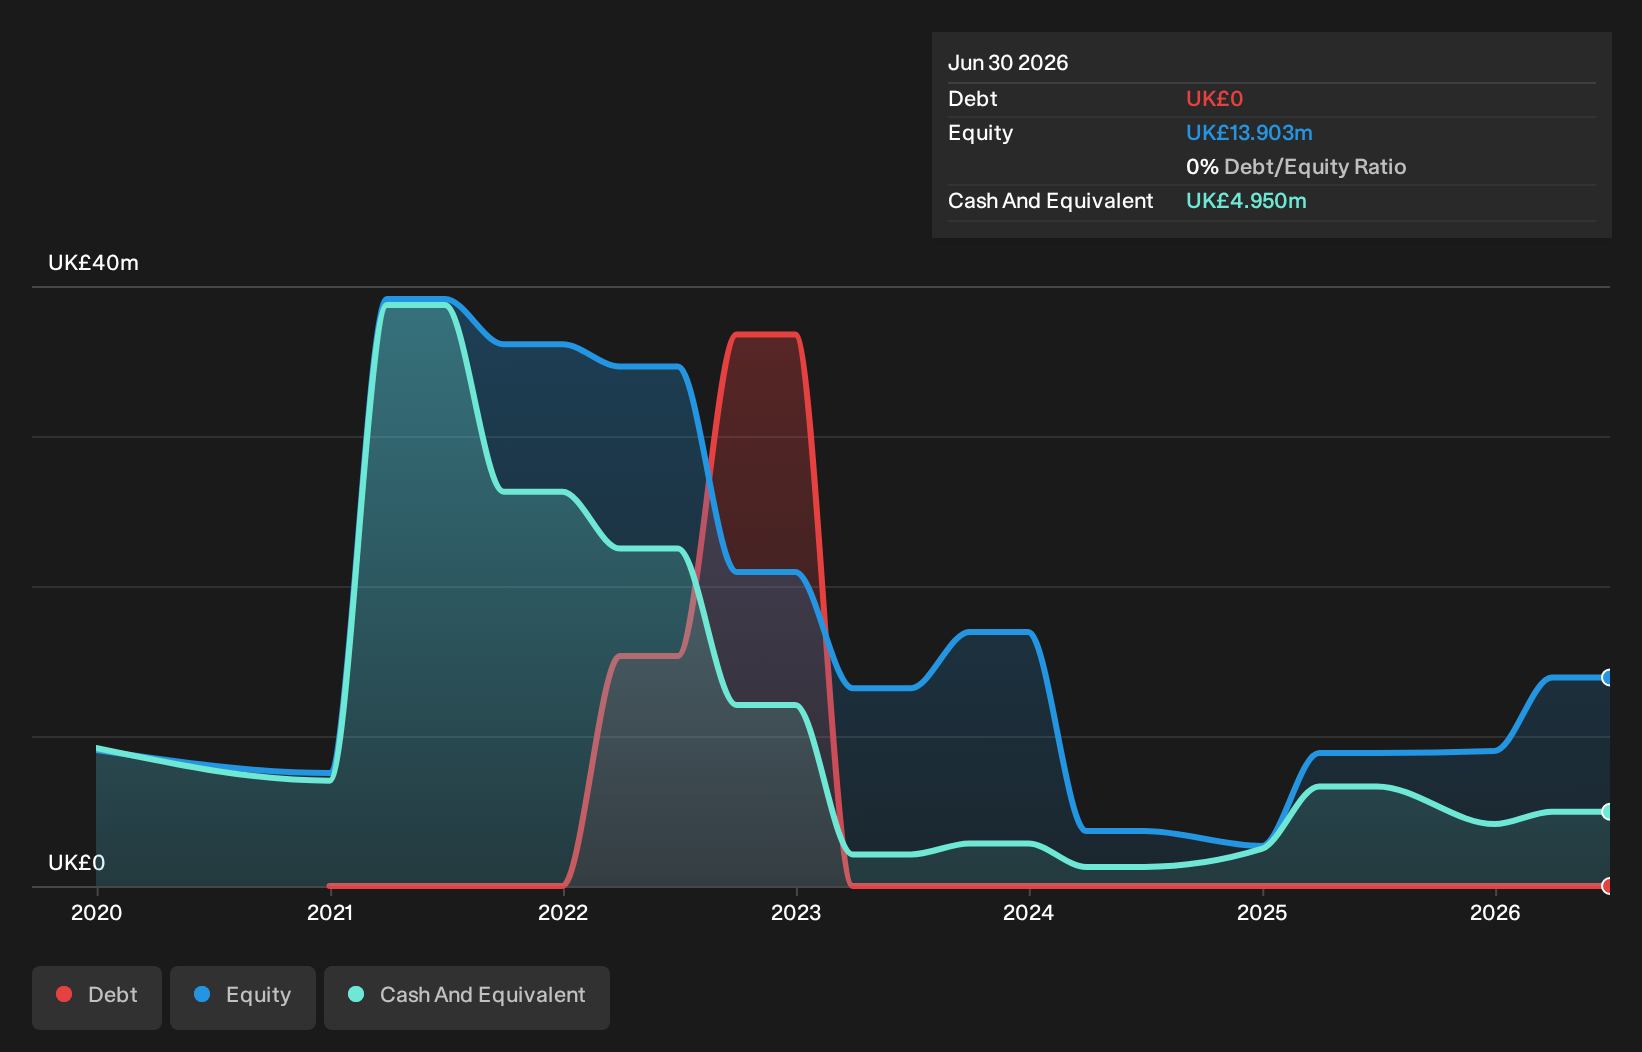
See our latest analysis for Seascape Energy Asia
How Is Seascape Energy Asia's Cash Burn Changing Over Time?
Seascape Energy Asia didn't record any revenue over the last year, indicating that it's an early stage company still developing its business. Nonetheless, we can still examine its cash burn trajectory as part of our assessment of its cash burn situation. With the cash burn rate up 32% in the last year, it seems that the company is ratcheting up investment in the business over time. However, the company's true cash runway will therefore be shorter than suggested above, if spending continues to increase. While the past is always worth studying, it is the future that matters most of all. So you might want to take a peek at how much the company is expected to grow in the next few years.
How Easily Can Seascape Energy Asia Raise Cash?
Given its cash burn trajectory, Seascape Energy Asia shareholders should already be thinking about how easy it might be for it to raise further cash in the future. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. Many companies end up issuing new shares to fund future growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of UK£74m, Seascape Energy Asia's UK£6.4m in cash burn equates to about 8.7% of its market value. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
How Risky Is Seascape Energy Asia's Cash Burn Situation?
Even though its cash runway makes us a little nervous, we are compelled to mention that we thought Seascape Energy Asia's cash burn relative to its market cap was relatively promising. Shareholders can take heart from the fact that analysts are forecasting it will reach breakeven. We don't think its cash burn is particularly problematic, but after considering the range of factors in this article, we do think shareholders should be monitoring how it changes over time. On another note, Seascape Energy Asia has 4 warning signs (and 3 which make us uncomfortable) we think you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.