
Is Hut 8 (HUT) A Bargain On Its New $1.07b Credit Facility?
Why Hut 8’s New Credit Facility Matters For Investors
Hut 8 (HUT) just closed a new US$1.07b four year senior secured revolving credit facility, a financing move that directly affects liquidity, capital access, and how investors think about the stock’s balance sheet.
The new facility lands after a volatile stretch for Hut 8, where the share price is up 74.82% year to date but the past quarter’s share price return declined 7.73%. In the short term, the 1 day share price return of 3.79% and 30 day share price return of 11.09% hint at improving momentum. The 1 year total shareholder return of 123.52% shows how strongly longer term holders have been rewarded despite recent swings.
Scan hand picked AI infrastructure opportunities alongside Hut 8’s new credit facility story by reviewing the 90 AI infrastructure stocks that are already building out power and compute at scale.
Given the new US$1.07b credit line, the recent share price swing, and a loss making income statement, does Hut 8 still offer an attractive enough risk reward for buyers at US$89.63 to care?
Most Popular Narrative: 43% Undervalued
The most followed narrative on Hut 8 pegs fair value at $157.09 against a last close of $89.63. The gap it highlights is wide and built on explicit revenue, margin and discount rate assumptions rather than vague optimism.
The Power First strategy, featuring sizable pipeline origination (10.8 GW under diligence, 3.1 GW under exclusivity) and dual-purpose sites for both Bitcoin mining and AI compute, provides scalability and flexibility to benefit from rising institutional adoption of digital assets and accelerating demand for clean energy powered blockchain infrastructure, bolstering future revenue and earnings growth. Strategic structuring and spin-out of American Bitcoin creates dual value streams, recurring infrastructure like returns for Hut 8 and scalable exposure to Bitcoin price appreciation, allowing for capital efficient growth and the potential to leverage a liquid minority stake for financing or fund further platform expansion positively impacting long-term earnings power.
See why 82 investors see Hut 8 as 43% undervalued.
Result: Fair Value of $157.09 (UNDERVALUED)
Still, Hut 8’s reliance on Bitcoin linked activity and capital intensive AI and data center build outs could quickly pressure cash flows if project execution slips.
Find out about the key risks to this Hut 8 narrative.
Another View On Hut 8’s Valuation
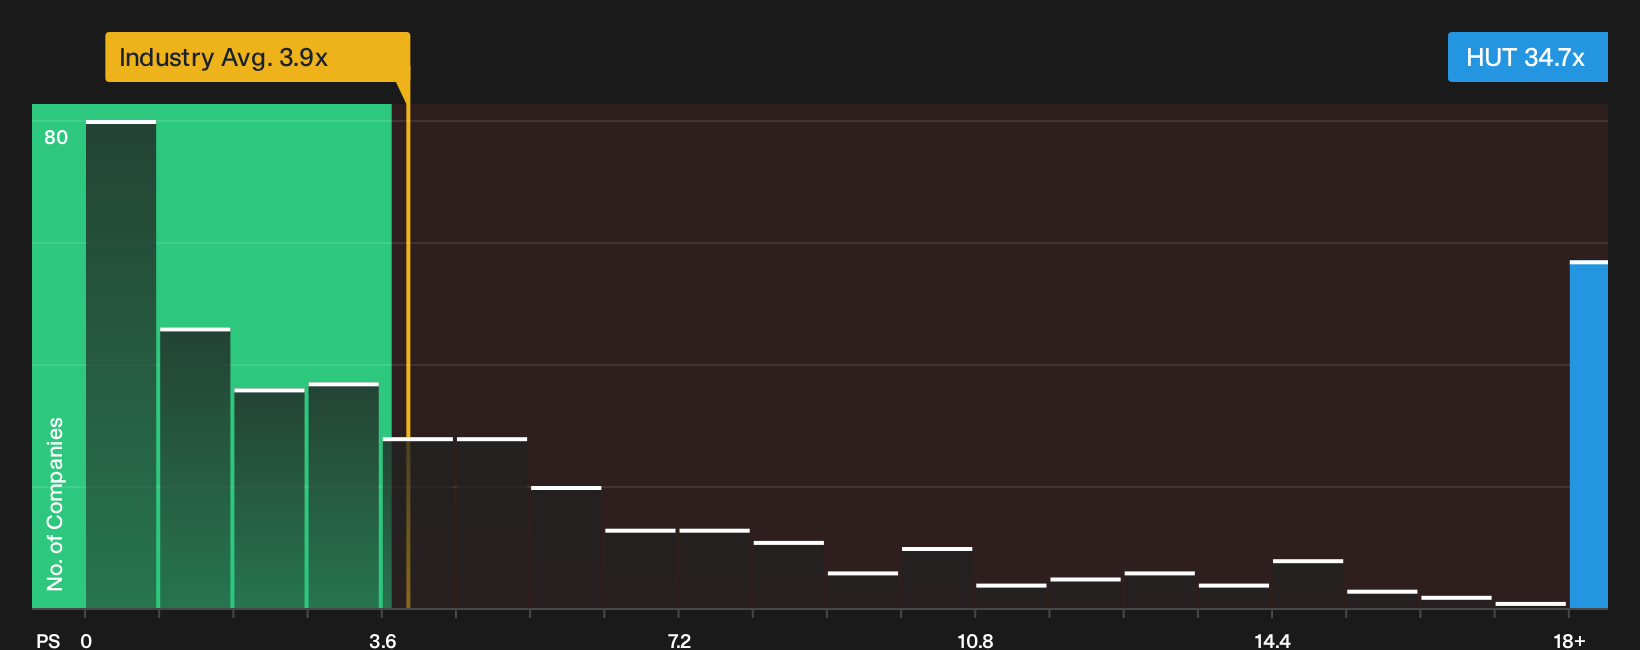
Analyst narratives lean on a fair value of $157.09, yet Hut 8 trades on a very rich P/S of 34.7x versus 1.4x for peers and 3.9x for the US Software sector. The fair ratio of 13.7x suggests the market could move closer to that level. Is that air gap risk or opportunity for you?
Before leaning too heavily on a single price target, it helps to sanity check this P/S premium against the detailed valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early setup. Either way, move quickly to review the figures on Hut 8, weigh both sides of the story, and ground your own stance in the 1 key reward and 3 important warning signs.
Want more ideas beyond Hut 8?
If Hut 8 has your attention, do not stop here. Broader context sharpens judgment, and fresh watchlist candidates can help you stay one step ahead.
- Target potential mispricing by scanning companies that score well on quality checks and trade below assessed value using the 31 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (26 results) that can better withstand shocks and still fund growth.
- Spot lesser known opportunities early by working through 19 high quality undiscovered gems with strong fundamentals before they draw wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com