
Is AI Chip Spending Altering The Investment Case For Nova Stock (NVMI)?
- Recent coverage highlighted Nova Ltd. as a semiconductor metrology and process control supplier that could potentially benefit from rising AI infrastructure capital spending as chip designs become more complex.
- The interesting angle is that AI-driven device complexity may increase reliance on Nova’s inspection and measurement tools, which would tie its demand more closely to long-term fabrication investment decisions.
- We will now look at how this AI-driven capital spending spotlight on Nova may influence the broader investment narrative around the business.
Scan how Nova fits into the AI hardware build out, then size up other potential beneficiaries through our hand picked 90 AI infrastructure stocks reshaping the semiconductor supply chain.
What Is Nova's Investment Narrative?
To own Nova, you have to buy into a fairly simple idea. As chip designs tied to AI workloads become harder to manufacture, fabs lean more on precise metrology and process control equipment. The recent focus on AI infrastructure spend fits that thesis and helps keep Nova in the conversation when foundries plan new capacity. In the short term, the key swing factors remain order timing, how quickly customers qualify newer tools, and whether pricing holds up against peers in a still capital intensive equipment cycle.
On the numbers already in hand, Nova is a profitable specialist with high quality earnings, a P/E of 46.6x that screens below both peer and broader semiconductor averages, and analyst forecasts that point to faster earnings growth than the wider US market. Revenue is projected to rise 18.6% a year, which is quicker than the market but not especially rapid for equipment, and recent share price performance has lagged the US semiconductor group even with a 1 year total return of 23%. The AI capex tailwind and analyst optimism help the story, yet the business still has to prove it can sustain that growth rate through a full equipment cycle.
That said, before leaning too hard on the AI metrology story, there is an uncomfortable wrinkle in the recent insider trading pattern that ...
There's only one way to know the right time to buy, sell or hold Nova. Head to Simply Wall St's company report for the latest analysis of Nova's Fair Value.
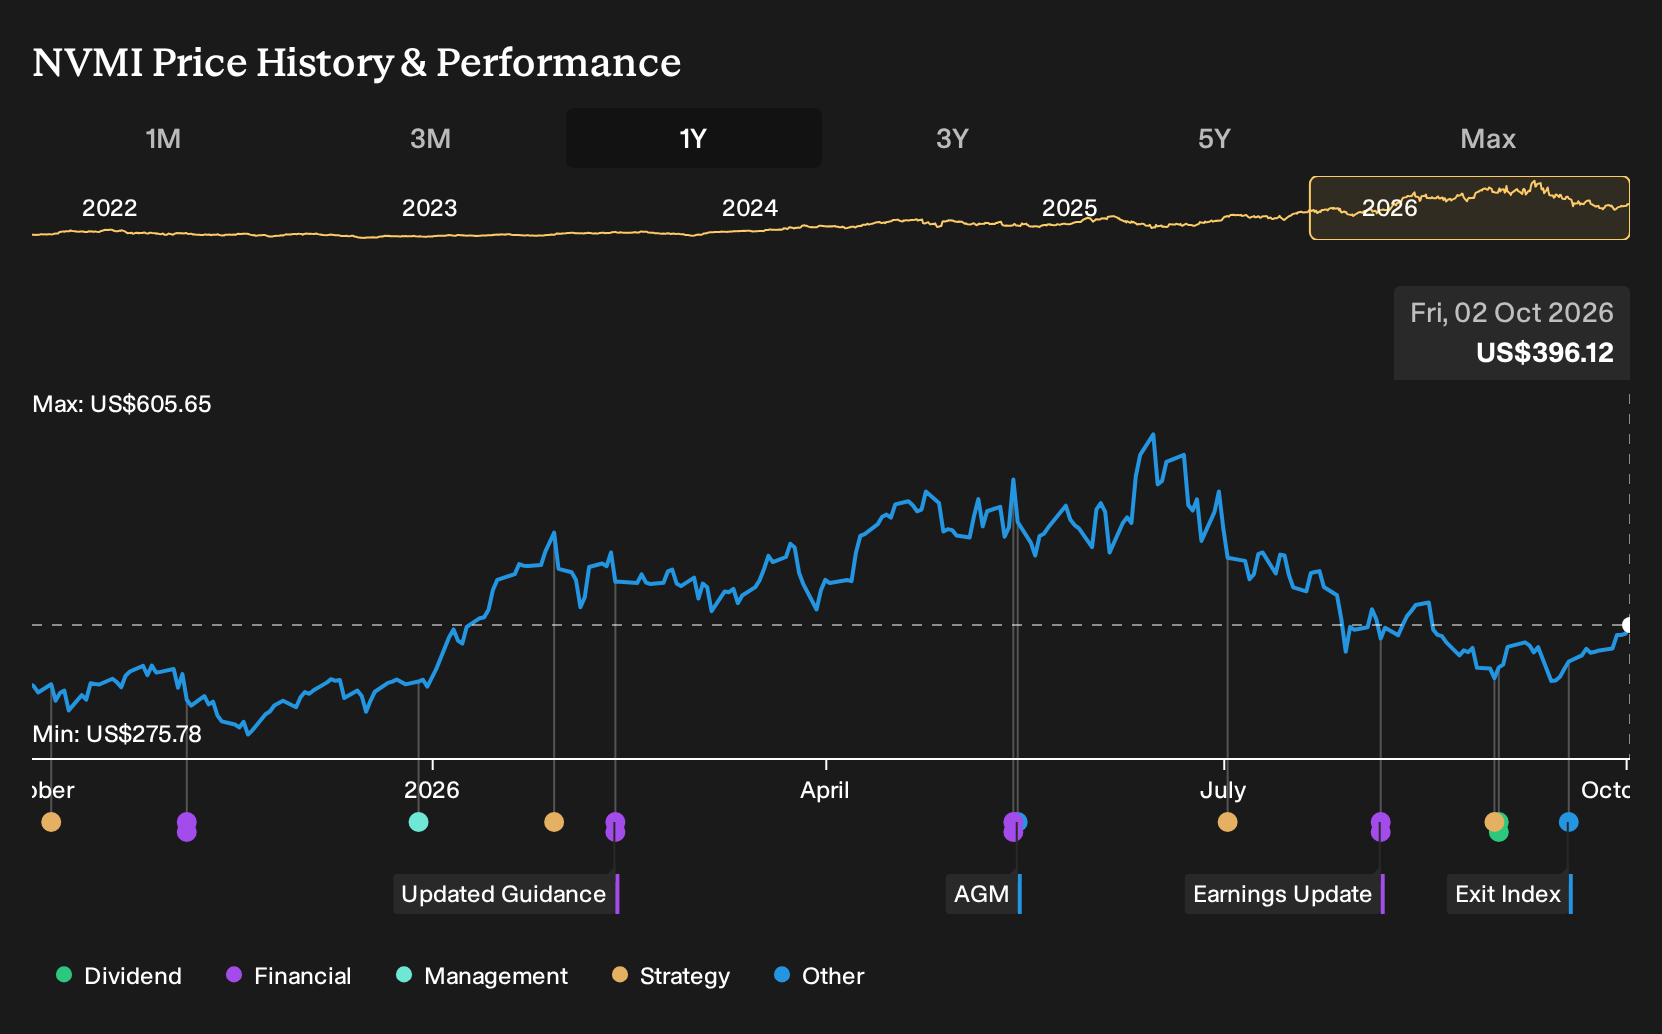
Exploring Other Perspectives
For Nova, the most optimistic twist comes from analysts who lean into AI driven metrology demand as a powerful catalyst. That group was modeling revenue climbing about 26% a year and earnings reaching roughly US$567.7 million by 2029, before this AI capex news. You can use that gap in expectations to explore how your own view might shift.
Explore 3 other Nova fair value estimates, including one that suggests as much as 34% potential increase from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nova research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nova. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Nova's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nova?
If Nova has sharpened your view on how AI hardware spend can ripple through suppliers, it can help to line it up against a wider watchlist using the Simply Wall St Screener. Comparing different types of opportunities side by side lets you test your thesis, pressure check expectations, and find businesses that better match your risk and return preferences.
- If you want income to play a bigger role in your portfolio, scan for reliable cash generators through our 7 dividend fortresses that focus on higher yielding payers with staying power.
- If valuation discipline is your priority, weigh Nova against companies flagged in the 31 high quality undervalued stocks to see where solid fundamentals and pricing potentially look more compelling.
- If capital preservation matters most to you, start with the 31 resilient stocks with low risk scores and filter for resilient businesses that score well on stability and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com