
Centrus Energy (LEU) Stock Looks Overvalued Even After Recent Wins
Centrus Energy has seen its share price fall sharply over the past year, even after a very large gain over the past five years. Those swings put the focus squarely on a simple question for investors who follow Centrus Energy: whether the current valuation is supported by the company’s earnings power.
- Over the past 5 years, Centrus Energy has delivered a total return of about 2.6x, which raises the question of how much of that move can be traced back to its earnings profile.
- Recent operational momentum and commercial wins in its enrichment business may support expectations for future profit streams, which matters directly for how the earnings multiple stacks up against the Fair Ratio benchmark.
- The analysts covering Centrus Energy have run their own numbers. See what analysts think Centrus Energy's shares could be worth.
The issue now is whether today's Centrus Energy share price is justified by the earnings it generates relative to this Fair Ratio benchmark.
To see how Centrus Energy compares with other nuclear infrastructure opportunities built around the same theme, it can help to review 19 nuclear energy infrastructure stocks.
Does Centrus Energy Look Pricey on Earnings?
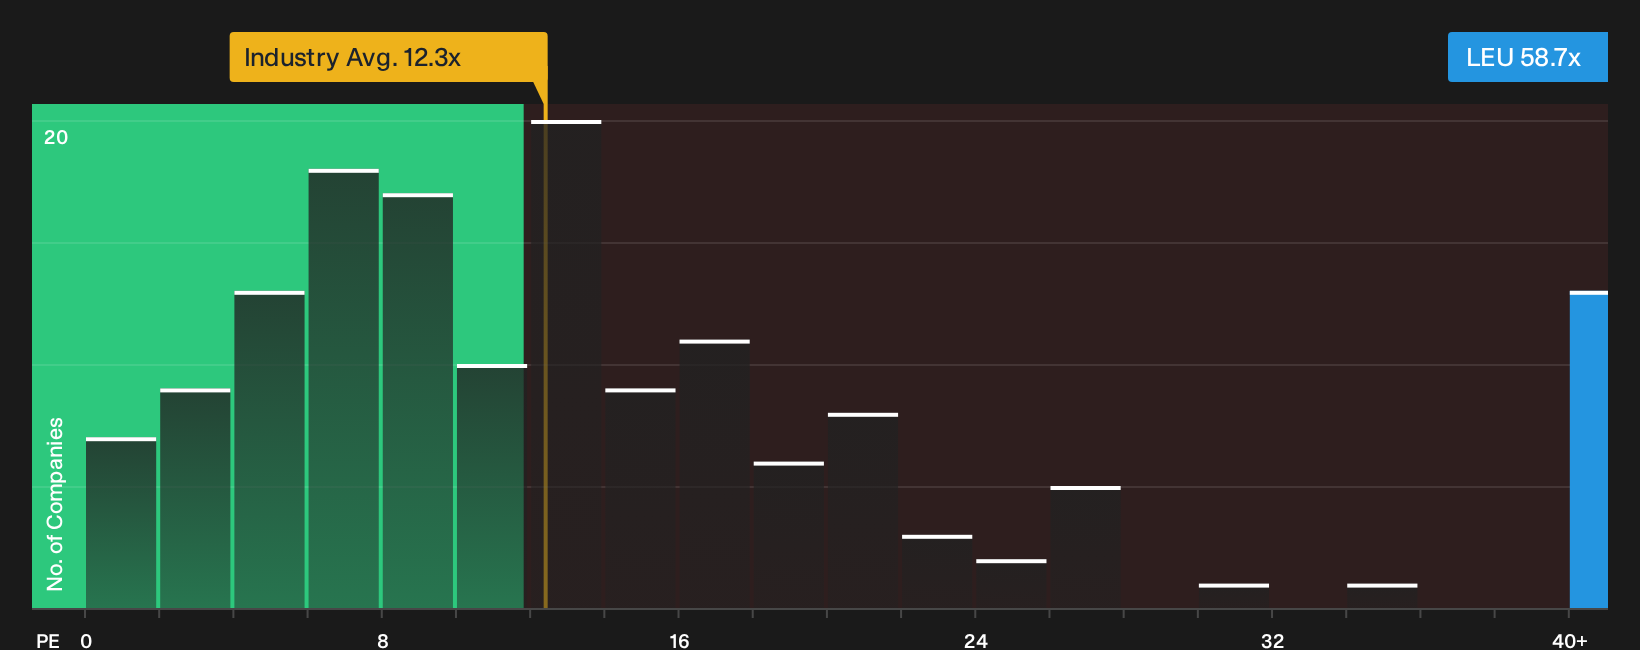
The P/E ratio is a useful lens for Centrus Energy because earnings are a core focus for investors trying to size up its enrichment franchise against the current share price. On this measure, the stock trades at about 58.7x earnings, compared with an Oil and Gas sector average of roughly 12.3x and a peer group closer to 21.4x. That is a steep premium to both the wider industry and more direct comparables.
Because the Fair Ratio framework adjusts for factors like profitability, growth profile, size and risk, it implies a much lower P/E than where Centrus Energy changes hands today. The gap is wide enough that the model is treating recent losses, cash flow pressure or business risk as a serious constraint. As a result, the outcome reads more as a warning flag that the shares screen very expensive on this earnings lens rather than as a precise target. Despite Q2 revenue of US$176.1m and reported commercial wins, the current multiple still prices Centrus Energy well above both its sector and peer benchmarks on this methodology. Explore the numbers behind Centrus Energy's P/E valuation.
The Centrus Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Centrus Energy pick up where this valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to materialise for the stock to be worth materially more or less than today's price on the Community page. Each scenario ties a fair value estimate to a clear storyline about Centrus Energy's potential catalysts and key risks, so you can track over time which version of events appears to be unfolding.
One of the top community narratives on Centrus Energy: 27% undervalued
"Centrus Energy (LEU) offers the most direct public-market exposure to U.S. HALEU production, a critical bottleneck for advanced nuclear deployment..."
Discover why this Narrative puts Centrus Energy at 27% undervalued.
Before acting on Centrus Energy’s valuation, there is one more piece to examine
The share price debate only tells part of the story. The people steering Centrus Energy and the way their pay is structured can pull returns toward or away from shareholders over time. See who runs Centrus Energy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com