
Edgewise Therapeutics (EWTX) Could Be 20% Undervalued After Its EDG 7500 Investor Call
Edgewise Therapeutics (EWTX) is holding a special call on September 22, 2026, to walk investors through the differentiated mechanism of action behind its cardiac sarcomere modulator, EDG-7500, for hypertrophic cardiomyopathy.
Recent trading suggests interest is picking up again in Edgewise Therapeutics, with a 1-day share price return of 2.27% and 7-day share price return of 5.24% ahead of the EDG-7500 call, even though the 30-day share price return declined 1.38%.
That short-term momentum sits on top of a very strong 1-year total shareholder return of 164.54% and a 3-year total shareholder return of roughly 5x. This indicates that recent moves are being judged against a much larger rerating story rather than a single event.
Scan beyond Edgewise Therapeutics and line up other potential breakout biotech stories with the hand picked 19 high quality undiscovered gems that investors are starting to notice.
Edgewise Therapeutics now trades at about a 27% discount to the current analyst target. The real puzzle is where fair value lands once you compare that gap with the full range of estimates.
Most Popular Narrative: 19.9% Undervalued
On the most followed view, Edgewise Therapeutics screens as materially below its narrative fair value of $51.69 compared with the last close at $41.40. This view places substantial emphasis on outcomes in the late stage cardiac pipeline.
Completion of the sale of sevasemten and the muscular dystrophy platform to Servier for US$1.55b upfront plus up to US$1.1b in milestones frees Edgewise Therapeutics to concentrate capital and management attention on cardiovascular assets. This could influence future revenue growth and reduce funding pressure on earnings.
See why 1 investors see Edgewise Therapeutics as 20% undervalued.
Result: Fair Value of $51.69 (UNDERVALUED)
Still, the Edgewise Therapeutics story hinges on EDG-7500 execution and the timing of cardiovascular approvals, while ongoing losses and no current revenue keep funding risk in play.
Find out about the key risks to this Edgewise Therapeutics narrative.
Another View: Edgewise Therapeutics On Rich P/B Terms
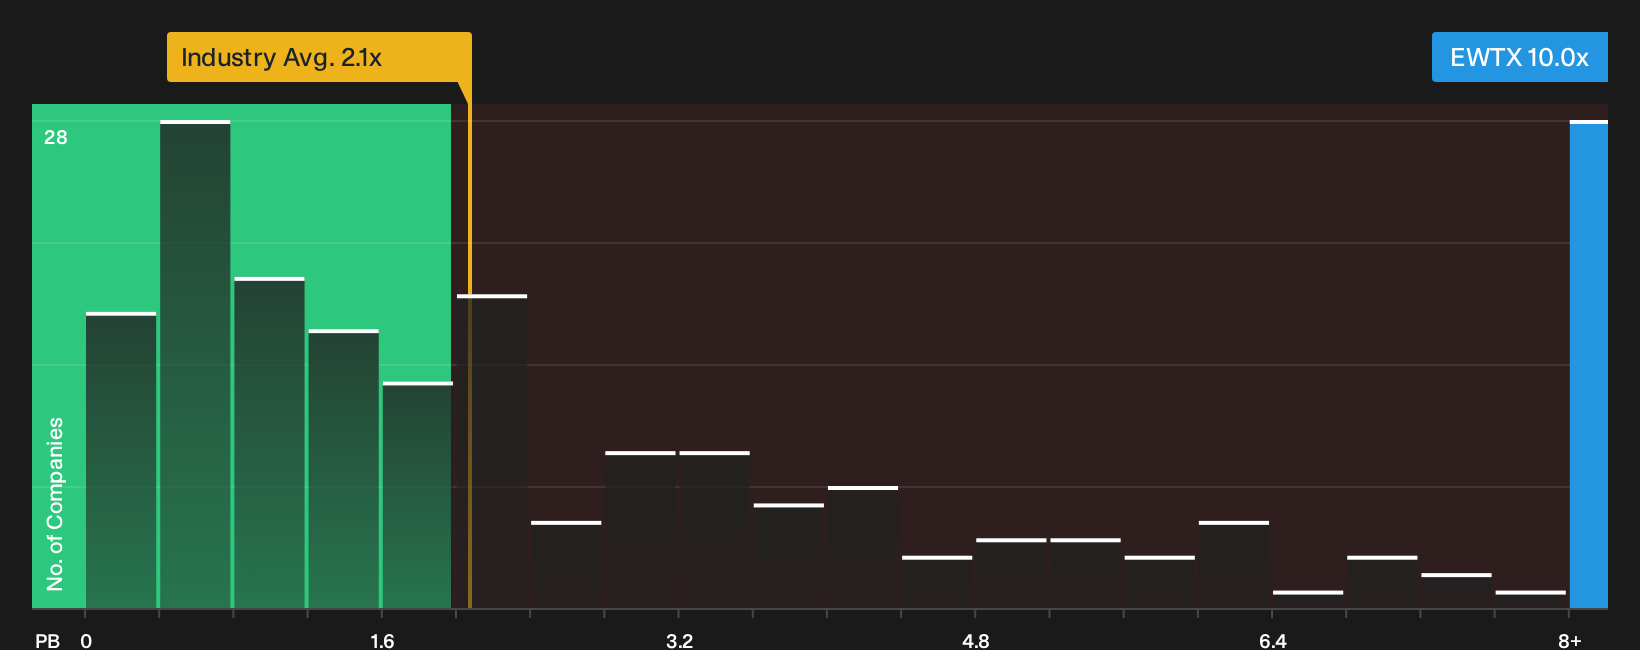
Look at Edgewise Therapeutics through its P/B and the story changes. The stock trades around 10x book value, compared with roughly 2x for the wider US Pharmaceuticals group and about 7.4x for peers. That is a steep premium. It raises a simple question for investors: How much execution risk are you willing to pay up for?
To unpack what that premium could mean for future upside or downside, it helps to see how the current price stacks up against the rest of the sector in one place, then compare it with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages so far on Edgewise Therapeutics, with strong past returns sitting beside clear open questions, make this a moment to move from headlines to hard data. To stress test the bullish and cautious angles before the next piece of news lands, start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Edgewise Therapeutics?
Do not stop with a single ticker when you can quickly scan fresh ideas that fit your preferred mix of risk, return potential, and financial strength.
- Target potential mispricings by reviewing companies flagged as 31 high quality undervalued stocks that may align with your return expectations.
- Prioritize resilience and sleep better at night by using a 31 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier profiles.
- Build a sturdier foundation for your portfolio by using a list of solid balance sheet and fundamentals (26 results) that surfaces businesses with stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com