
Innospec (IOSP) Could Be 2% Undervalued Following Its Margin Improvement Story
Innospec (IOSP) has drawn fresh attention after recent share price moves, with the stock last closing at $97.41. Investors are weighing that market reaction against the specialty chemicals producer’s current financial profile.
Recent trading has been choppy for Innospec, with a 2.35% 1 day share price gain sitting against a 1.33% 7 day share price decline. However, a 27.70% year to date share price return and 26.63% 1 year total shareholder return indicate that momentum has been building over a longer stretch.
Scan beyond Innospec and evaluate other specialty and materials players showing similar momentum in our hand picked 31 high quality undervalued stocks.
Bulls see Innospec’s recent move as the market waking up to a solid specialty chemicals profile, while bears see stretched optimism crowding into a slower compounder. Which side do the valuation markers actually support next?
Most Popular Narrative: 2% Undervalued
Innospec’s most followed valuation storyline puts fair value at $99.33, only slightly above the last close at $97.41. This keeps the focus squarely on what might drive that gap to close.
The company's ongoing margin improvement initiatives, disciplined pricing strategies, and product mix optimization, particularly in Fuel Specialties and Performance Chemicals, are expected to boost gross margin and earnings as operational execution improves through the second half and into 2026. Innospec's strong cash position and lack of debt provide significant flexibility for organic investments and opportunistic M&A, aligning with the global trend of increased specialty chemicals demand for emerging wellness, personal care, and advanced materials markets, which could drive outsized revenue and net income growth over the long term.
See why 3 investors see Innospec as 2% undervalued.
Result: Fair Value of $99.33 (UNDERVALUED)
Still, the bullish Innospec story can break if raw material cost swings squeeze margins for longer than expected or if weakness in Oilfield Services drags on group earnings.
Find out about the key risks to this Innospec narrative.
Another View On Innospec Using Earnings Multiples
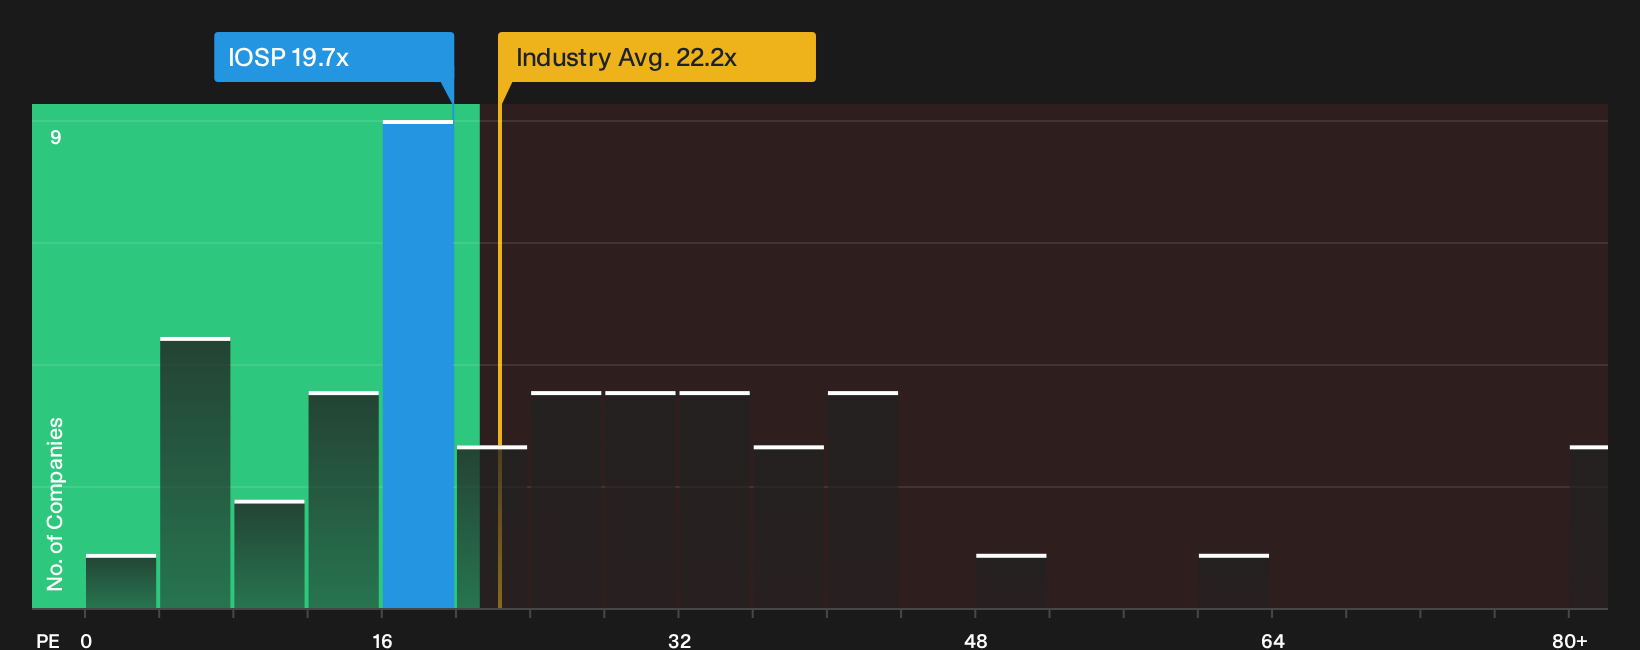
Innospec screens as undervalued on fair value estimates, yet its current P/E of 19.7x sits above a fair ratio of 17.2x. It is below the US Chemicals industry on 21.1x and well under peers at 45.8x. Is the stock priced for comfort rather than clear upside?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Innospec so far. If you want to move quickly and decide where you stand, weigh both sides through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Innospec?
If you stop with Innospec, you risk missing other stocks that better match your goals, so use the tools available and widen your opportunity set.
- Target stronger income streams by scanning companies that resemble steady payers and potential yield opportunities through 7 dividend fortresses.
- Hunt for quality at a discount by lining up financially robust businesses using the 19 high quality undiscovered gems.
- Prioritise resilience in tougher markets and filter for companies with sturdier finances through the list of solid balance sheet and fundamentals (26 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com