
How Earnings Beat Will Impact SM Energy Stock Investors
- SM Energy reported quarterly results that exceeded consensus revenue and earnings expectations, with the current quarter forecast at $1.81 per share, which Zacks notes would be 36.1% higher than the prior year period.
- The business continues to lean on efficiency gains and disciplined capital use, which supports expectations for near term earnings growth despite commodity price swings.
- We will examine how SM Energy's investment narrative around efficiency, balance sheet discipline, and drilling depth is affected by this earnings outperformance.
Compare SM Energy's earnings driven story with other potential underpriced operators by scanning our hand picked list of 31 high quality undervalued stocks that also pair cash generation with disciplined balance sheets.
SM Energy Investment Narrative Recap
To own SM Energy, you need to be comfortable with a focused shale portfolio and a business model that depends on steady drilling, efficiency gains, and disciplined spending. The recent revenue and earnings beat supports that story in the near term, because it points to solid execution rather than a one off swing.
The key short term catalyst is whether SM Energy can keep converting this operating efficiency into consistent cash generation while managing high decline rates. The main risk sits in basin concentration and Uinta logistics, where any marketing or takeaway issues could quickly pressure realized prices and margins.
The latest quarterly report is the announcement that matters most here. SM Energy delivered results ahead of consensus on both revenue and earnings and is currently expected to earn US$1.81 per share this quarter, which Zacks notes would be 36.1% higher than the same period a year ago.
That type of performance ties directly into the core catalysts investors are watching. Continued operational improvements and disciplined capital use can support resilient free cash flow, but the value of this beat still depends on how repeatable these well results are across the Uinta and Midland inventory and whether the company can sustain margins without materially higher spending.
SM Energy's current narrative points to forecast revenues of US$7.4b and projected earnings of US$1.8b by 2029, based on analysts expecting revenue to grow 14.3% per year and earnings to rise by US$0.8b from US$1.0b today.
Uncover why SM Energy's fair value indicates a 23% potential upside to its current price before the discount starts to close.
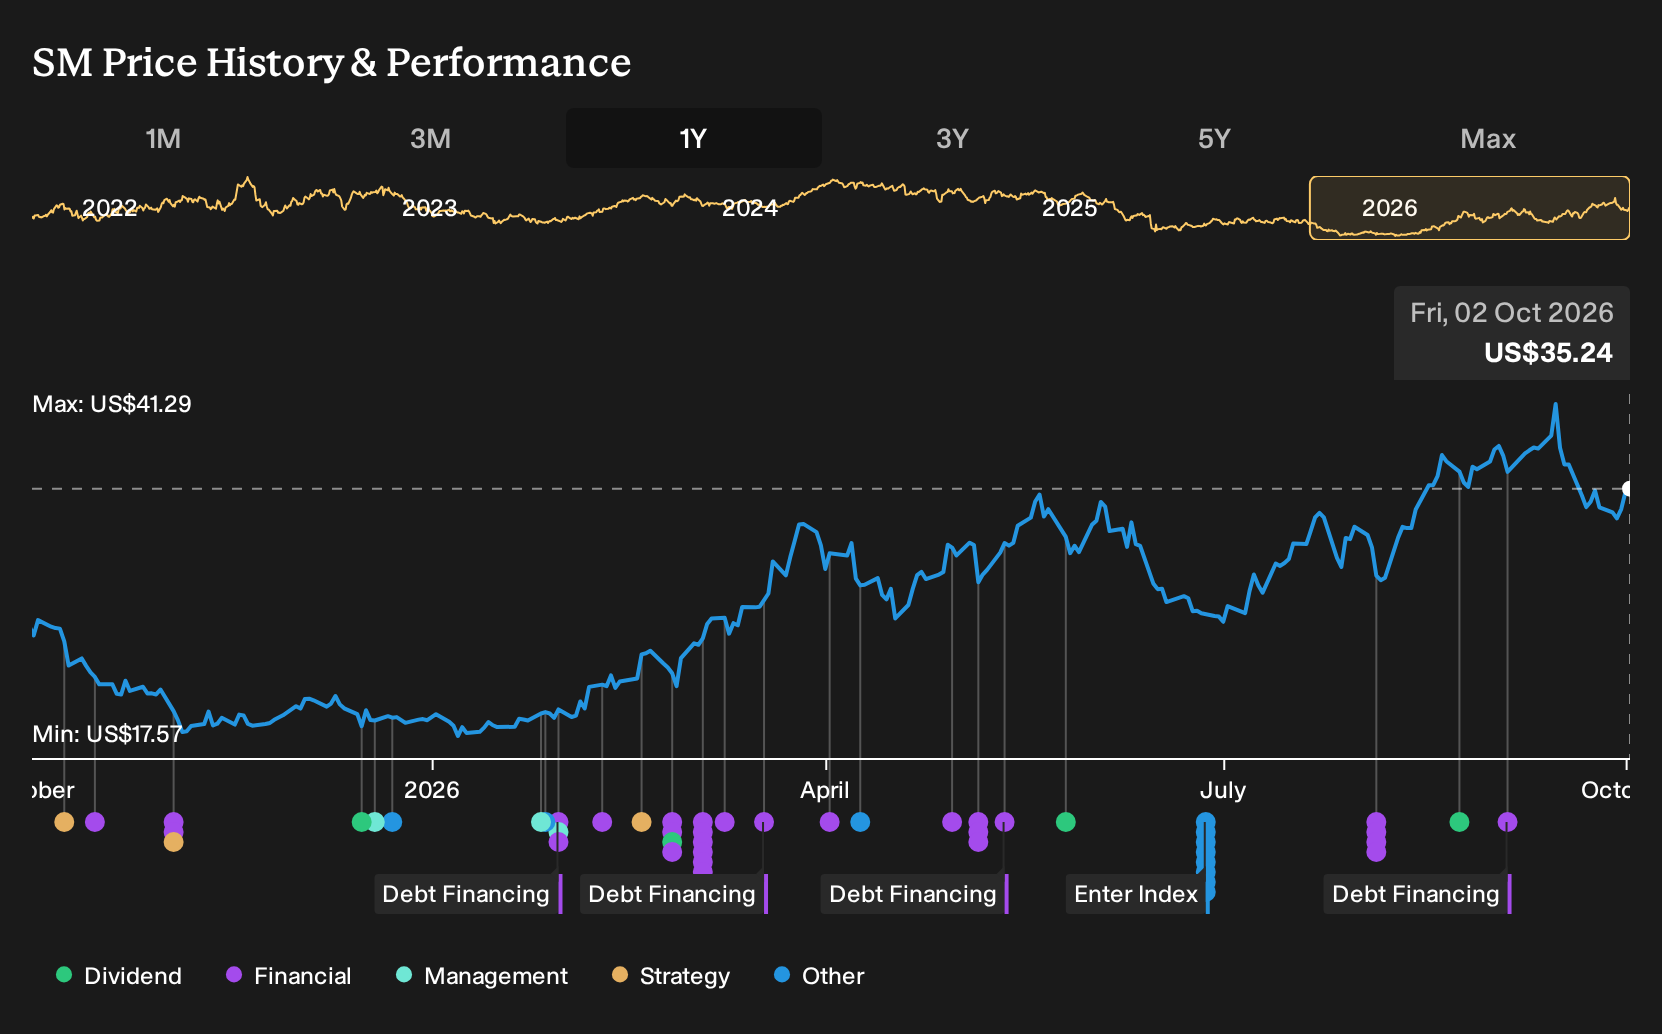
Exploring Other Perspectives
For SM Energy, the bullish twist in the story comes from Uinta well outperformance. The most optimistic analysts were already penciling in revenue of about US$8.5b and earnings of US$2.3b by 2029 before this earnings beat. You can treat this quarter as a fresh data point that might shift those views, in either direction.
Explore 5 other SM Energy fair value estimates, including one that suggests as much as 273% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SM Energy research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SM Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SM Energy's overall financial health at a glance.
Looking For More Ideas Beyond SM Energy?
If the SM Energy story has sharpened your view on efficiency, balance sheets and drilling depth, it can help to line that up against other opportunities. The Simply Wall St Screener lets you filter for the traits that matter most to you, so you can quickly build a watchlist that matches your risk tolerance and return goals.
- For investors who want potential mispricing combined with quality metrics, scan through a curated set of 31 high quality undervalued stocks that pair solid fundamentals with attractive valuation markers.
- If capital preservation ranks high on your priority list, narrow the field to a 31 resilient stocks with low risk scores that aim to keep volatility and financial red flags in check.
- When you are hunting for less crowded ideas with robust business profiles, sift through a focused pool of 19 high quality undiscovered gems that have strong fundamentals but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com