
Zai Lab (ZLAB) Puts Zoci Data In Focus Following ESMO Reveal As Valuation Debate Builds
Clinical data catalyst for Zai Lab
Zai Lab (ZLAB) has put fresh attention on its oncology pipeline after scheduling the first global data readout for zoci in extensive-stage small cell lung cancer at the 2026 ESMO Congress.
Recent trading has been choppy. Zai Lab’s share price is up 40.39% year to date and 27.25% over 90 days, yet the 1-year total shareholder return is down 27.91%. This suggests that enthusiasm around catalysts like the upcoming zoci data is rebuilding after a tough stretch.
Compare this Zai Lab catalyst with a curated set of oncology and biotech peers by scanning the 19 high quality undiscovered gems that could be pricing in very different expectations around upcoming data readouts.
Zai Lab now has a growing portfolio, fresh clinical catalysts and a share price that has rebounded hard this year. Is that combination still mispriced or already fully reflected in today’s US$24.33 quote?
Most Popular Narrative: 26.9% Undervalued
Against Zai Lab’s last close at $24.33, the widely followed narrative pegs fair value at $33.30, implying a sizable valuation gap that investors are using to frame the upcoming zoci data and broader pipeline news.
Multiple high-potential product launches and label expansions over the next 12-18 months (including VYVGART, bemarituzumab, KarXT, TIVDAK, Tumor Treating Fields), combined with a deep pipeline in oncology and immunology, are expected to significantly increase Zai Lab's addressable market and diversify revenue streams, supporting both top-line growth and future earnings.
See why 12 investors see Zai Lab as 27% undervalued.
Result: Fair Value of $33.30 (UNDERVALUED)
Still, the bullish Zai Lab narrative leans heavily on in licensed assets and assumes smooth NRDL pricing, and setbacks on either front could quickly challenge that 26.9% discount story.
Find out about the key risks to this Zai Lab narrative.
Another View: Zai Lab Through The P/S Lens
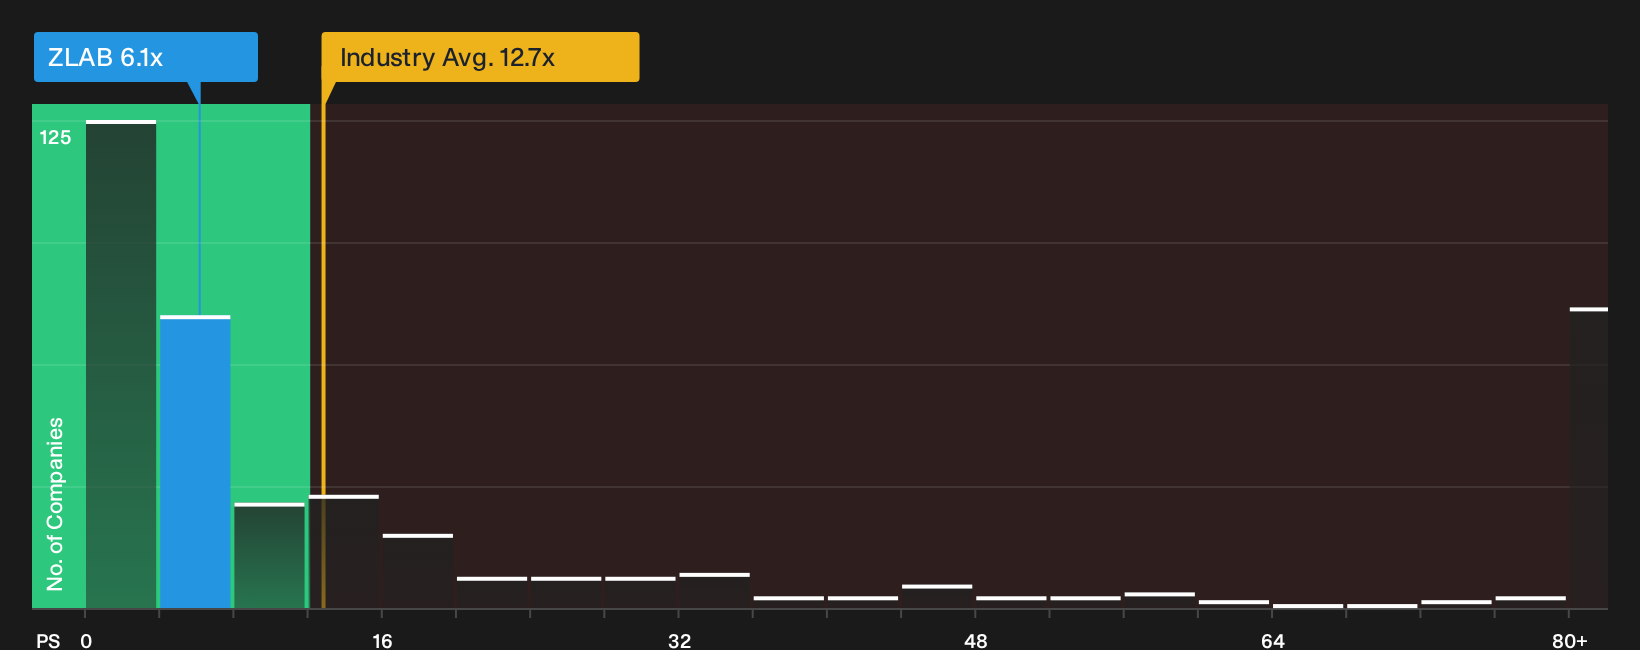
The SWS DCF model points to Zai Lab trading well below an estimated future cash flow value of $79.32, yet the current P/S of 6.1x is higher than a fair ratio of 3.4x and slightly above close peers at 6x. Is the discount a genuine opportunity or just extra risk?
To see how the market ratio story lines up with detailed valuation work, take a look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Zai Lab so far. If you want your own conviction rather than someone else’s headline, stress test the full picture through 3 key rewards and 1 important warning sign.
Looking for more Zai Lab sized ideas?
If you only stop with Zai Lab, you miss plenty of other setups that could fit your risk appetite and return targets just as well.
- Target potential bargains by scanning a curated pool of resilient opportunities through 31 high quality undervalued stocks.
- Prioritize balance sheet strength by reviewing the list of solid balance sheet and fundamentals (26 results) that helps you focus on financial resilience first.
- Dial down volatility risk by using the 31 resilient stocks with low risk scores to surface candidates with more defensive profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com