
Is Hawaiian Electric Industries (HE) Cheap Following New Wildfire Liability Relief?
Hawaiian Electric Industries (HE) has drawn fresh attention after a sharp pullback, with the stock down about 19% over the past month and roughly 35% over the past 3 months.
For Hawaiian Electric Industries, the recent slide builds on a longer stretch of weakness, with the share price return down over the past year and multi year total shareholder returns also negative. This signals fading momentum as investors reassess both growth prospects and risk.
Compare Hawaiian Electric Industries' recent slide with other utilities under pressure and find which ones pass a quality filter in our curated list of list of solid balance sheet and fundamentals (26 results).
Bulls see Hawaiian Electric Industries as punished too far for recent setbacks, while bears point to years of weak total returns. Which story fits the current valuation will hinge on what the numbers say next.
Most Popular Narrative: 2% Undervalued
On the latest narrative, Hawaiian Electric Industries screens only slightly below its estimated fair value of $9.06 against a last close of $8.90. The small gap puts more weight on how investors view risk, regulation and wildfire exposure rather than on simple momentum.
Recent Hawaii legislation enabling wildfire liability caps, state funding for settlements, and securitization of wildfire safety investments significantly reduces legal and financial risk exposure while supporting large-scale infrastructure upgrades. This is likely to stabilize earnings and improve net margins.
See why 16 investors see Hawaiian Electric Industries as 2% undervalued.
Result: Fair Value of $9.06 (UNDERVALUED)
Still, wildfire litigation and the need to fund large resilience projects could continue to put pressure on Hawaiian Electric Industries' costs and financial flexibility.
Find out about the key risks to this Hawaiian Electric Industries narrative.
Another View on Hawaiian Electric Industries' Price Tag
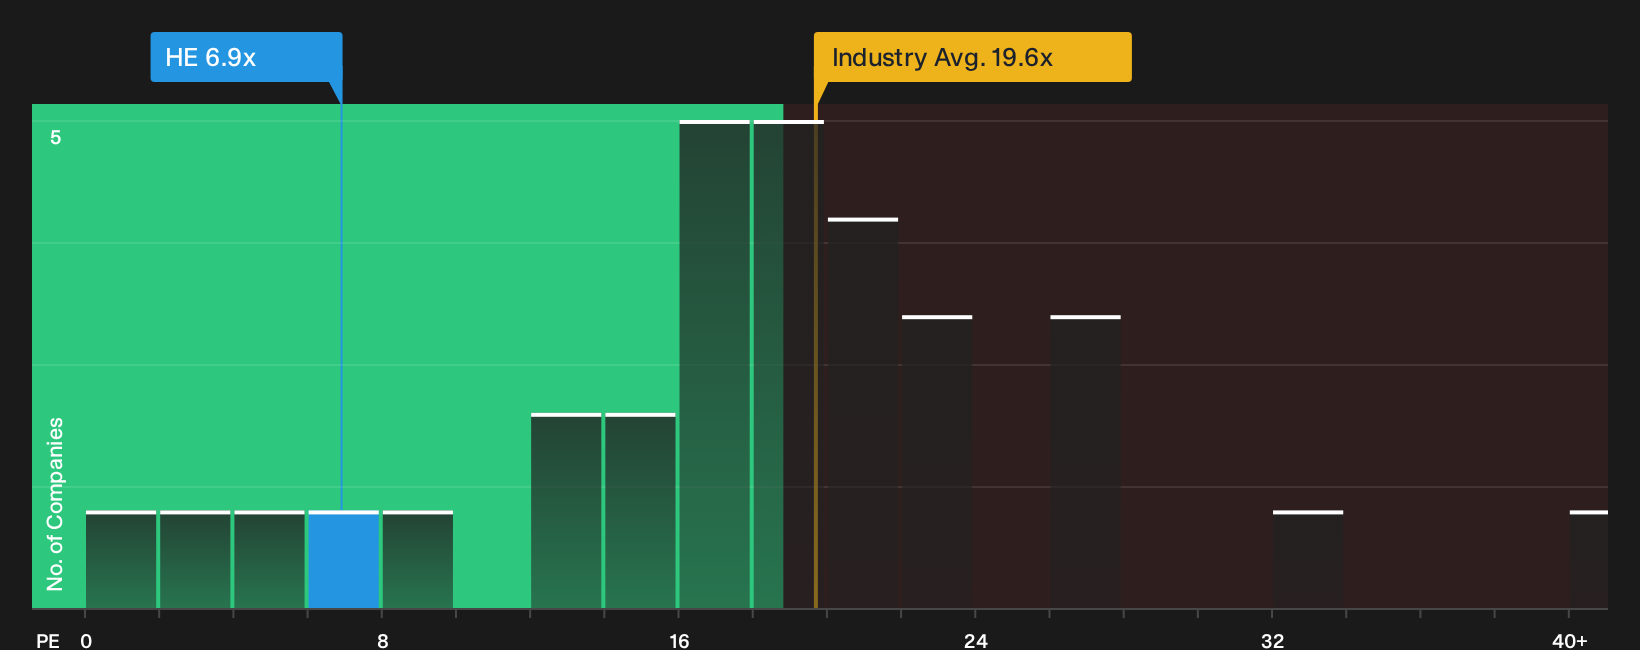
On simple earnings multiples, Hawaiian Electric Industries screens as inexpensive. The stock trades on a P/E of 6.9x, compared with 19.6x for the US Electric Utilities group and 22.6x for peers, while the fair ratio estimate sits at 16.4x.
If the market ever drifted closer to that fair ratio, the valuation gap would close quickly. The question is whether current risks keep the discount locked in or whether sentiment eventually shifts toward the higher peer and industry ranges.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hawaiian Electric Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views remain on whether Hawaiian Electric Industries is undervalued or fairly priced. Consider the full picture of risks and potential upsides to form your own view with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hawaiian Electric Industries?
If Hawaiian Electric Industries has you rethinking risk and valuation, do not stop here. Fresh ideas often come from comparing very different opportunities side by side.
- Target resilient balance sheets by scanning companies with strong fundamentals in the list of solid balance sheet and fundamentals (26 results).
- Hunt for mispriced opportunities by zeroing in on quality shares that screen as attractively valued in the 31 high quality undervalued stocks.
- Build a watchlist of potential future winners by checking out quietly strong businesses highlighted in the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com