
Is AB SKF (OM:SKF B) Fairly Valued As Its New Lubrication Pump Draws Attention?
AB SKF (OM:SKF B) has just rolled out its new Progressive Lubrication Pump, a platform-based automatic lubrication system designed to improve machine reliability, reduce maintenance effort, and help control operating costs for industrial and mobile users.
Recent trading has been quietly supportive for AB SKF, with a 1-month share price return of 4.00% and an 11.17% year-to-date share price return at a last close of SEK275.6. Total shareholder return of 16.88% over one year and 64.00% across three years points to sustained interest as new products like the PLP shape how investors think about the company’s risk and opportunity profile.
Scan how AB SKF’s lubrication push compares with other industrial plays by checking out 90 robotics and automation stocks, which is riding the same automation and reliability trend.
After that solid multi year run and the recent push to SEK275.6, the debate around AB SKF is simple. Is the bigger upside still ahead, or has most of the easy money already been made?
Most Popular Narrative: 4% Overvalued
Compared with the last close at SEK275.6, the most followed fair value estimate for AB SKF sits at SEK266.06. This frames the current debate as a modest premium rather than a deep value setup.
The ongoing automation and digitalization of manufacturing, along with AB SKF's continued investments in automation, manufacturing regionalization, and rightsizing are expected to enhance operational efficiency and support sustained improvements in operating and EBITDA margins over the next several years. The expansion and modernization of the industrial segment now contributing 72% of sales and 89% of adjusted operating profit positions SKF to benefit from the global push for energy efficiency and sustainability, driving future revenue growth from advanced, energy-efficient bearing solutions.
See why 21 investors see AB SKF as 4% overvalued.
Result: Fair Value of SEK266.06 (OVERVALUED)
Still, heavy reliance on a weaker automotive arm, along with execution risk around that separation, could quickly challenge the current fair value narrative for AB SKF.
Find out about the key risks to this AB SKF narrative.
Another View On AB SKF’s Valuation
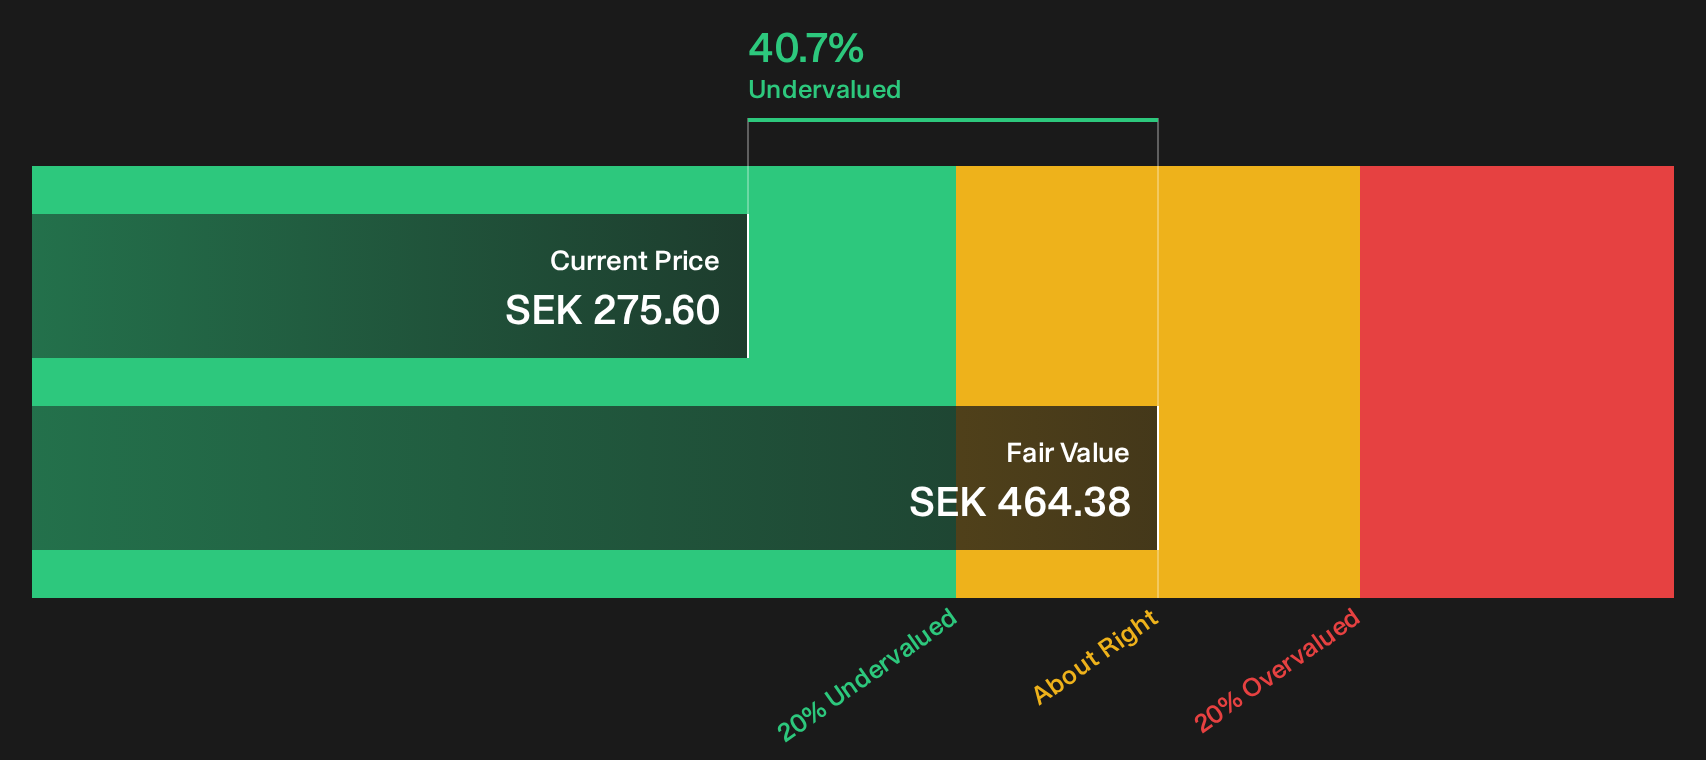
Fair value based on analyst targets and earnings forecasts pegs AB SKF as slightly overvalued around SEK266.06. Yet Simply Wall St’s cash flow model paints a different picture, with the shares trading 40.7% below an estimated future cash flow value of SEK464.38. Which story do you trust more: price targets or cash flows?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on AB SKF so far. If you want a clearer view, go straight to the underlying data and weigh up the 2 key rewards and 1 important warning sign.
Looking For More Ideas Beyond AB SKF?
If AB SKF has sharpened your interest in quality industrial exposure, do not stop here. Broader idea hunting can help round out your watchlist and reveal opportunities you might otherwise miss.
- Target resilient compounders by scanning companies with strong fundamentals and low risk profiles through the 228 resilient stocks with low risk scores.
- Hunt for stronger value opportunities by reviewing the 196 high quality undervalued stocks that pair solid cash flows with quality balance sheets.
- Spot earlier stage potential by checking out the 615 high quality undiscovered gems that combine sound financials with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com