
3 Great Dividend Stocks To Own In October 2026
Rising government borrowing costs are back in focus after the latest bond market moves, and higher real interest rates are forcing investors to think harder about where every dollar works. Reliable income suddenly matters more. That is where companies paying solid, well covered dividends above 3% come in. This article walks through three dividend heavyweights from our screener that aim to offer consistency when bond markets feel unpredictable.
The stocks covered below are just a small sample, and the full Dividend Powerhouses screen surfaced 170 more income ideas with similarly compelling stories that are not included here.
To go deeper on this income theme, head straight into the Dividend Powerhouses (3%+ Yield) screener to identify, filter and analyze the dividend payers that best fit your own risk and return goals.
Chevron (CVX)
Overview: Chevron is a global integrated energy group that explores for, produces, refines, and markets oil, gas, fuels, and petrochemicals.
Operations: Chevron generates most revenue from Downstream activities, with about US$161b from refining and marketing and around US$108b from Upstream operations.
Market Cap: US$406.2b
Chevron matters for this Dividend Powerhouses theme because its cash rich Downstream refining and marketing arm helps underpin a well covered, income focused payout even when commodity markets feel unsettled.
"Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel. This supports future revenue and free cash flow."
For income investors, what happens if a single unseen cost pressure quietly erodes those improving margins will matter far more than headlines.
Those hidden pressures are exactly what the full narrative for Chevron unpacks, showing where Chevron's cash engine could be accelerating or quietly stalling next.

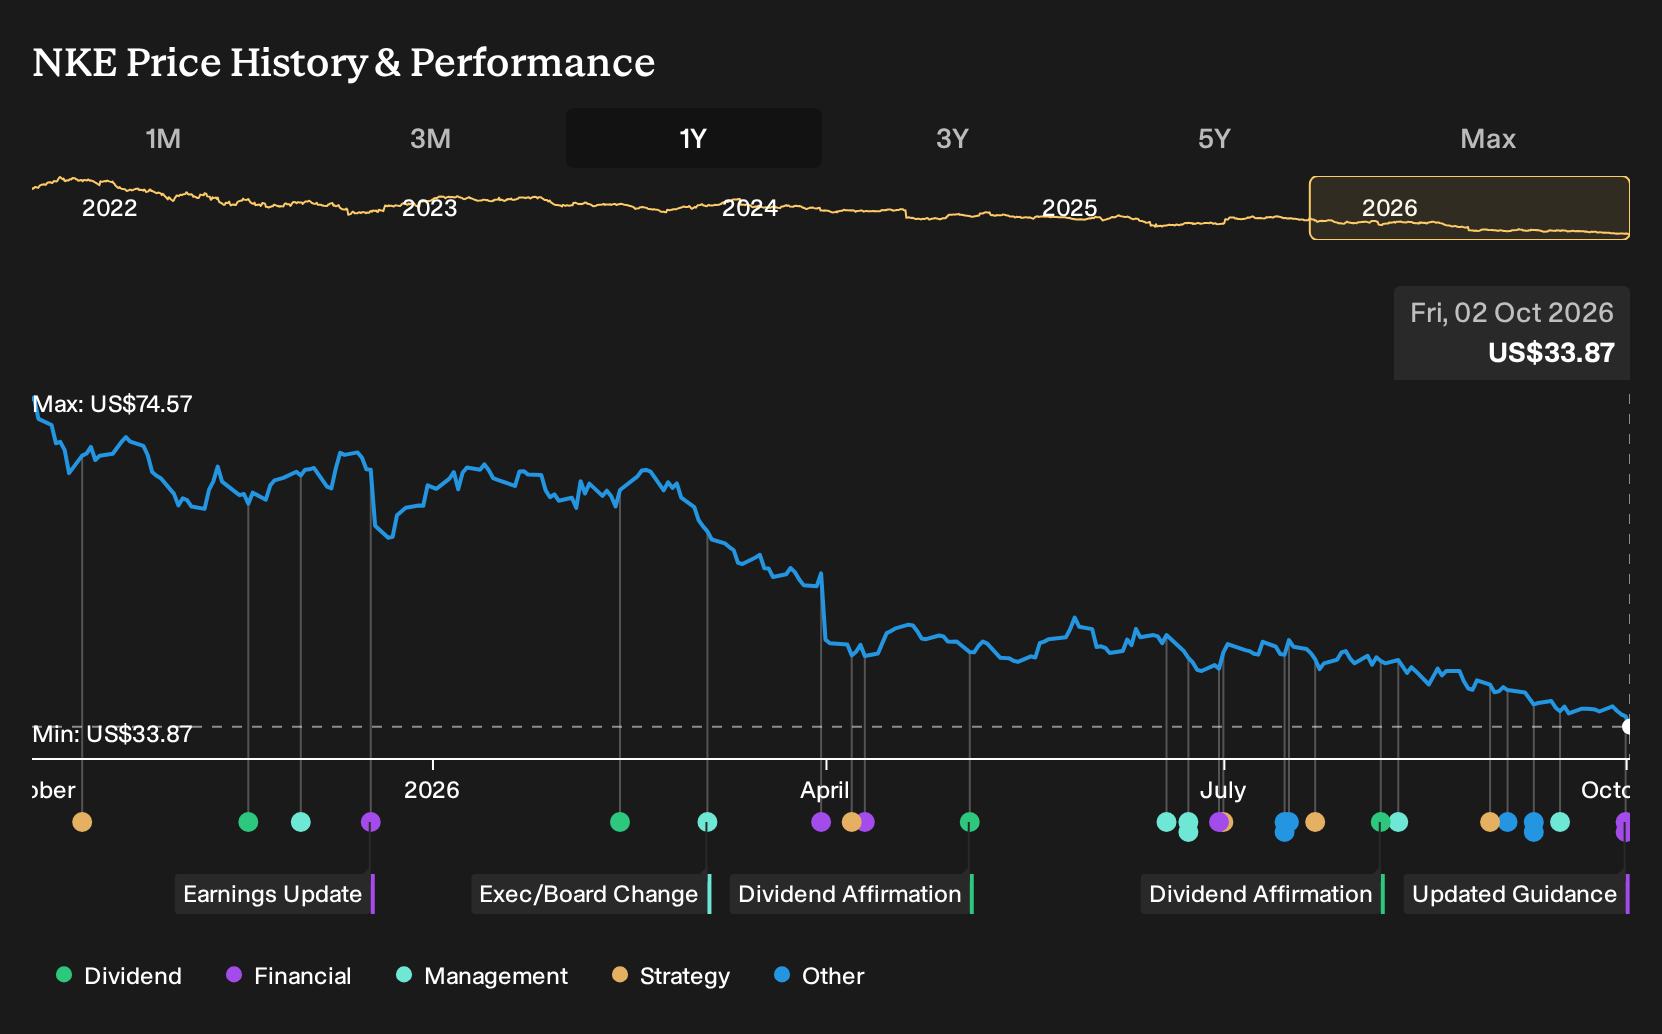
NIKE (NKE)
Overview: Nike is a global sportswear group that designs and sells athletic footwear, apparel and accessories. NIKE Direct powers high-margin, recurring cash flows that support its dividend alongside a broad wholesale and licensing base.
Market Cap: US$52.1b
Nike matters to a dividend-focused reader because the NIKE Direct engine links a well known brand to a stream of recurring cash that can help fund regular payouts, even as the business works through slower growth and fiercer competition across key categories.
"However, there are some risks for the company, represented by the High uncertainty rating, showing that Nike, despite having a history of success, needs to keep reinventing itself providing, as always, great products to its clients."
One risk to consider is what happens if a single assumption about how quickly that cash rich direct business improves margins and earnings quietly proves too optimistic.
When that optimism proves too rosy, the full narrative for NIKE shows where Nike’s direct engine could still be accelerating and which underappreciated levers might reset the story.
VICI Properties (VICI)
Overview: VICI Properties is a real estate investment trust that owns casino, hospitality and leisure properties, collecting long term rent to support dividends.
Operations: VICI Properties generates about US$4.1b from real estate investment activities, with all reported revenue coming from properties in the United States.
Market Cap: US$25b
For income focused readers, VICI Properties matters because its long term, triple net leases on marquee gaming and hospitality venues are designed to feed a steady, cash backed dividend stream that fits the Dividend Powerhouses theme.
"Given the historical data presented, my assumption is that the company will be able to growth its revenues ~3.5-4.5% during Year 1 and ~3.5-5.5% each year from Year 2-5."
What really shapes the appeal of that income profile is how one unseen pressure on VICI Properties’ funding costs ultimately plays out.
That funding question is exactly where the full narrative for VICI Properties steps in, revealing how VICI Properties’ growth, rent escalators and balance sheet decisions could be quietly decoupling from headline risks.

Seeking Fresh Alternatives Right Now
Fresh ideas move first. By the time every dividend hunter piles in, the early entry window can be gone. Scan these under the radar lists while it matters and get in early.
- Spot companies quietly building momentum before headlines catch up by running the curated 19 high quality undiscovered gems that surfaces under followed opportunities with stronger fundamentals than the crowd expects.
- Track where real cash generation meets balance sheet strength through the focused list of solid balance sheet and fundamentals (26 results) and avoid businesses that look exciting but struggle to fund their own plans.
- Position ahead of infrastructure spending themes by reviewing the targeted 40 power grid technology and infrastructure stocks and see which enablers of the next grid upgrade cycle are still flying below the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com