
MillerKnoll (MLKN) Earnings Lifted Profit, Is The Stock Still A Bargain?
MillerKnoll (MLKN) has drawn fresh attention after reporting first quarter earnings on September 22, 2026, with higher net income and earnings per share despite lower sales compared with a year earlier.
The recent earnings update and long running share repurchase program have landed against a mixed price backdrop for MillerKnoll. The stock’s 1-year total shareholder return of 20.63% contrasts with a share price that is down 9.46% over the past month and 5.51% over the last quarter, which hints that enthusiasm around improved profitability is meeting some resistance after earlier gains year to date and over longer horizons.
Capitalize on MillerKnoll’s earnings focus by scanning a curated group of list of solid balance sheet and fundamentals (26 results) that pair profitability with financial resilience.MillerKnoll’s earnings strength is now colliding with a share price that has cooled over the last month. Does it make more sense to step in after this pullback, or to wait for an even cheaper valuation first?
Most Popular Narrative: 42% Undervalued
MillerKnoll’s most followed narrative points to a fair value of $35 per share, which sits well above the recent $20.24 close. As a result, the current pullback is being weighed against a thesis that still sees meaningful upside over time.
The restructuring of MillerKnoll's reporting segments to better align with strategic goals could improve operational clarity and facilitate growth, potentially boosting revenue and net earnings by optimizing resource allocation and improving market focus.
The company's investment in innovative new products and exclusive designer collaborations may drive higher revenue growth due to increased consumer appeal and competitive differentiation, contributing positively to long-term earnings.
See why 3 investors see MillerKnoll as 42% undervalued.
Result: Fair Value of $35 (UNDERVALUED)
Still, MillerKnoll’s thesis rests on cleaner retail execution and tariff management. Setbacks in either could quickly erode confidence in that 42% discount story.
Find out about the key risks to this MillerKnoll narrative.
Another Angle On MillerKnoll’s Valuation
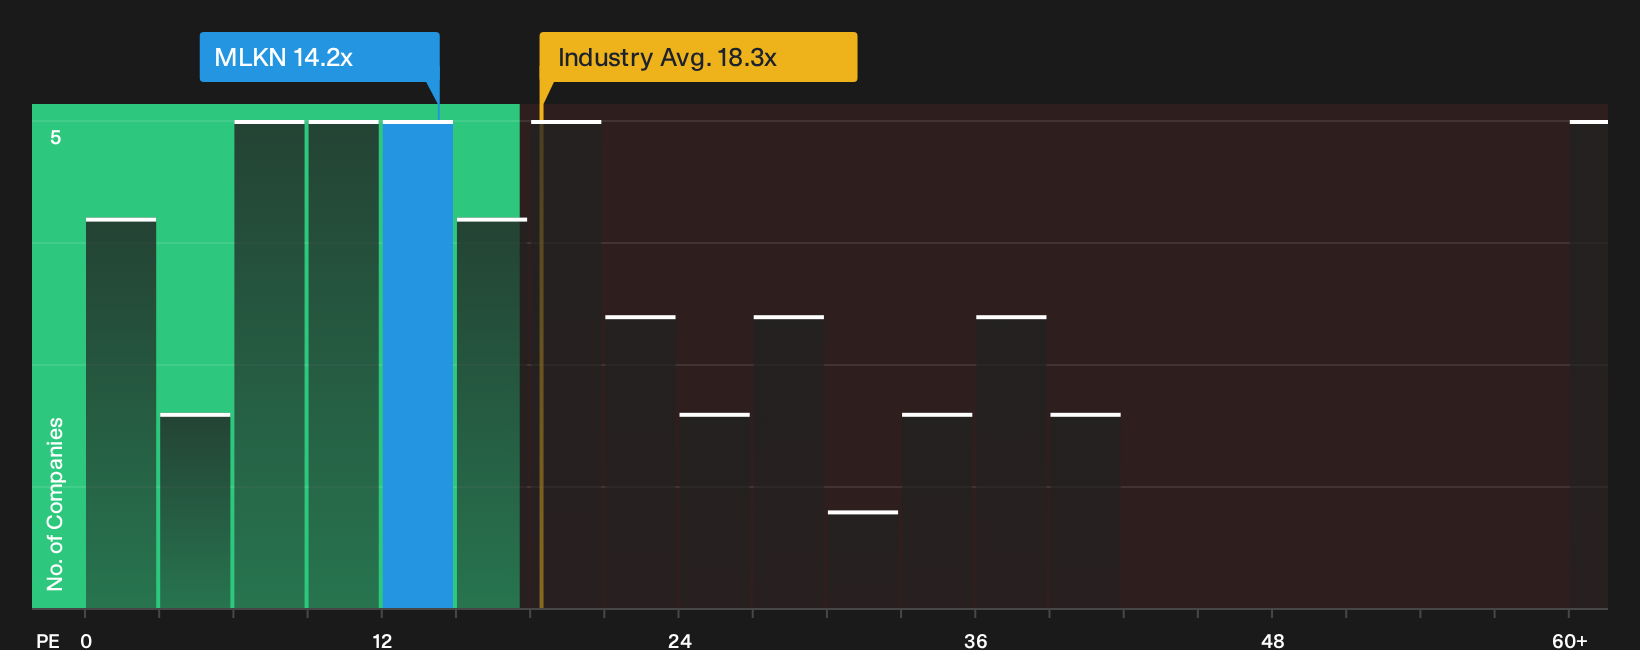
The earlier narrative leans on a discounted cash flow view that frames MillerKnoll as undervalued. A simpler yardstick tells a more cautious story. On a P/E of 14.2x, the stock trades above peer averages at 13.5x, yet below its own fair ratio of 19.6x.
That mix of slight expensiveness versus similar companies and a discount to the 19.6x fair ratio points to a tug of war between perceived safety and upside. Which side of that gap do you think matters more for your portfolio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on MillerKnoll’s value case can feel confusing, especially with both risks and rewards on the table. Act promptly: review the data and pressure test the bullish and cautious angles for yourself by checking our breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond MillerKnoll?
If MillerKnoll has sharpened your focus on quality and price, do not stop here. Broadening your opportunity set can help you compare risk, income and upside more clearly.
- Target reliable cash generators by reviewing a 31 high quality undervalued stocks that blend strong fundamentals with prices that still look restrained.
- Boost portfolio resilience by scanning a 31 resilient stocks with low risk scores built around sturdier balance sheets and more consistent financial profiles.
- Spot tomorrow’s potential leaders early by checking a 19 high quality undiscovered gems before other investors start paying closer attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com