
Here's Why We're Watching Cardiol Therapeutics' (TSE:CRDL) Cash Burn Situation
We can readily understand why investors are attracted to unprofitable companies. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
So should Cardiol Therapeutics (TSE:CRDL) shareholders be worried about its cash burn? For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
How Long Is Cardiol Therapeutics' Cash Runway?
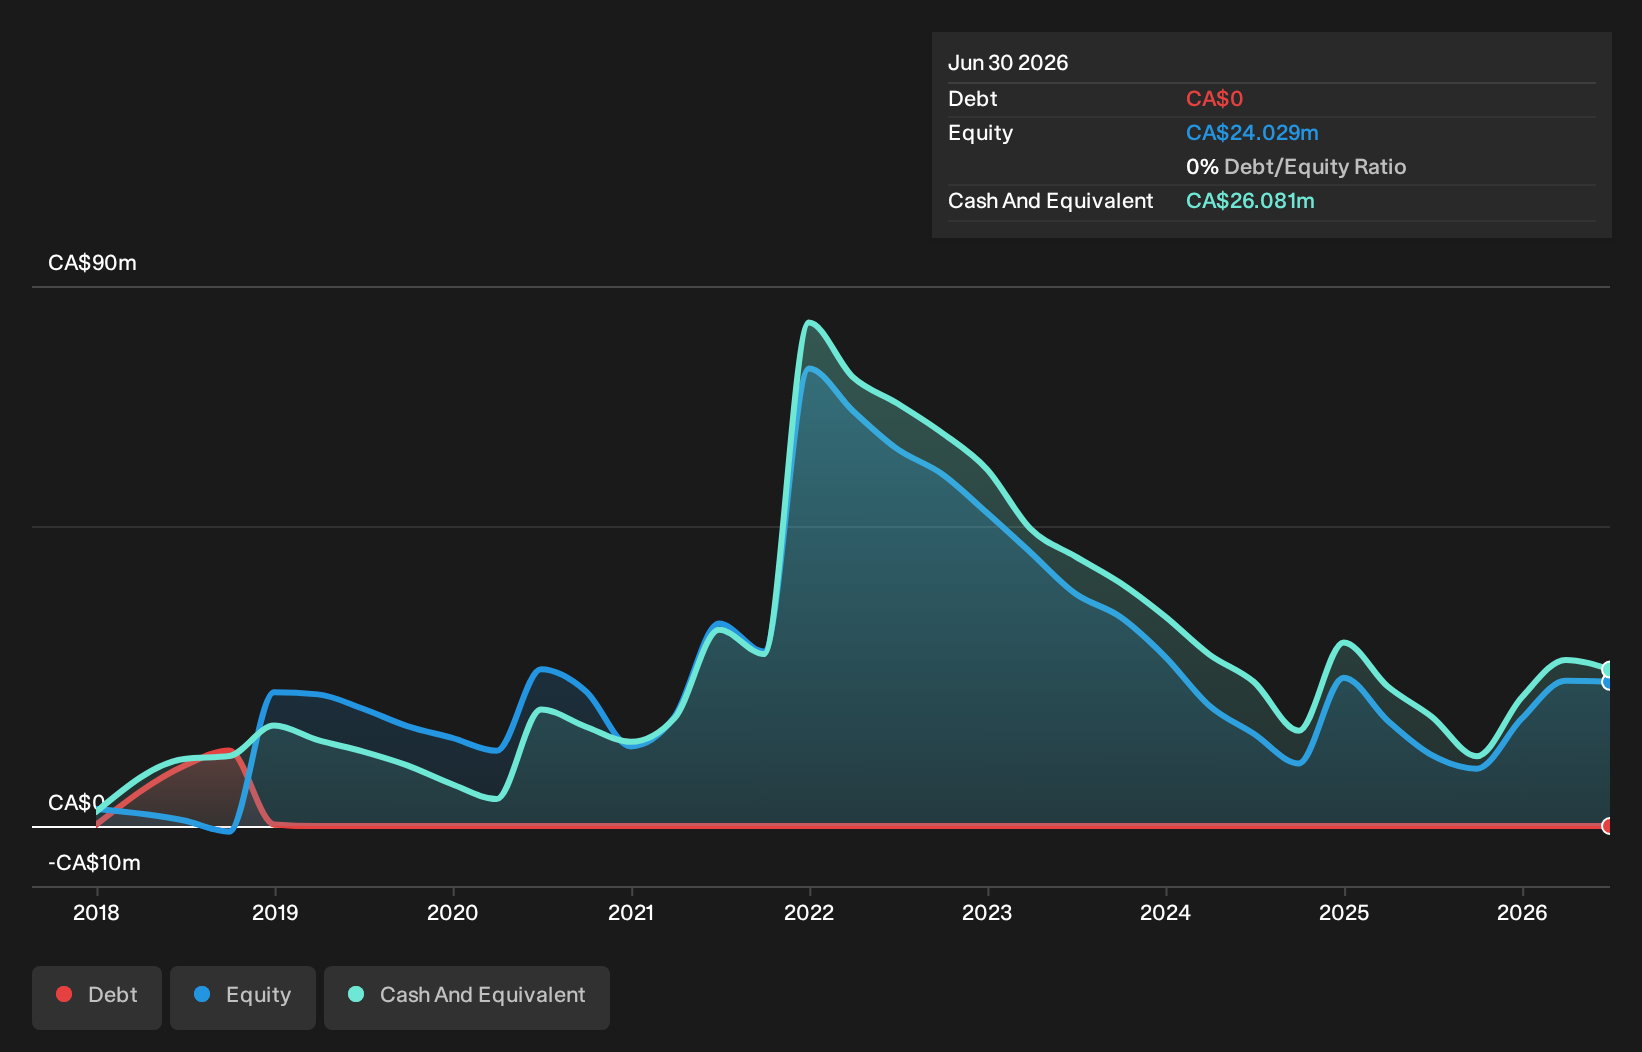
A company's cash runway is calculated by dividing its cash hoard by its cash burn. As at June 2026, Cardiol Therapeutics had cash of CA$26m and no debt. Looking at the last year, the company burnt through CA$24m. Therefore, from June 2026 it had roughly 13 months of cash runway. Importantly, analysts think that Cardiol Therapeutics will reach cashflow breakeven in 4 years. That means unless the company reduces its cash burn quickly, it may well look to raise more cash. You can see how its cash balance has changed over time in the image below.
Check out our latest analysis for Cardiol Therapeutics
How Is Cardiol Therapeutics' Cash Burn Changing Over Time?
Because Cardiol Therapeutics isn't currently generating revenue, we consider it an early-stage business. Nonetheless, we can still examine its cash burn trajectory as part of our assessment of its cash burn situation. With cash burn dropping by 4.0% it seems management feel the company is spending enough to advance its business plans at an appropriate pace. While the past is always worth studying, it is the future that matters most of all. For that reason, it makes a lot of sense to take a look at our analyst forecasts for the company.
Can Cardiol Therapeutics Raise More Cash Easily?
While Cardiol Therapeutics is showing a solid reduction in its cash burn, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Companies can raise capital through either debt or equity. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Since it has a market capitalisation of CA$261m, Cardiol Therapeutics' CA$24m in cash burn equates to about 9.3% of its market value. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
Is Cardiol Therapeutics' Cash Burn A Worry?
The good news is that in our view Cardiol Therapeutics' cash burn situation gives shareholders real reason for optimism. Not only was its cash burn reduction quite good, but its cash burn relative to its market cap was a real positive. Shareholders can take heart from the fact that analysts are forecasting it will reach breakeven. Cash burning companies are always on the riskier side of things, but after considering all of the factors discussed in this short piece, we're not too worried about its rate of cash burn. Taking an in-depth view of risks, we've identified 3 warning signs for Cardiol Therapeutics that you should be aware of before investing.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.