
We're Not Very Worried About Allogene Therapeutics' (NASDAQ:ALLO) Cash Burn Rate
We can readily understand why investors are attracted to unprofitable companies. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
So, the natural question for Allogene Therapeutics (NASDAQ:ALLO) shareholders is whether they should be concerned by its rate of cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. Let's start with an examination of the business' cash, relative to its cash burn.
When Might Allogene Therapeutics Run Out Of Money?
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. When Allogene Therapeutics last reported its June 2026 balance sheet in August 2026, it had zero debt and cash worth US$333m. Looking at the last year, the company burnt through US$103m. That means it had a cash runway of about 3.2 years as of June 2026. Notably, analysts forecast that Allogene Therapeutics will break even (at a free cash flow level) in about 3 years. That means it doesn't have a great deal of breathing room, but it shouldn't really need more cash, considering that cash burn should be continually reducing. Depicted below, you can see how its cash holdings have changed over time.
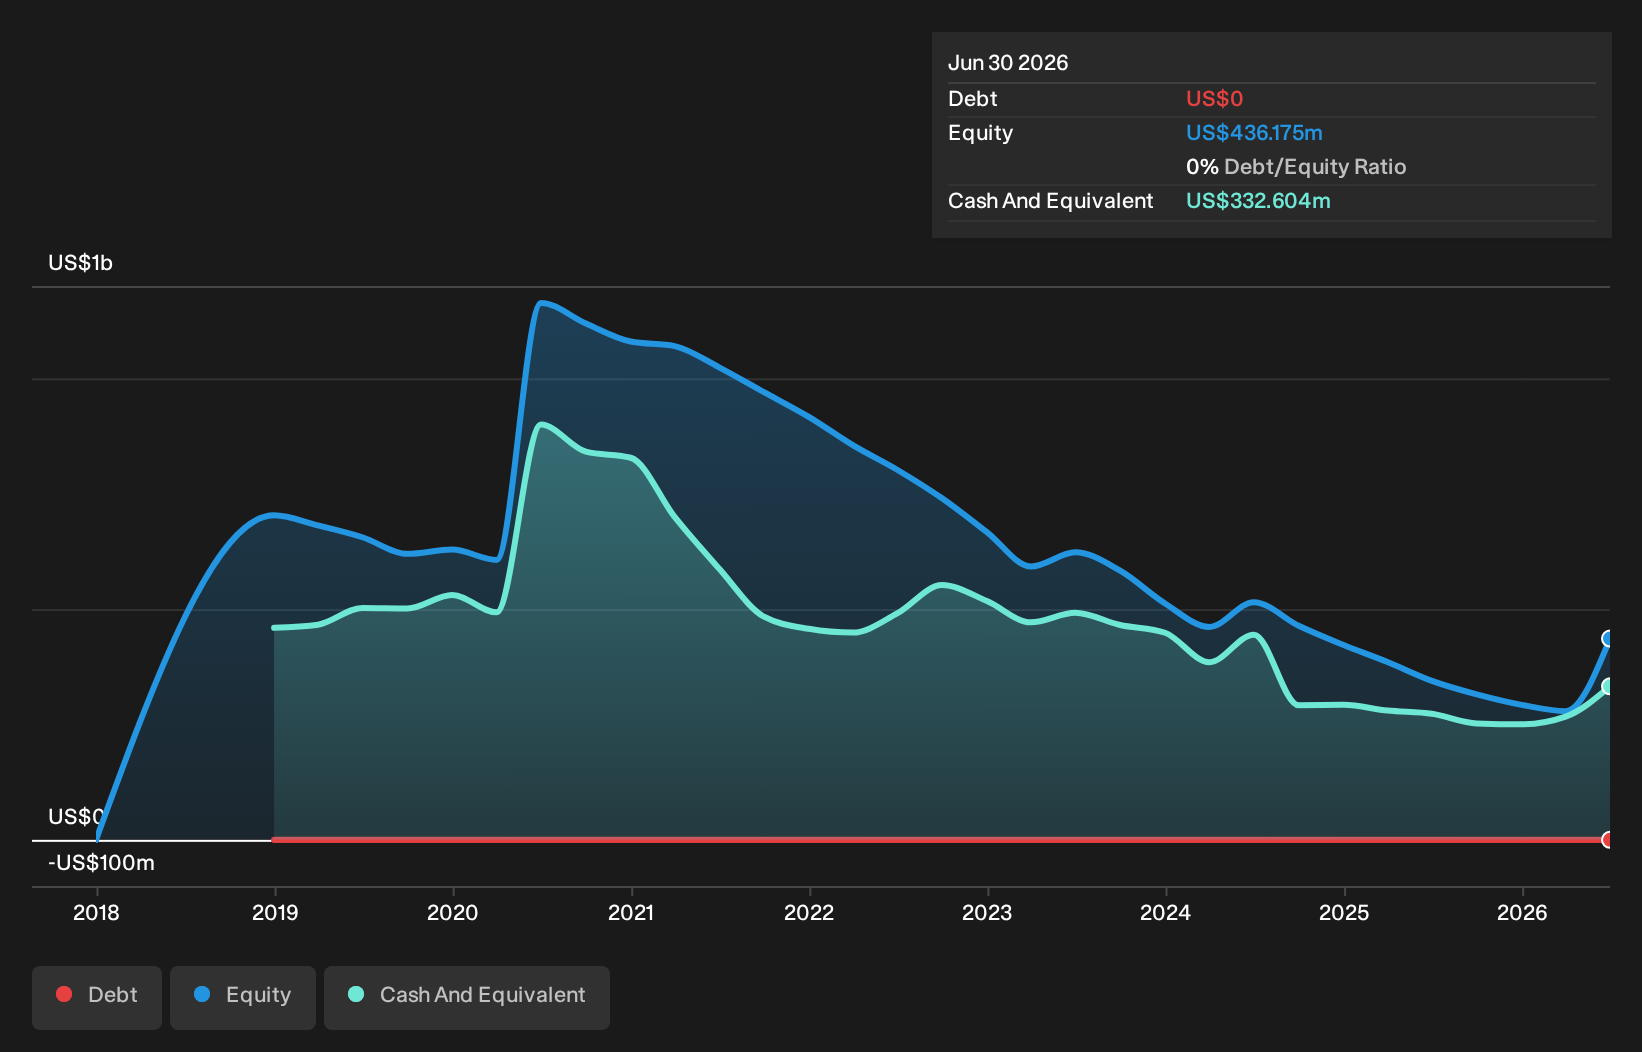
See our latest analysis for Allogene Therapeutics
How Is Allogene Therapeutics' Cash Burn Changing Over Time?
Whilst it's great to see that Allogene Therapeutics has already begun generating revenue from operations, last year it only produced US$4.6m, so we don't think it is generating significant revenue, at this point. Therefore, for the purposes of this analysis we'll focus on how the cash burn is tracking. While it hardly paints a picture of imminent growth, the fact that it has reduced its cash burn by 41% over the last year suggests some degree of prudence. While the past is always worth studying, it is the future that matters most of all. For that reason, it makes a lot of sense to take a look at our analyst forecasts for the company.
How Hard Would It Be For Allogene Therapeutics To Raise More Cash For Growth?
Even though it has reduced its cash burn recently, shareholders should still consider how easy it would be for Allogene Therapeutics to raise more cash in the future. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. Commonly, a business will sell new shares in itself to raise cash and drive growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Allogene Therapeutics has a market capitalisation of US$532m and burnt through US$103m last year, which is 19% of the company's market value. Given that situation, it's fair to say the company wouldn't have much trouble raising more cash for growth, but shareholders would be somewhat diluted.
Is Allogene Therapeutics' Cash Burn A Worry?
As you can probably tell by now, we're not too worried about Allogene Therapeutics' cash burn. For example, we think its cash runway suggests that the company is on a good path. Its weak point is its cash burn relative to its market cap, but even that wasn't too bad! Shareholders can take heart from the fact that analysts are forecasting it will reach breakeven. Considering all the factors discussed in this article, we're not overly concerned about the company's cash burn, although we do think shareholders should keep an eye on how it develops. Separately, we looked at different risks affecting the company and spotted 3 warning signs for Allogene Therapeutics (of which 1 is potentially serious!) you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.