
Qorvo (QRVO) Could Be 25% Overvalued Following Russell Index Removal
Qorvo’s index removal puts stock exposure in focus
Qorvo (QRVO) has been dropped from a wide range of Russell value and core benchmarks, including the Russell 1000, 2500, 3000 and several related style and completeness indices.
These exits could alter how index funds and benchmarked portfolios treat the semiconductor group, which already shows mixed return patterns over the past year, the recent quarter and the most recent month.
Qorvo’s removal from several Russell indices comes at a time when momentum has been picking up, with a 30.4% three-month share price return and a 32.3% year-to-date move, even though the five-year total shareholder return is still down 31.2%.
Scan beyond Qorvo’s reshuffle and compare it with a curated group of quality opportunities using our 31 high quality undervalued stocks built around strong fundamentals and potential mispricing.
Qorvo looks like a solid specialist in radio frequency and connectivity, yet the shares have surged while value indices move on without it. Is this a high quality business at a stretched price, or still misjudged?
Most popular Qorvo valuation narrative: 25% overvalued
Qorvo last closed at $114.17, while the most followed narrative pegs fair value at about $91.46 using a 12.03% discount rate. This frames the recent index exit against a stock price already sitting well above that internal estimate.
Material improvements in operational efficiency such as the exit from legacy low-margin Android businesses, consolidation of manufacturing footprint (closure of North Carolina and Costa Rica sites), and product portfolio rationalization are projected to drive sustainable cost savings and support higher operating margins starting late fiscal '27.
See why 18 investors see Qorvo as 25% overvalued.
Result: Fair Value of $91.46 (OVERVALUED)
Still, Qorvo’s heavy reliance on a single customer and the execution risk in shifting away from low-margin Android exposure could easily challenge this valuation story.
Find out about the key risks to this Qorvo narrative.
Another view on Qorvo’s valuation
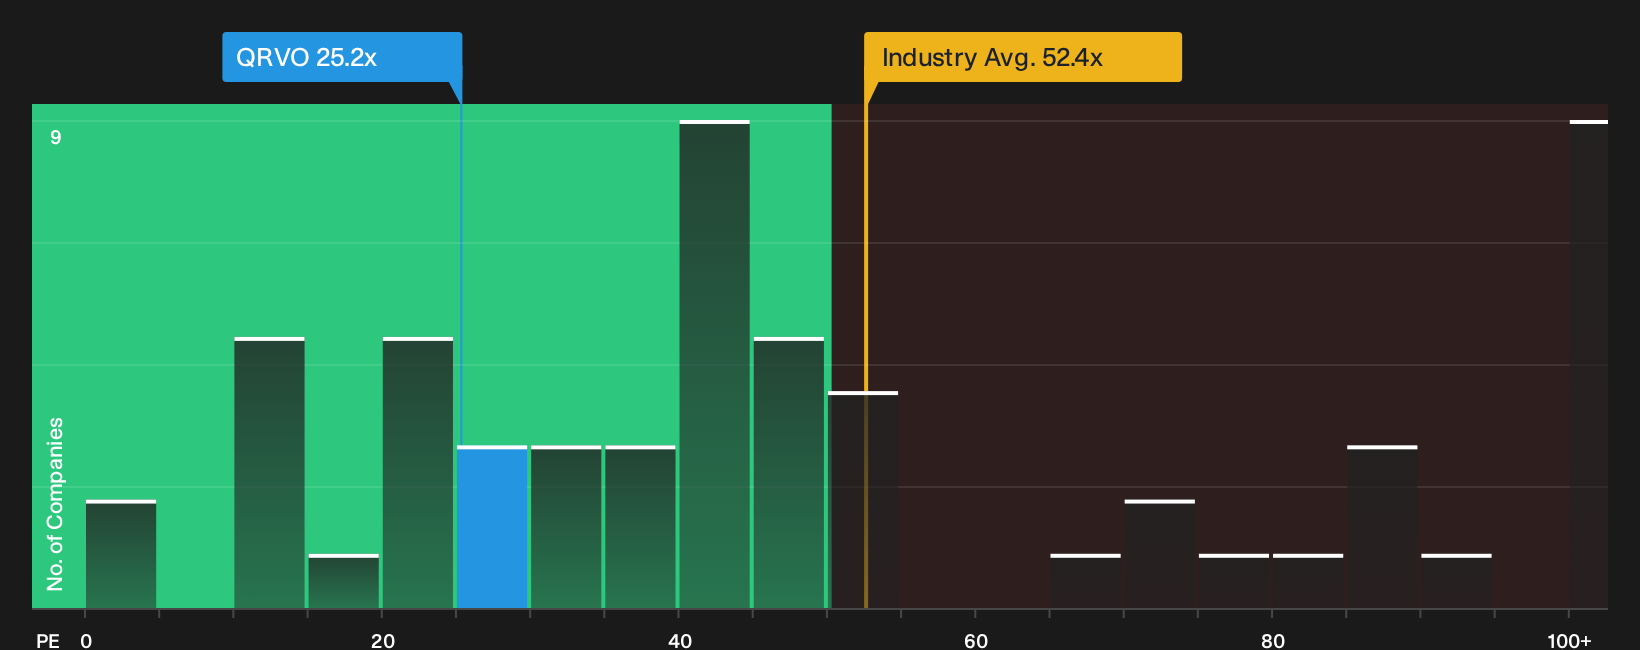
The narrative fair value places Qorvo at $91.46, which implies the current $114.17 quote appears overvalued. Yet the simple P/E picture looks different. At 25.2x earnings, QRVO trades well below the US Semiconductor industry on 49.5x and under the peer average of 35.4x.
The key consideration is the fair ratio. Our estimate of a 22.4x multiple suggests the market could move closer to that level over time, which would make today’s valuation look somewhat expensive rather than cheap. That leaves investors weighing an apparently low sector-relative P/E against a fair ratio that points to more limited upside. Which signal carries more weight for you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether Qorvo is being priced too optimistically or too cautiously right now? Act while the data is fresh and weigh the trade off for yourself by checking the 3 key rewards and 1 important warning sign.
Looking for more Qorvo sized ideas?
If Qorvo’s story has you thinking about what else might be mispriced, use the Simply Wall St Screener to hunt for fresh, data backed opportunities before they move.
- Target potential bargains by scanning a 31 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their underlying strength.
- Prioritize resilience by reviewing a 31 resilient stocks with low risk scores that filters for businesses with lower risk scores and steadier financial profiles.
- Spot early stage opportunities by checking a 19 high quality undiscovered gems that highlights under the radar companies with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com