
ASICS (TSE:7936) After Its Buyback Tranche Looks Cheap Against Fair Value
ASICS (TSE:7936) has just finished a share repurchase tranche, buying 4,199,400 shares, or 0.59% of its equity, between September 9 and September 30 for ¥16,999.72 million.
ASICS shares have cooled after a strong run, with the 90 day share price return down 10.45% and a softer 30 day move, even though the 1 year total shareholder return of 9.83% and the very large 5 year total shareholder return suggest that long term holders have still seen substantial gains.
Scan 75 high quality undiscovered gems that, like ASICS after its buyback, may be quietly reshaping their shareholder base before the wider market catches on.
ASICS now trades well below both analyst targets and one estimate of fair value, even after completing its latest buyback. Is the discount a sensible response to recent share weakness, or does it represent a mispricing of the underlying business?
ASICS valuation: premium P/E versus fair value and peers
ASICS currently trades at ¥4,141, and one SWS DCF model estimate of future cash flows points to a fair value around ¥5,430.87, which implies the stock is trading at a discount even after the recent share price pullback.
The same data set shows ASICS on a P/E of 22.3x, which investors often use to compare what the market is paying for each unit of current earnings across similar businesses.
That earnings multiple sits above the JP Luxury industry average of 15.5x, yet is almost in line with the peer group at 22.5x and only slightly above the estimated fair P/E of 20.9x that the SWS model suggests the market could eventually gravitate toward.
Explore the SWS fair ratio for ASICS.
Result: Price-to-earnings of 22.3x (OVERVALUED).
Still, the valuation story around ASICS could change quickly if earnings growth underwhelms relative to its higher P/E, or if consumer demand for its footwear and apparel softens.
Find out about the key risks to this ASICS narrative.
Another view on ASICS valuation
A second lens on ASICS comes from analysts' price targets rather than the SWS DCF model. Their average target sits at ¥5,713.57, which is about 38% above the current ¥4,141 share price, so these external expectations suggest that some market participants view the stock as undervalued. The open question is whether you place more weight on the model or on market-based estimates at this point.
Look into how the SWS DCF model arrives at its fair value.
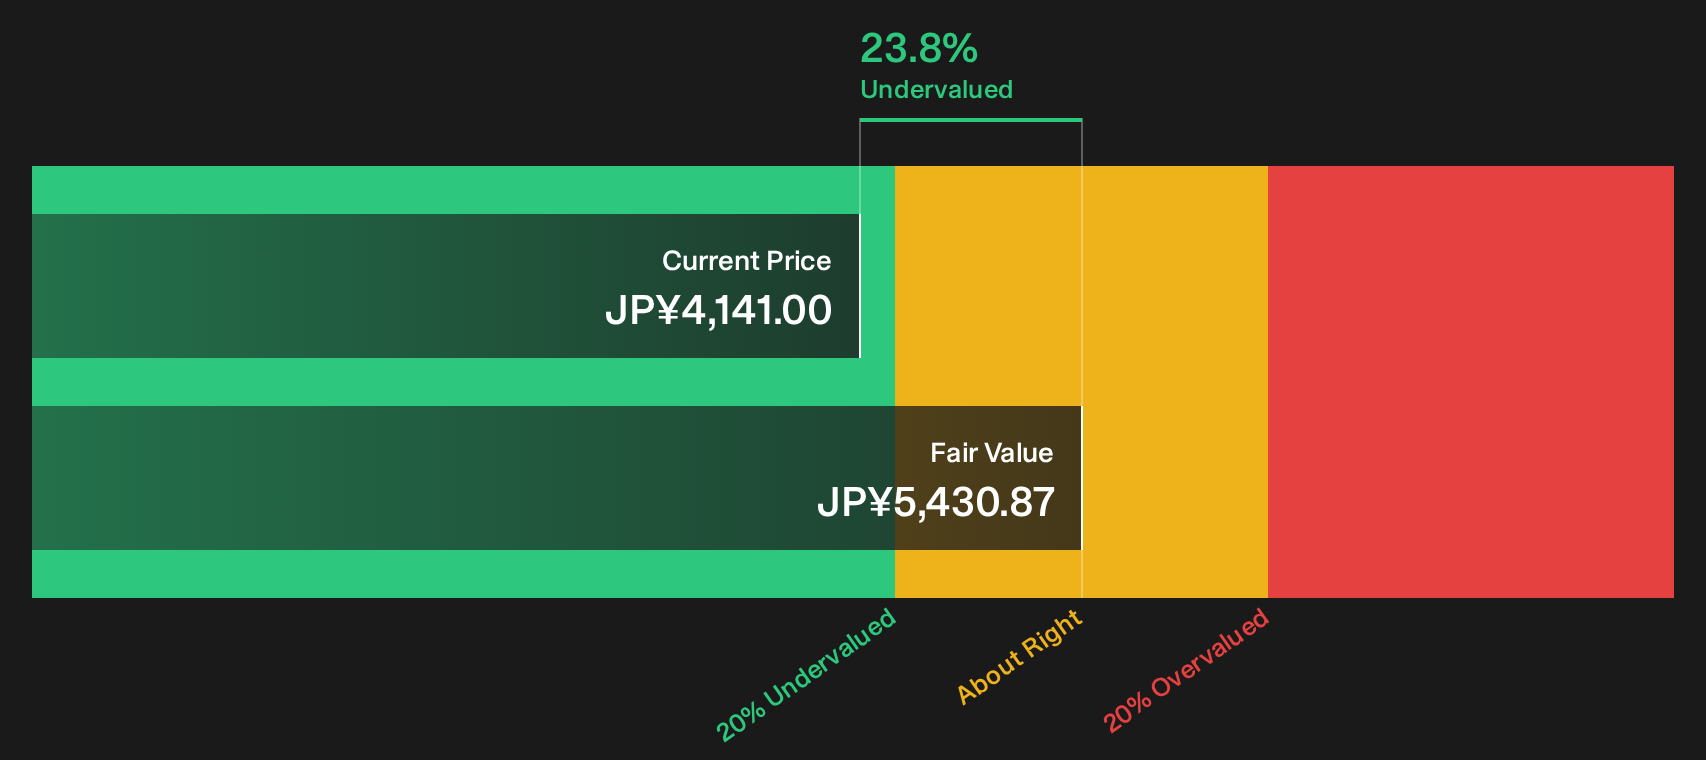
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ASICS for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ASICS valuation can feel confusing, so move quickly to review the key drivers yourself and then weigh both the upside and the pressure points. To see the balance of risks and potential rewards in one place, start with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond ASICS?
Do not stop your research with ASICS. Fresh opportunities keep surfacing, and a few minutes with the right screeners can surface ideas you would otherwise miss.
- Explore potential value in beaten down opportunities by scanning the 18 high quality undervalued stocks that currently combine compressed prices with stronger underlying fundamentals.
- Strengthen the income side of your portfolio by reviewing a focused set of 24 dividend fortresses that concentrate on higher yields with more resilient payout profiles.
- Dial down portfolio stress by filtering for 23 resilient stocks with low risk scores that aim to pair steadier balance sheets with more measured volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com