
WeRide (WRD) After The ELEVATE Slovakia Deal And The Valuation Debate
WeRide (WRD) is back on investor radar after its partnership with ELEVATE Slovakia. The deal takes the company’s autonomous driving products into the Slovak market and introduces fresh regulatory and customer exposure.
For now, the headline with WeRide is that the partnership news arrives against a weak tape. The stock’s share price has fallen 46.5% year to date and its 1 year total shareholder return is down 54.2%. Any bounce around the ELEVATE Slovakia agreement is coming after a long stretch of fading momentum.
Scan how WeRide compares to other autonomous and AI-focused players under pressure this year by checking the hand picked 37 profitable AI stocks that aren't just burning cash in the sector.
WeRide is signing new partners and growing revenue, while the share price has been hit hard this year. Is that a solid business on sale, or a fair markdown on the risks?
Most Popular Narrative: 64% Undervalued
Against a last close of $5.03, the most followed valuation narrative for WeRide points to a fair value of $14.09, which sets up a wide gap investors are trying to explain.
The dual deployment of L4 robotaxis and L2+ WePilot 3.0 ADAS in mass production vehicles from Chery EXEED and GAC allows data and software to be reused across product lines. This can spread R&D spending over a larger revenue base and potentially support higher group level margins.
See why 8 investors see WeRide as 64% undervalued.
Result: Fair Value of $14.09 (UNDERVALUED)
Still, the WeRide narrative depends on fresh permits arriving on time and on R&D spending eventually being matched by robotaxi, robobus and ADAS revenue.
Find out about the key risks to this WeRide narrative.
Another View: What Multiples Say About WeRide
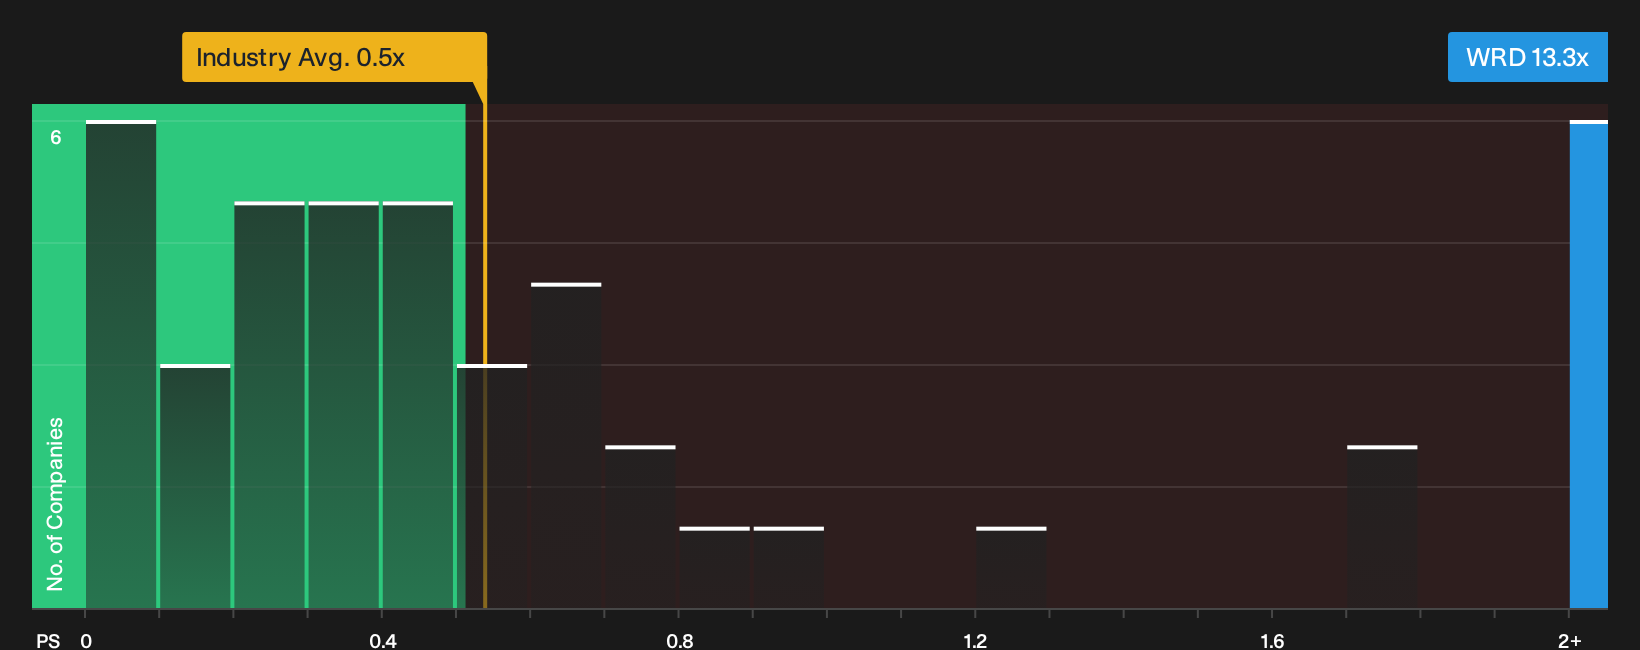
There is a very different message coming from simple market ratios. WeRide trades on a P/S of 13.3x, while the US Auto Components industry averages 0.5x and peers sit around 2.1x. The fair ratio is 3.7x, which implies investors are already paying up heavily. Is that optimism or valuation risk?
Our ratio work suggests the current pricing stands far above both the sector and the fair ratio. This raises questions about how much of the WeRide story is already reflected in the quoted price, and how much margin for error may remain. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around WeRide is clearly split, which is exactly why independent work matters. If you want a quick way to pressure test the upside case, start with the 1 key reward.
Looking for more WeRide investment ideas?
If you are only focused on WeRide, you might miss opportunities elsewhere, so use the Simply Wall Street Screener to surface fresh ideas before others do.
- Target resilient cash generators by reviewing the 31 high quality undervalued stocks that combine compressed valuations with stronger fundamentals.
- Lock in income potential by scanning the 7 dividend fortresses that offer higher yields alongside business stability checks.
- Protect your downside by filtering for the 31 resilient stocks with low risk scores that carry lower overall risk scores while still offering equity upside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com