
3 US REIT Stocks Worth Watching As Rate Cut Hopes Return
Cooling US job data, softer hiring across tech, retail and government, and a slightly higher unemployment rate have put interest rates back at the center of the story. When the pace of hiring slows, rate expectations can shift, and income-focused stocks often move quickly. This article explains that link and walks through three stocks from a US rate-sensitive dividend and value screener that appear positively exposed to this news.
The stocks covered below are just a first pass, and the full screen surfaced 17 more US rate-sensitive dividend and value companies with equally interesting stories that are not included here.
Identify income ideas that fit your own risk tolerance by going straight to the US Rate-Sensitive Dividend & Value Stocks screener.
Americold Realty Trust (COLD)
Overview: Americold Realty Trust runs a global network of temperature-controlled warehouses and logistics services that help food producers and retailers safely store and move refrigerated products, fitting the screener’s focus on essential, income-oriented real estate.
Operations: Americold generates about $2.4b from segment adjustments and $207 million from transportation services, with revenue primarily sourced from North America, Europe and Asia-Pacific.
Market Cap: $3.9b
Americold Realty Trust brings an essential, rent-generating cold storage footprint to a screen built around rate-sensitive, dividend-focused real estate, and the current macro backdrop pushes its income profile and operating leverage into sharper focus.
"The accelerating shift toward e-commerce grocery and direct-to-consumer food delivery continues to drive sustained, structural demand for complex cold-storage logistics and rapid fulfillment, aligning with Americold's investments in automation, specialized services, and high-turn retail/QSR business, enabling them to capture both greater market share and higher-margin revenue growth."
What really matters now is how one less visible pressure on Americold’s cost of capital shapes the path for future cash generation.
That hidden pressure on funding costs is exactly what the full narrative for Americold Realty Trust unpacks, highlighting where Americold Realty Trust could be quietly decoupling from headline rate anxiety.

Alexandria Real Estate Equities (ARE)
Overview: Alexandria Real Estate Equities owns and develops specialized life science campuses that lease lab and office space to research focused tenants.
Operations: Alexandria generates about $2.9b from leasing space to life science, agtech and technology tenants, after a small segment adjustment.
Market Cap: $8.2b
For income investors using this screener, Alexandria Real Estate Equities combines life science exposure, REIT cash flows, and clear sensitivity to shifting rate expectations. This makes management’s capital allocation choices especially important.
"The dividend cut is intended to save approximately $410 million per year and strengthen the balance sheet."
What happens to investor returns now largely depends on how one unresolved funding pressure interacts with future leasing and development economics.
That funding squeeze is only part of the story, and the full narrative for Alexandria Real Estate Equities shows how Alexandria Real Estate Equities could turn balance sheet repair into future upside.

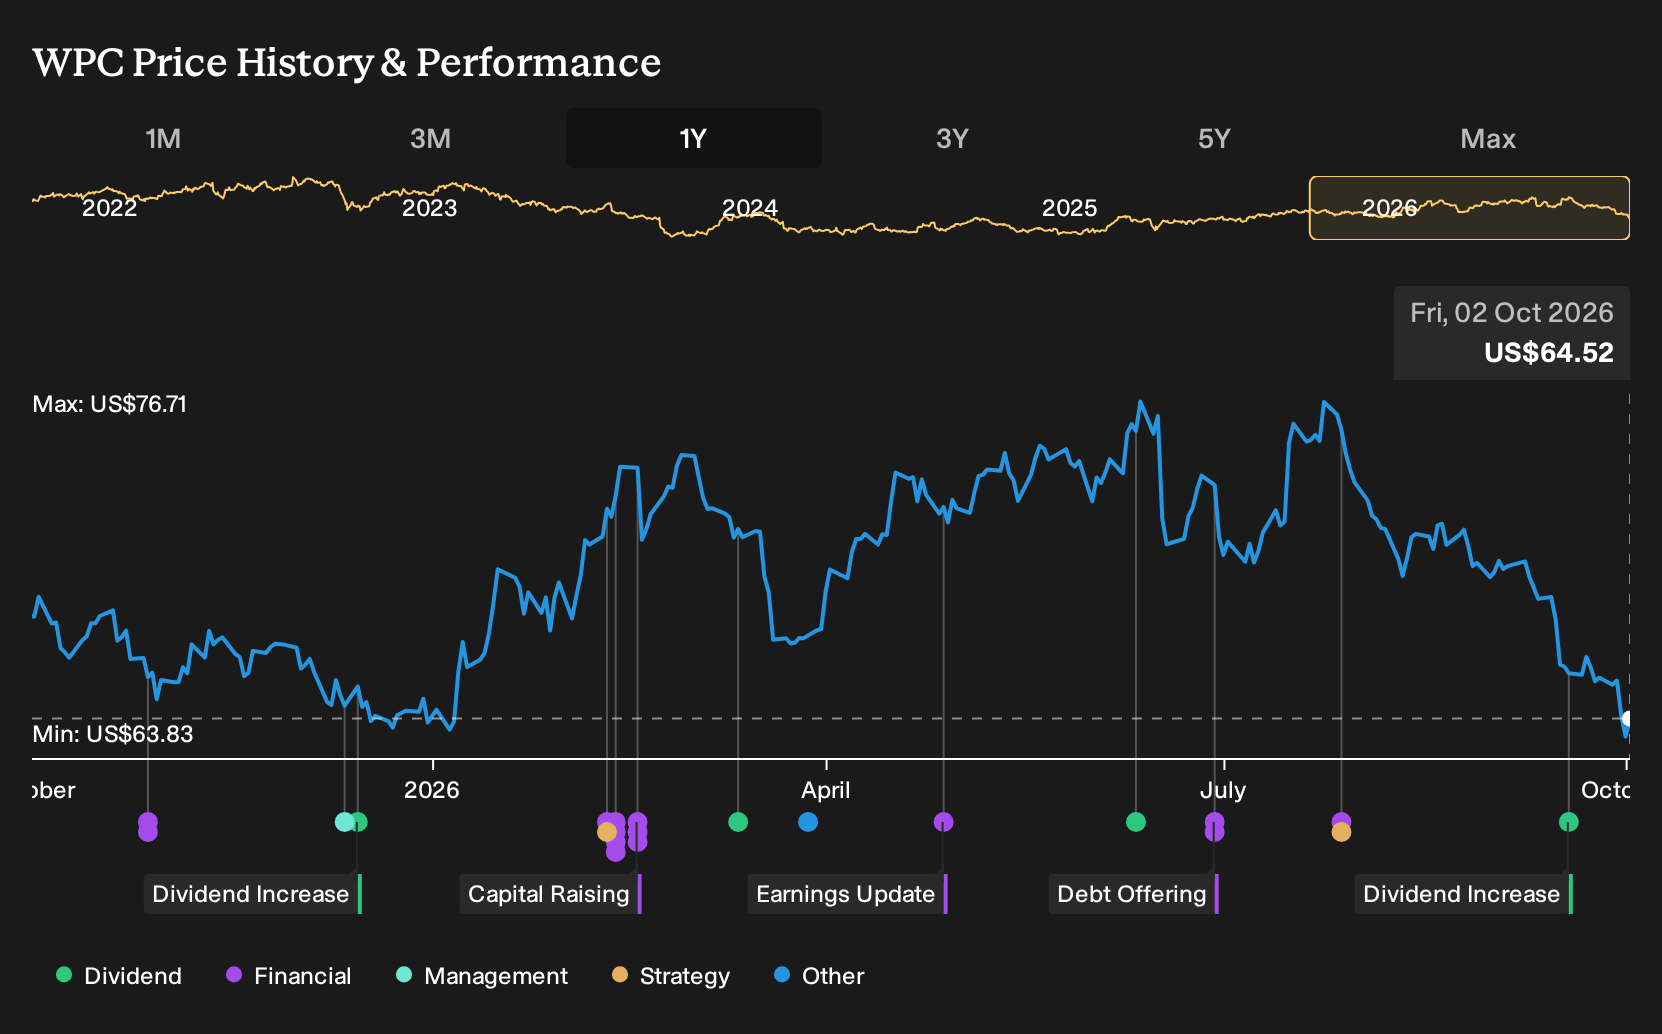
W. P. Carey (WPC)
Overview: W. P. Carey is a large net lease REIT that owns long term, single tenant industrial, warehouse and retail properties generating rental income.
Market Cap: US$14.5b
For income investors scanning rate sensitive REITs, W. P. Carey offers a mix of long leases, embedded rent growth and global diversification. These factors can matter a lot when borrowing costs and inflation expectations start to move.
"Contractual rent escalations, with roughly half of same store leases tied to CPI and the rest carrying fixed annual increases that supported 2.6% contractual rent growth guidance for 2026, provide a built in driver for higher rental revenue and earnings."
What really shapes the payoff from that built in growth is how one less obvious funding pressure interacts with future acquisition spreads.
That funding pressure is where the story gets interesting, and the full narrative for W. P. Carey shows how it could turn into overlooked upside or a slower burn than you expect.
Curious About Alternative Stock Paths
Fresh opportunities can move from quiet to flying once momentum builds and the crowd catches on. Scan curated shortlists before the best entries get caught, and consider acting while conditions suit your strategy.
- Look for yield-focused ideas and capital growth opportunities in one sweep by scanning a curated mix of 7 dividend fortresses while they may still be under the radar.
- Monitor potential infrastructure developments by focusing on power, grid and electrification leaders through a focused set of 40 power grid technology and infrastructure stocks before any broader attention develops.
- Explore AI-related opportunities by targeting cash-generative technology operators in a hand-picked pool of 37 profitable AI stocks that aren't just burning cash while valuations still look reasonable to you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com