
Talen Energy (TLN) Could Be 30% Undervalued After CEO Succession And $3.0b Buyback
Talen Energy (TLN) just reshaped its story for investors by pairing a planned CEO transition to Terry L. Nutt in early 2027 with a larger US$3.0b share repurchase authorization.
Recent trading shows a mixed picture for Talen Energy, with the share price rising 5.37% over the past week and 6.20% over the past month, yet still down 19.15% year to date and 12.04% over 90 days. At the same time, the 3 year total shareholder return remains very large, suggesting that the buyback expansion and the planned 2027 leadership change are being weighed against earlier gains and shifting risk perceptions.
Scan how Talen Energy compares with other power and infrastructure players by checking a curated set of 40 power grid technology and infrastructure stocks in the current market backdrop.
The share price has slipped this year while analyst targets and intrinsic estimates sit far higher. Is Talen Energy trading near fair value, or at a sizeable discount that the US$3.0b buyback alone will not explain?
Most Popular Narrative: 30% Undervalued
Talen Energy’s latest close of $320.77 sits well below the most followed fair value estimate of $460.59, which applies an 8.33% discount rate and incorporates detailed assumptions about PJM demand, long term contracts and future earnings power.
The current valuation implies Talen Energy is undervalued relative to its guidance and outlook, given management’s expectation of roughly $4b of adjusted free cash flow from mid 2026 through 2028 and a policy to return at least 70% of that amount to shareholders via buybacks.
See why 53 investors see Talen Energy as 30% undervalued.
Result: Fair Value of $460.59 (UNDERVALUED)
Still, that story can crack if softer PPL zone pricing persists, or if PJM capacity rule changes and data center politics keep squeezing Talen Energy’s projected cash engine.
Find out about the key risks to this Talen Energy narrative.
Another View: What Talen Energy’s Sales Multiple Is Saying
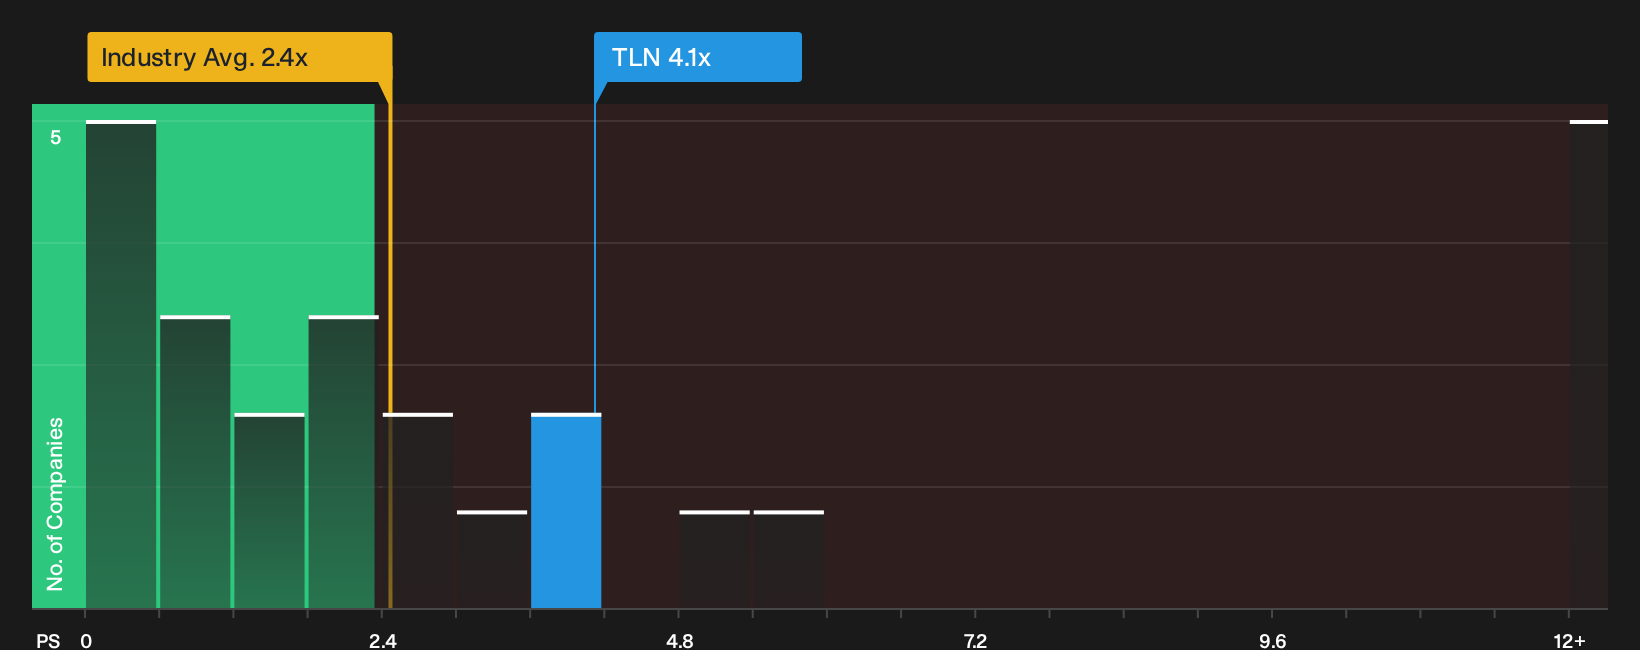
Talen Energy screens cheaply against fair value estimates, yet its P/S ratio of 4.1x is higher than the North American Renewable Energy industry on 2.4x and well above peers on 1.8x. The fair ratio sits at 4.8x. Is this a margin of safety or just richer expectations baked into the share price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear opportunity for Talen Energy, either way the data is on the table and worth checking yourself before the story moves. To weigh the 1 or more concerns against the 1 or more positives that other investors see, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Talen Energy?
If Talen Energy has sharpened how you think about value and risk, do not stop here. Broader context across other opportunities can sharpen your next decision.
- Target companies that combine meaningful discounts with strong fundamentals by scanning a curated set of 31 high quality undervalued stocks.
- Prioritize resilience first by reviewing a focused group of 31 resilient stocks with low risk scores that score well on financial strength and volatility measures.
- Hunt for future leaders hiding in plain sight by checking a hand picked pool of 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com