
New Oriental Education & Technology Group (EDU) Could Be 25% Undervalued Following Buyback Progress
New Oriental Education & Technology Group (EDU) is back in focus after a fresh update on its share repurchase activity, with management reporting completed buyback phases and a clearer picture of recent capital deployment.
Recent buyback headlines sit against a mixed price backdrop for New Oriental Education & Technology Group, with the share price down 6.27% over the past month but ahead 17.88% on a 90 day view. The 1 year total shareholder return of 8.21% and 5 year total shareholder return of 167.47% point to stronger longer run value creation than the shorter term share price moves suggest.
Compare New Oriental Education & Technology Group's aggressive buyback activity with other companies pursuing shareholder focused capital returns by scanning our curated list of 7 dividend fortresses
After a sharp ramp up in repurchases and a share price that has cooled over the past month but still sits higher over 90 days, investors may be wondering whether New Oriental Education & Technology Group still offers an attractive balance between risk and reward at US$55.44.
Most Popular Narrative: 25% Undervalued
Against New Oriental Education & Technology Group's last close of $55.44, the most followed narrative anchors fair value at $73.57. This points to a sizeable gap that the market has not closed and puts fresh focus on how its newer businesses and capital returns could influence that spread.
Expansion of newer lines such as non-academic tutoring, intelligent learning systems and devices, livestreaming e-commerce and tourism services, which have delivered more than 20% year-over-year revenue growth in recent quarters, provides additional revenue streams that can diversify earnings and support group top-line growth.
See why 18 investors see New Oriental Education & Technology Group as 25% undervalued.
Result: Fair Value of $73.57 (UNDERVALUED)
Still, recent pressure on non GAAP net income and the slower outlook for overseas test preparation work against the bullish narrative for New Oriental Education & Technology Group.
Find out about the key risks to this New Oriental Education & Technology Group narrative.
Another View On New Oriental Education & Technology Group’s Valuation
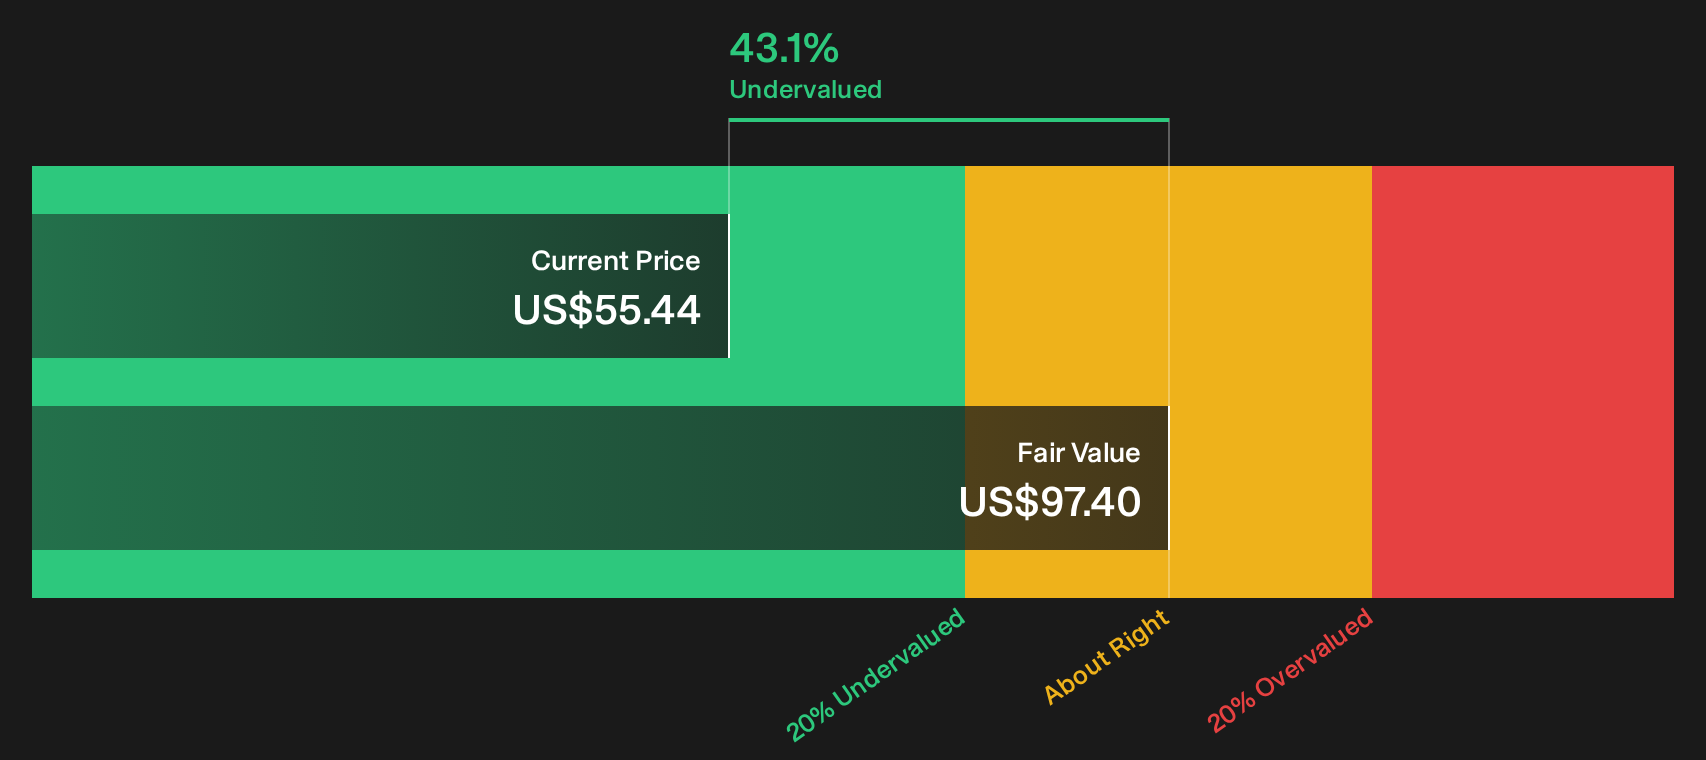
The DCF work-up presents New Oriental Education & Technology Group as attractive, with the shares at $55.44 compared with an SWS DCF value of $97.40. That indicates a wide gap that suggests potential upside. The question is whether you place more weight on long range cash flow estimates or on today’s market caution.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals so far on New Oriental Education & Technology Group, so treat this as your cue to move quickly, review the underlying data and decide where you land on 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond New Oriental Education & Technology Group?
If New Oriental Education & Technology Group has your attention, do not stop here. Use the screeners below to explore other opportunities that may fit your investment approach.
- Target quality at a discount by focusing on companies that combine strong fundamentals with room for potential re-rating through the 31 high quality undervalued stocks.
- Prioritise resilience by scanning for businesses with healthy finances and robust fundamentals using the list of solid balance sheet and fundamentals (26 results).
- Review a focused set of underfollowed companies with solid foundations through the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com