
Is Elisa Oyj (HLSE:ELISA) Undervalued Following Its New AI Partnership With Kempower?
Elisa Oyj’s new AI partnership with Kempower
Elisa Oyj (HLSE:ELISA) has signed an agreement with Kempower Corporation to deliver AI-powered IT services, ranging from end-user support to Device-as-a-Service. The services are aimed at supporting Kempower’s expanding global workforce and everyday digital operations.
Against this AI-focused agreement, Elisa Oyj’s share price has edged up over the past month with a 30-day share price return of 2.07%, although momentum looks softer when you zoom out, with the year to date share price return down 1.51% and the 1-year total shareholder return declining 12.78%.
Scan beyond Elisa Oyj and this Kempower deal by comparing it with other AI-focused enablers of digital infrastructure in our curated list of 90 AI infrastructure stocks.
So after a modest bounce and a longer spell of weaker returns, does Elisa Oyj still offer enough potential upside relative to the risks at today’s price, or has most of the easy value already been captured?
Most Popular Narrative: 8% Undervalued
Set against Elisa Oyj’s last close at €36.56, the most followed narrative fair value of €39.65 points to a modest valuation gap that still needs the underlying telecom and software story to play out as expected.
Scaling of international software services, including energy flexibility solutions such as Gridle and increasing recurring revenue streams, should drive higher quality, less cyclical topline growth and operating leverage, lifting group EBITDA and earnings as project timing headwinds ease.
See why 4 investors see Elisa Oyj as 8% undervalued.
Result: Fair Value of €39.65 (UNDERVALUED)
Still, if Finnish mobile competition continues to pressure pricing or international software projects face prolonged delays, the current Elisa Oyj narrative could come under stress.
Find out about the key risks to this Elisa Oyj narrative.
Another View on Elisa Oyj’s Valuation
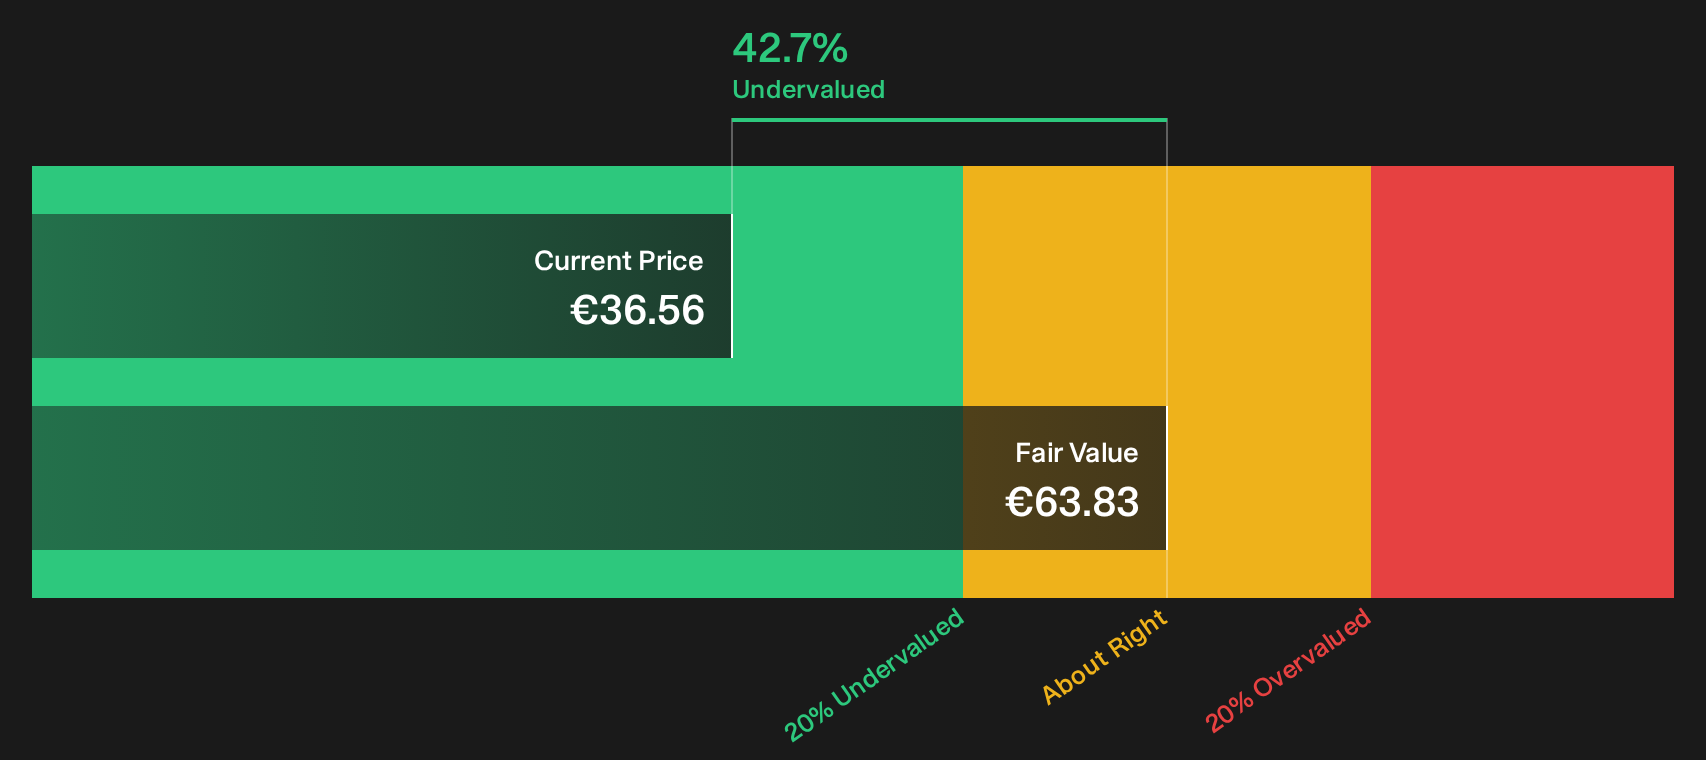
The SWS DCF model points to a fair value of €63.83 for Elisa Oyj compared with the current price of €36.56, which suggests the stock is trading at a sizeable discount based on expected future cash flows. If the model is roughly right, are investors leaning too heavily on near term caution?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals so far on Elisa Oyj, with both concerns and bright spots in the story, mean you should move quickly and weigh the evidence directly. Start by reviewing the 2 key rewards and 2 important warning signs
Looking for more Elisa Oyj style ideas?
If Elisa Oyj has you thinking harder about pricing and risk, do not stop here. Fresh opportunities often emerge where investors are not yet looking.
- Spot potential mispricings early by scanning companies that score well on value and quality in our 196 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with robust finances in the list of solid balance sheet and fundamentals (208 results).
- Get ahead of the crowd by filtering for under-the-radar opportunities in the 615 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com