
Seadrill (SDRL) Dropped, So Why Is It Drawing Fresh Attention?
Analyst sentiment shift puts Seadrill in focus
Improved analyst sentiment around Seadrill (SDRL), including an upgraded Zacks Rank to #1 and a very large increase in full year earnings estimates over the past 3 months, has pulled fresh attention to the stock.
The share price tells a mixed story. Seadrill is down 13.15% on a 1 month share price basis and has slipped over the past week, yet the 90 day share price return of 9.98% and year to date share price gain of 25.46% point to momentum that is still positive overall. This is supported by a 1 year total shareholder return of 38.94% and a 3 year total shareholder return of 4.33%.
Scan other oil and gas drillers with fresh analyst interest by checking the hand picked 19 high quality undiscovered gems alongside Seadrill for potential ideas in the same space.
Seadrill trades at a discount to both analyst targets and intrinsic estimates after a sharp pullback. Is that a pricing error, or the market’s way of flagging real risks around offshore drilling exposure and earnings quality?
Most Popular Narrative: 17% Undervalued
On this view, Seadrill’s estimated fair value of $52.78 sits above the last close at $43.85. This puts the current pullback against a backdrop of projected earnings and margin expansion supported by offshore drilling trends.
Supply of competitive ultra-deepwater rigs remains tight due to minimal newbuilds and uneconomical reactivations. This positions Seadrill's high-spec fleet for greater pricing power and margin improvement as the market rebalances, ultimately benefiting net margins and profitability.
See why 10 investors see Seadrill as 17% undervalued.
Result: Fair Value of $52.78 (UNDERVALUED)
Still, Seadrill’s narrative could easily be knocked off course if weaker rig utilization squeezes dayrates or if legal and regulatory disputes trigger heavier cash outflows.
Find out about the key risks to this Seadrill narrative.
Another way to look at Seadrill’s value
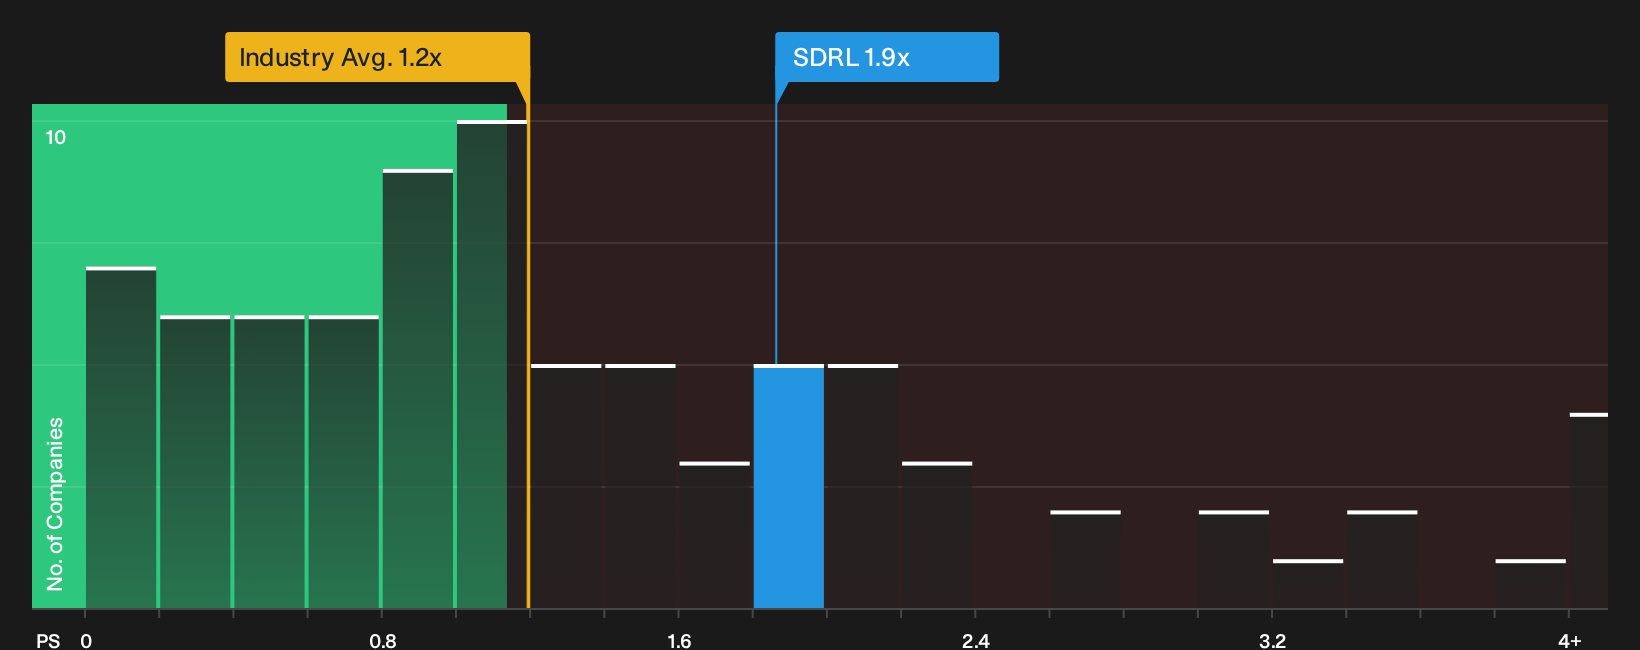
The analyst fair value narrative presents Seadrill as 17% undervalued around $52.78. A different lens tells a less comfortable story. On sales, SDRL trades on a P/S of 1.9x, while the US Energy Services group averages 1.2x and the fair ratio sits near 1.1x. This points to richer pricing and less margin for error if sentiment cools.
This gap means that even if earnings forecasts play out, investors are still paying a premium to both peers and the level the market could move toward over time. The key question is whether you view that premium as justified quality or as valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about the Seadrill story so far or sensing there is more behind the mixed signals? Move quickly, review the latest data, and weigh both sides through the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Seadrill?
Do not stop with Seadrill. Use the broader data set to widen your watchlist, compare business quality, and pressure test your thesis against fresh opportunities.
- Target powerful compounding potential by scanning for resilient blue chips in the 31 resilient stocks with low risk scores.
- Pressure test your valuation instincts against a curated pool of quality companies trading below intrinsic estimates using the 31 high quality undervalued stocks.
- Balance growth ambitions with cash returns by reviewing income opportunities through the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com