
What Hilton Hotels' Hawaii Curio Debut Means For Shareholders
- Hilton Worldwide Holdings has opened Hale Hokuala Kaua?i, Curio Collection by Hilton, a 210 room lifestyle resort in Hawai?i with extensive leisure, wellness and event amenities, expanding the company’s nearly 30 hotel presence across the islands.
- The debut of Curio Collection in Hawai?i gives Hilton a differentiated, experience led flag in a high demand resort market that can appeal to both leisure guests and groups through cultural programming, destination focused dining and more than 14,000 square feet of flexible event space.
- We will now see how Hilton’s Hawai?i Curio debut, with its experience led positioning and event capacity, could influence the investment narrative.
Scan beyond Hilton Worldwide Holdings and compare this Hawai?i resort move with other travel focused opportunities using a curated list of 19 high quality undiscovered gems.
Hilton Worldwide Holdings Investment Narrative Recap
To own Hilton Worldwide Holdings, investors are buying into a fee driven hotel platform that is working to turn a record 541,000 room pipeline into sustained 6% to 7% net unit growth, while keeping owners engaged through margin support programs. The Hale Hokuala opening fits that story, but on its own it does not change the near term picture.
The key swing factor still lies with RevPAR trends in more fragile regions and the timing of any payoff from heavy renovations at owned hotels in Europe and Japan, which currently reduce annual EBITDA by US$20 million to US$25 million. Weakness in the Middle East or China, or a slower than expected post renovation recovery, remains a bigger near term risk than one resort launch in Hawai?i.
Among recent initiatives, Hilton Worldwide Holdings has been vocal about expanding into lifestyle and niche concepts, including Undergraduate by Hilton and other conversion friendly flags. The Hawai?i Curio opening aligns with that push into experience led resorts that tend to carry higher fee rates and rely less on heavy balance sheet investment.
For catalysts, the key question is how efficiently Hilton Worldwide Holdings can layer new lifestyle locations such as Hale Hokuala onto a system where 36% to 40% of openings already come from conversions. Execution on this model, together with its AI ready tech stack and owner incentive programs such as RISE, will likely be more important to future system wide fee growth than any single property, even in a premium resort market.
Hilton Worldwide Holdings' current analyst narrative points to revenue of US$16.0b and earnings of US$2.7b by 2029, based on an assumed 46.3% yearly revenue growth rate and a shift in earnings from US$1.6b today to the US$2.7b forecast, which is an increase of about US$1.1b in profit over that period.
Uncover why Hilton Worldwide Holdings' fair value points to an 11% potential upside to its current price that could narrow quickly as expectations reset.
Exploring Other Perspectives
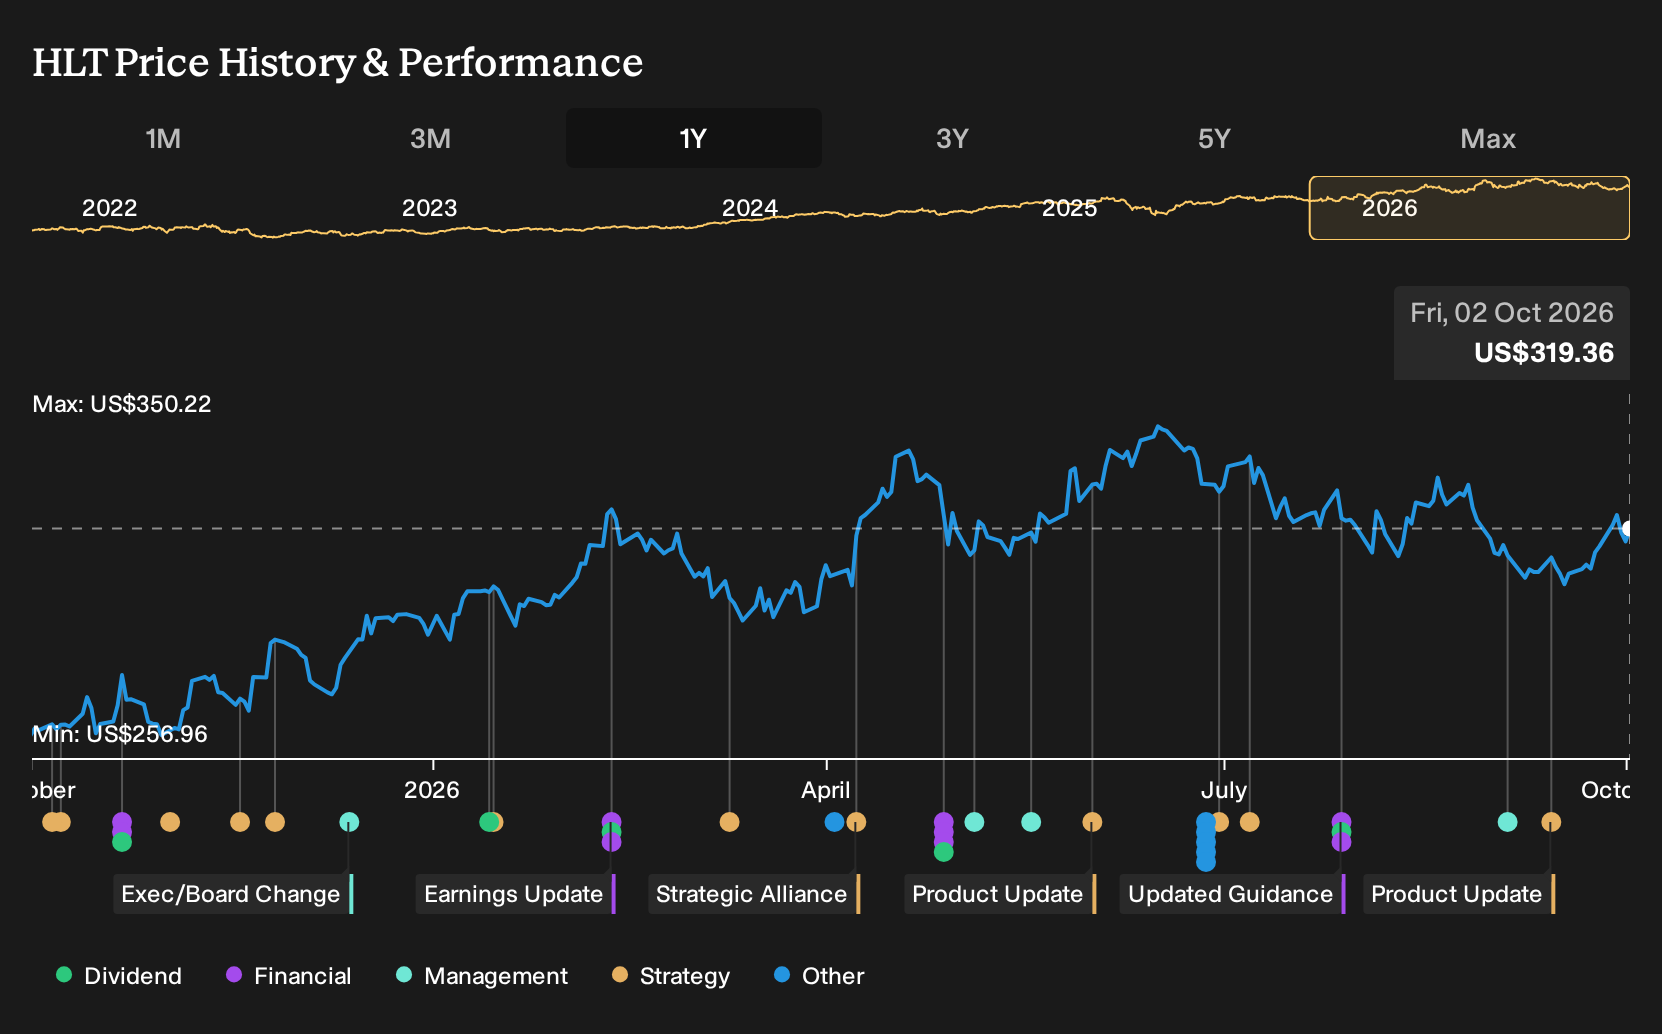
Two fair value estimates from the Simply Wall St Community span a wide range, from about US$264.81 to US$353, which already shows how far opinions on Hilton Worldwide Holdings can spread. Those views were formed before the Hale Hokuala opening, so you may want to weigh them against the risk of weaker RevPAR in regions such as the Middle East and China, as well as the potential lift from Hilton’s expanding lifestyle pipeline and tech investment.
Explore another Hilton Worldwide Holdings fair value estimate, including one that suggests potential upside of up to 11% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hilton Worldwide Holdings research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hilton Worldwide Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hilton Worldwide Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hilton Worldwide Holdings?
Once you have a view on Hilton Worldwide Holdings, it can help to widen the lens and compare it with other businesses that fit the kind of risk and return profile you prefer.
- If capital protection and smoother portfolio swings matter most to you, start with a 31 resilient stocks with low risk scores that may better align with a cautious approach.
- For investors focused on strong finances and durable operations, consider a list of solid balance sheet and fundamentals (26 results) that can provide a clearer picture of financially resilient businesses.
- If you are hunting for underfollowed potential, scan a 19 high quality undiscovered gems that might not yet be widely tracked by the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com