
Why Stewart Information Services (STC) Is Getting Attention Today
Stewart Information Services (STC) came under pressure after fresh housing finance data showed mortgage applications declining, while 30 year fixed rates reached multi year highs, weighing on mortgage insurers and title related stocks together.
For Stewart Information Services, the hit from weaker housing data comes on top of already soft momentum. The 7 day share price return is down 12.91% and the 30 day share price return is down 24.26% from a last close of $51.55, while a 3 year total shareholder return of 32.85% contrasts with a 1 year total shareholder return down 26.55%. This points to pressure in the recent trend after earlier gains.
Scan how Stewart Information Services compares with other housing and financial stocks under pressure from higher mortgage rates by reviewing the hand picked list of solid balance sheet and fundamentals (26 results).
Bulls point to Stewart Information Services’ longer term shareholder gains and recent revenue and net income expansion, while bears focus on the sharp pullback and housing pressure. Which case does the current valuation stack support next?
Most Popular Narrative: 38% Undervalued
Against a last close of $51.55, the most followed narrative pegs Stewart Information Services at a fair value of $83, pointing to a substantial gap that centers on housing recovery and technology spending.
The Real Estate Solutions business line sees opportunities for growth through expanding lender relationships and cross-selling products, which could stabilize and eventually increase net margins in the long term.
See why 2 investors see Stewart Information Services as 38% undervalued.
Result: Fair Value of $83 (UNDERVALUED)
Still, the story around Stewart Information Services can change quickly if housing activity remains weak or if higher data and employee costs continue to squeeze margins.
Find out about the key risks to this Stewart Information Services narrative.
Another View on Stewart Information Services Valuation
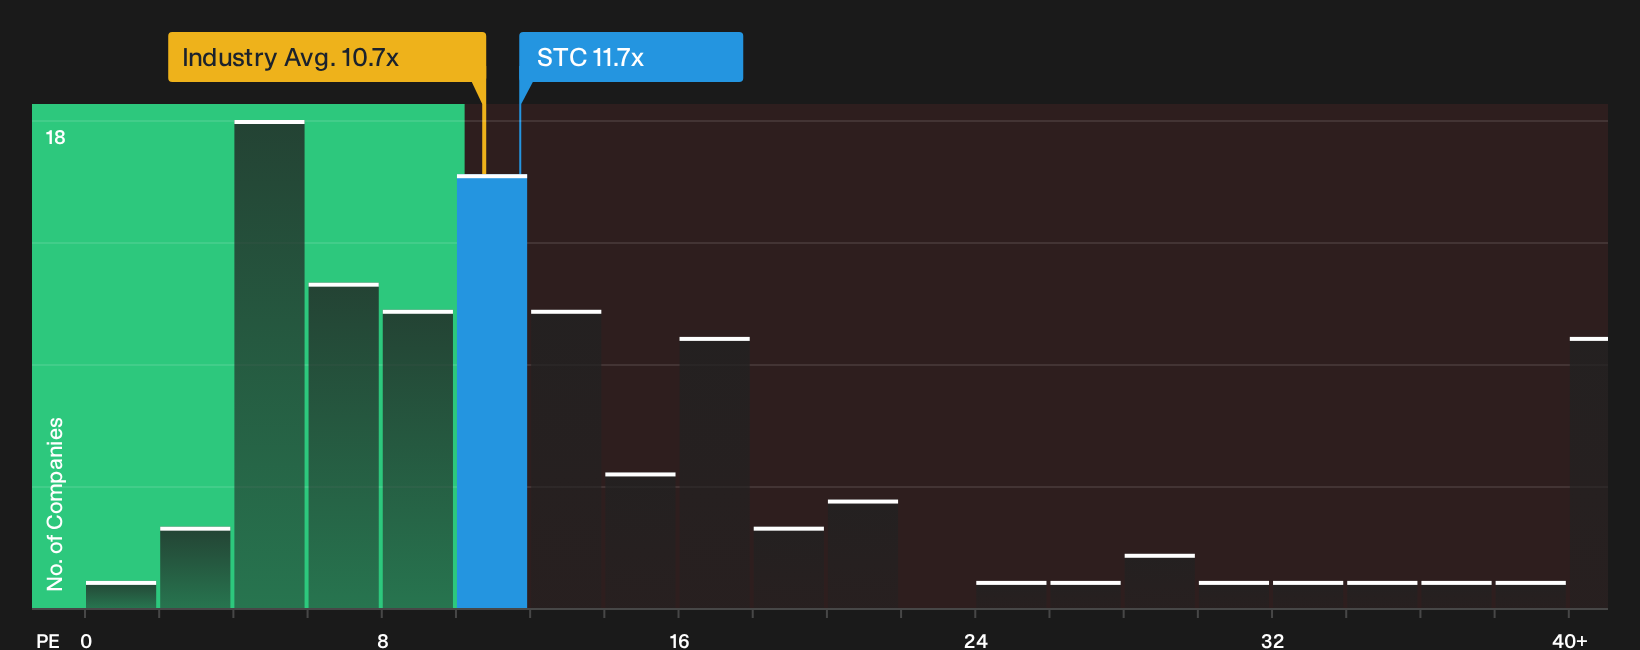
There is a twist when the conversation moves from narrative fair value to plain earnings multiples. Stewart Information Services trades on a P/E of 11.7x, which is higher than both the US Insurance industry on 10.6x and its peer group on 11.2x, yet below its own fair ratio of 13x.
That mix means investors are paying more than the sector average today. At the same time, the fair ratio suggests the market could still move higher before the shares look stretched. The real question is whether you see that gap as extra downside risk if expectations slip, or as room for sentiment to catch up if the story holds together.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Stewart Information Services is clearly split, so move quickly, review the full data set, and weigh the 5 key rewards against the recent share price pressure.
Looking for more investment ideas beyond Stewart Information Services?
If Stewart Information Services has you rethinking your portfolio mix, do not stop here. Use the Simply Wall Street screener to spot fresh opportunities before others catch on.
- Target potential mispricing by scanning a curated 31 high quality undervalued stocks that highlights stocks where fundamentals and current prices appear out of sync.
- Strengthen your income stream by checking a focused 7 dividend fortresses built around companies offering higher yields with support from their financial profiles.
- Dial down portfolio stress by reviewing a 31 resilient stocks with low risk scores aimed at businesses with more resilient balance sheets and risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com