
Learn Why The Bull Case For CTF Services (SEHK:659) Could Change Following Full Year Earnings
- CTF Services reported full year 2026 results with revenue and sales of HK$27,099.7 million, net income of HK$2,571.8 million, and basic earnings per share from continuing operations of HK$0.53.
- Management highlighted acquisition appetite, supported by slightly more than HK$2 billion of cash reserves and gearing targeted in the 40% to 45% range, alongside a proposed final dividend of HK$0.33 per share for the year ended June 30, 2026.
- The focus now turns to how CTF Services' investment narrative could be influenced by higher earnings together with fresh guidance on acquisition capacity.
Scan how CTF Services' earnings, dividend move and acquisition plans stack up against other financials by checking out a curated list of 196 high quality undervalued stocks.
CTF Services Investment Narrative Recap
To own CTF Services, you need to be comfortable with a diversified Hong Kong and Mainland focused group that leans heavily on construction, roads and financial services, with earnings partly shaped by large one off items. The latest full year numbers show higher sales and profit, but the key near term swing factor still looks like execution in logistics and construction rather than headline EPS.
The main risk in the short term remains exposure to Mainland driven activity and Hong Kong construction, where weaker demand could pressure occupancy and new contracts. Recent results and commentary do not materially change that risk balance. However, acquisition appetite slightly raises attention on gearing and integration discipline over the next year.
The acquisition commentary from the September 24 earnings call looks central to this update. Management flagged slightly more than HK$2b of cash reserves available after tax, interest and dividends, with a gearing target of 40% to 45%. That gives CTF Services room to keep adding to its insurance, logistics and overseas wealth platform while still talking about balance sheet limits.
For you, the operational question is whether those new deals and the existing four recent acquisitions can support occupancy, fee income and insurance flows quickly enough to justify the extra leverage. Execution risk around fit, pricing and integration stays high, especially alongside an unstable dividend track record and relatively low Return on Equity. Monitoring deal quality and post merger delivery becomes a key near term catalyst.
CTF Services' current earnings sit at HK$2.3b, with analysts projecting revenue growth of 3.4% a year and forecasting revenues of HK$27.7b and earnings of HK$3.7b by 2029. This implies an earnings increase of HK$1.4b from today.
Uncover why CTF Services' fair value points to a 24% potential upside to its current price that could narrow quickly as confidence builds.
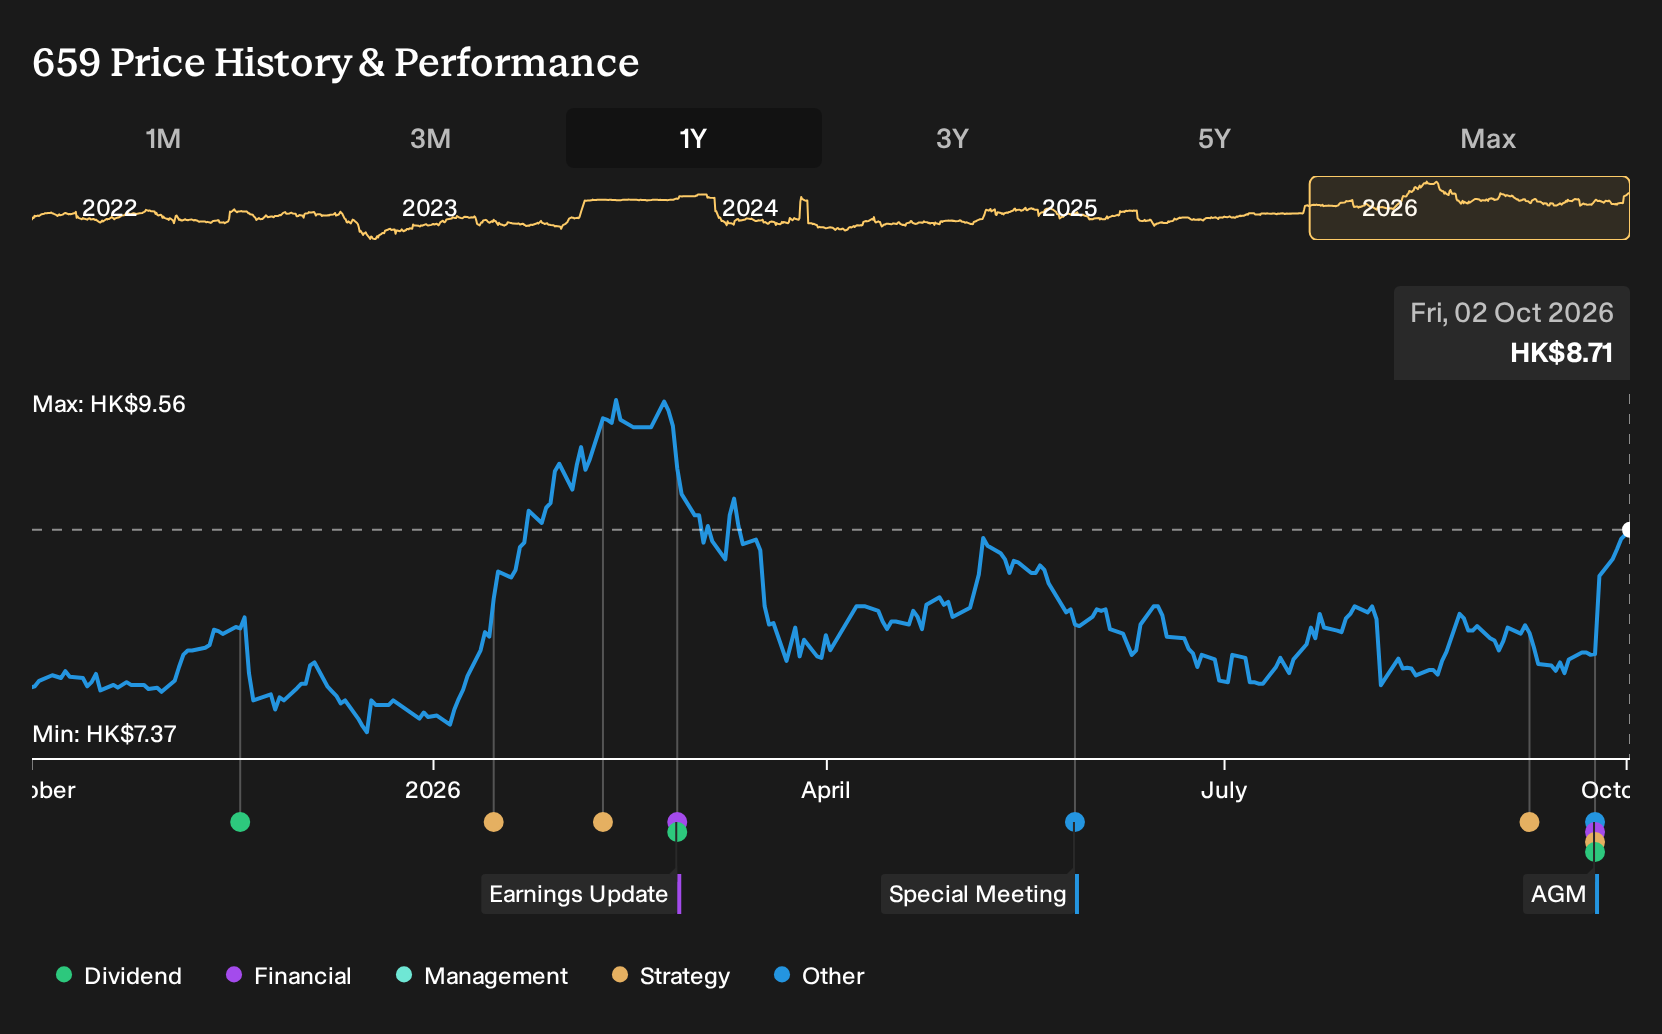
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly HK$10.8 to HK$77.21, which shows how far apart private investors can be on CTF Services. Those views were formed before the latest earnings, dividend proposal and acquisition commentary. As a result, fresh information on gearing, visitor mix and Hong Kong construction exposure could shift sentiment. If you want a fuller picture, explore several alternative viewpoints from the Community before forming your own stance.
Explore another CTF Services fair value estimate, including one that suggests potential upside of up to 787% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CTF Services research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CTF Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CTF Services' overall financial health at a glance.
Looking For More Ideas Beyond CTF Services?
If CTF Services has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you quickly surface other companies that match different risk and return profiles.
- For investors who want potential mispricing with stronger fundamentals, consider a curated group of 196 high quality undervalued stocks that may warrant a closer look beside CTF Services.
- If capital preservation and steadier profiles rank higher for you, filter the market using a 228 resilient stocks with low risk scores that focuses on resilience over excitement.
- Those hunting for higher quality outliers off the beaten path can work through a 615 high quality undiscovered gems that highlights companies with solid metrics but limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com